When To Follow The Rules — And When To Break Them
By J.D. ROTH December 2019
Last night's recipe from HelloFresh was Bulgogi Pork Tenderloin. As always, the instructions were clear and easy to follow. As always, it took me about twice as long to prep things as the recipe card said they would.
I chopped the vegetables, boiled the rice, seared the meat, made the sauce. But when I reached the final step — “finish and serve” — I hit a wall of sorts.
“Ugh,” I said to Kim, who was playing with our three cats and one dog simultaneously. “The recipe calls for a tablespoon of butter in the rice. I hate adding butter to rice. It makes it gummy and gross. But HelloFresh always wants me to do it.”
“I like butter in my rice,” Kim said, throwing a bacon ball for the dog while kicking a catnip toy for the cats. “But if you don't like it, don't add it.”
I sighed. Of course, she was right: Just don't add the butter! Such an obvious solution, right? Yes — and no.
You see, I am fundamentally a Rule Follower. When I'm cooking, I follow the recipe exactly. When I'm building an IKEA desk for my new office, I follow the instructions exactly. On the road, I generally stick to the speed limit (which sometimes drives Kim nuts). I used to take pride that never once did I cheat on my homework or tests in high school and college — and I never helped anyone else cheat either.
As I said: I am, fundamentally, a Rule Follower.
This has been true when it comes to managing my money too. Since beginning my quest to become the CFO of my own life fifteen years ago, I've surrendered to wiser minds than mine. I tend to heed the time-tested “rules of money”, rules like:
When average people like me are wondering how to invest, the best answer is usually “set up automatic contributions to an index fund”.
When setting up a budget, it's more important to pay attention to the Big Picture than it is to fret over details. Follow the balanced money formula and you should do okay.
When you want to get out of debt, use the debt snowball method. If possible, pay high-interest debts first. Many folks (including me) have more success, though, if they pay off low-balance debts first. And still others use a debt snowball approach in which they start by tackling the debts with the greatest emotional weight.
If you're going to use them, know how to use credit cards wisely. If you're unable to use credit without digging yourself into debt, then throw away the “shovel”.And so on.
Following these rules has proved profitable. These “rules” are rules for a reason. Because they work. They allow folks to get out of debt and build wealth. Crazy, right?
Here's the thing, though. As effective as these financial rules have been for me, as much as I like strictly following a recipe, I've also come to realize that sometimes it makes sense to (gasp!) break the rules.
The challenge, then, is determining when to follow the rules — and when to break them.
To continue reading, please go to the original article here:
Tomorrow’s Election Changes Nothing About The National Debt
Notes From the Field By james Hickman (Simon Black/Sovereign Man) November 2, 2026
Johnny Moon was homeless and unemployed in the early 2000s. A high school dropout with a bad drug habit, Moon was hardly someone that banks would consider creditworthy.
And yet, over the course of a single year, he was able to borrow more than $600,000 to buy five different investment properties.
7 Surprising Benefits of Failure
By Kentin Waits WISEBREAD
Everyone loves a success story, and the world is filled with them. But what about stories of failure? Can't they be as just as educational? Just as inspirational? Equally insightful?
After all, a single big win is often built on several losses. It's a truth perfectly captured in the words of Japanese industrialist and automaker, Soichiro Honda, "Success is 99% failure."
Brazil’s Massive Crash Is A Sign Of Things To Come In The West
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 29, 2026
On Sunday night, Brazil re-elected its left-wing president, Lula da Silva. On Monday morning the São Paulo stock market fell so hard at the open that the exchange halted trading for the first time since the pandemic. When trading resumed, Brazil’s stock market kept falling.
6 Attitudes That Breed Financial Failure
By Kentin Waits WiseBread
Financial success or failure is often the result of attitudes — both conscious and unconscious — that affect our behavior. No amount of budgeting and self-control can help us when we’re up against ingrained ideas about money management, spending, and debt. If you’re having a tough time shifting your financial behavior, maybe it’s time to change your mind about money. Here are six common attitudes that work against us financially.
Plan B Options for folks on Social Security
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 27, 2026
In the early morning hours of February 7, 1937, a young American named Stirling Dickinson got off a train in central Mexico and rode into San Miguel de Allende on a mule-drawn cart.
He and a Princeton classmate were months into a trip around Mexico looking for a quiet place to write, and a Mexican opera singer had told them to try San Miguel.
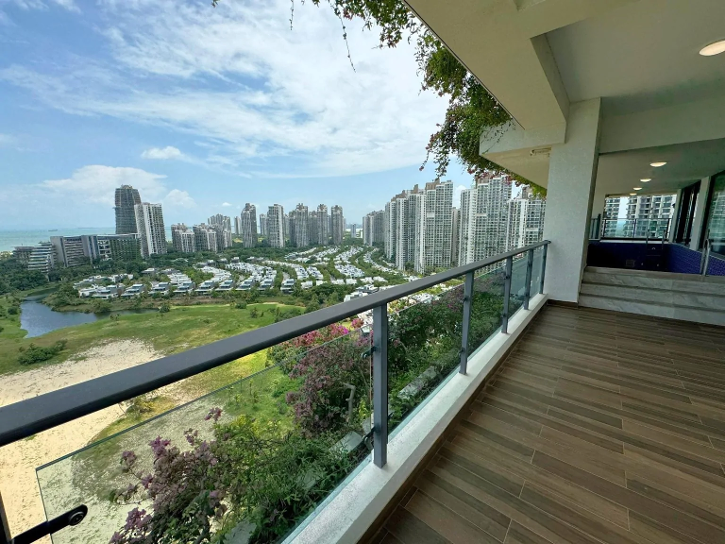
A Condo in this Ghost City Gets You Ten Years Residency
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 22, 2026
On March 6, 2016, Malaysia’s prime minister, Najib Razak, turned up for the grand opening of a city that did not exist yet, two kilometers off the coast from Singapore.
It was called Forest City, and the plan was enormous. One of the largest property developers in the world came in to build four artificial islands in the strait and put a “smart, green” city of 700,000 people on them, at a cost of roughly $100 billion.
Avoid These 4 Common Mistakes When You Get Rich Overnight
September 4, 2025 by Laura Bogart GoBankingRates
You’re about to score a financial touchdown. Maybe you’ve crushed it at work and landed a sweet promotion. Perhaps you’ve won a lottery or stumbled into a side hustle that suddenly pays off. As you near the end zone, heart pounding, head full of dreams, you can’t afford (literally) to fumble. Whether you’re blindsided by unexpected taxes or tripped up by bad financial advice, you have a lot to lose if you drop the ball.
6 Common Excuses for Not Saving Money By Tara Struyk
Have you ever settled on a new exercise program, only to get a bad cold a few days in and happily throw yourself on the couch, relieved to have a handy excuse? Excuses must be human nature; I know I usually make them when I'm facing something that’s new, that's hard, or that I just don’t enjoy. And I’ve certainly made excuses when it comes to money.
In the years that I’ve been writing about personal finance and investing, I’ve also heard my fair share of excuses, mostly from readers who don’t agree with my advice. The problem is, unlike good financial habits, excuses are easy to come by, even though most of them just don’t stand up to reason. Check out some of the ones I’ve heard most frequently so far.
How To Make Strategic Cash Bucketing Work For You
Last Edited Sep 16, 2026| Angelena Mascilli
Cash bucketing – or categorizing your funds based on specific expenses or goals – can help you organize your financial life.
Cash and other liquid assets may be the ideal place for buckets of money that you may need to access soon to cover expenses or capitalize on new investment opportunities.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
There’s a Different Way
Notes From the Field By James Hickman (Simon Black / Sovereign Man) November 6, 2026
A friend of mine got legal residency in New Zealand a couple of years ago as global tensions rose around wars in Ukraine and the Middle East. He was only half joking about why. His reasoning is that if WW3 breaks out and the nukes start flying, he would want to be in New Zealand.
But he’s not picking up his life, abandoning all caution, and permanently moving to a new country. He just has a plan, and the basics in place.