Debt management: How To Avoid Common, But Costly, Money Mistakes
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
As debt burdens have grown, so too has the importance of making the right repayment decisions. Managing debt involves meaningful trade-offs. Even decisions that feel financially responsible—such as paying down a mortgage faster or holding excess cash beyond emergency savings—can sometimes lead to higher overall costs or lower long-term wealth.3 An important but often overlooked insight is that debt repayment is just another form of savings.
Vanguard researchers explored the problems that can arise when investors fail to coordinate borrowing and savings decisions. Their research paper, Balancing Saving and Debt Paydown: Money Mistakes to Avoid (de la Fuente et al., 2026), presents the results. Here are two common mistakes and some practical ways investors can address them:
Mistake #1: Paying down high-interest debt too slowly
The researchers found that 35% of all Vanguard investors carry revolving credit card debt and the average balance carried is about $4,100. With the average credit card interest rate of 21%, that balance costs more than $800 a year in interest.4
Yet 57% of investors with credit card debt could pay it off by redirecting dollars that are earning lower returns. Specifically, 67% of investors with brokerage accounts have cash in their accounts that could pay off some or all of their credit card debt, while 60% of 401(k) investors contribute above their company match limit in their retirement plan.
Additionally, 30% of all investors with credit card debt make extra payments on other lower-interest debts, like mortgages or auto loans.
“The typical investor could pay off credit card debt in less than 18 months if they reallocated this extra cash toward credit card payments,” said Malena de la Fuente, Vanguard investment strategy analyst and lead author of the paper.
Many investors carry revolving credit card debt despite having cash available
Mistake #2: Paying down low-interest debt too quickly
While some investors pay down credit card debt too slowly, others speed up paying down lower-interest debt by prepaying loans.
Within Vanguard-administered 401(k) plans, roughly 50% of employees with mortgage, auto, or student debt make extra payments (payments made in addition to the minimum monthly payment) at least once per year.
At the same time, 30% of these prepayers are leaving employer-match dollars on the table—costing them almost $1,100 a year in missed 401(k) contributions.
Secured debt like auto loans and mortgages usually have single-digit interest rates, while employers often match 401(k) contributions at 50 or 100 cents on the dollar.
This means that—when considered as an investment—matched retirement contributions have a much higher rate of return than extra loan payments.
“Riskless returns of 50%–100% are hard to come by in financial markets,” said Aaron Goodman, Vanguard senior investment strategist and one of the paper’s coauthors. “That makes earning the full 401(k) match a priority before prepaying low-interest debt.”
Prepaying debt can come at the cost of the full 401(k) match
TO READ MORE:
9 Ways Retirement Will Be Different in 2026
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
Even if retirement is still a few years away, these changes could affect how you prepare to leave the 9-to-5. Here are nine things affecting retirees’ financial well-being that will be different in the coming year.
More Ways to Benefit
1. Social Security gets COLA boost
Social Security recipients get a 2.8 percent benefit bump in January, when the annual cost-of-living adjustment (COLA) kicks in. The average monthly retirement payment is set to increase by an estimated $56, from $2,015 to $2,071, according to the Social Security Administration (SSA), and the average survivor benefit for a widowed spouse will rise by $52, from $1,867 to $1,919.
The 2026 COLA reflects changes in prices for a set of consumer goods and services from the third quarter of 2024 to the third quarter of 2025, as measured by a federal price index. Inflation ticked up over that time, resulting in a slightly higher increase compared with 2025’s 2.5 percent COLA.
People collecting retirement, family, survivor or Social Security Disability Insurance (SSDI) benefits will see the COLA boost in their January payments. Those receiving Supplemental Security Income (SSI) — a benefit for people with very limited income and assets who are 65 and older, blind or have a disability that is administered by the SSA — will get their first inflation-adjusted payment on Dec. 31.
The COLA’s impact on beneficiaries’ purchasing power will depend largely on inflation trends in 2026. If inflation cools, the 2.8 percent benefit increase could provide retirees with a modest financial cushion. But if prices continue to climb, the COLA may leave beneficiaries struggling to manage their expenses.
2. Medicare premiums up nearly 10%
One cost that will put a dent in the COLA: Medicare premiums. The base rate for Medicare Part B, which covers doctor visits and other outpatient care, is going up by 9.7 percent in 2026, from $185 to $202.90 a month.
Most Medicare enrollees’ premiums are deducted directly from their Social Security payments, so the Part B increase effectively reduces their COLA by $17.90 a month. Premiums are higher for what Medicare considers high earners — in 2026, those are beneficiaries with incomes above $109,000 for individual taxpayers and $218,000 for couples filing jointly.
The annual deductible for Part B is also rising, from $257 in 2025 to $283 in 2026.
People with Medicare Advantage (MA) coverage or Medicare Part D prescription drug plans may see varying costs, as these plans are provided by private insurers. According to Medicare estimates, the average monthly premium for an MA plan will decline by $2.40 a month, from $16.40 in 2025 to $14.00 in 2026.
The average premium for a stand-alone Part D prescription plan is projected to be $34.50 next year, a reduction of $3.81 from 2025. The cap on annual out-of-pocket costs for prescriptions under both Part D policies and drug coverage in MA plans will increase from $2,000 to $2,100.
3. Retirement plan contribution caps rise
The IRS sets annual limits on the amount you can put into an individual retirement account (IRA) or workplace retirement plan, with multiple tiers.
For IRAs, the standard contribution cap for the 2026 tax year is $7,500, up from $7,000 in 2025. The maximum catch-up contribution for savers age 50 and older is going up from $1,000 to $1,100, meaning older adults can sock away up to $8,600 in an IRA in 2026. (You can still make a contribution that counts for 2025 tax purposes — the deadline is April 15, 2026.)
If you have a job-based retirement account, such as a 401(k), 403(b) or Thrift Savings Plan, the 2026 contribution limit for workers age 49 and younger is $24,500, $1,000 more than the 2025 cap. For workplace plans, there are two catch-up levels:
Workers ages 50 to 59 and 64-plus have a catch-up cap of $8,000 in 2026 (up from $7,500 in 2025), for a maximum contribution of $32,500.
The so-called “super catch-up” limit for workers ages 60 to 63 is $11,250 (the same as in 2025), for a total contribution cap of $35,750.
4. Standard tax deduction going up
The IRS increases the standard deduction most years to account for inflation, and this year, Congress juiced it a bit more as part of the “One Big Beautiful Bill” (OBBB) enacted in July. That’s especially meaningful for Americans age 65 and over, who have a bigger standard deduction than younger taxpayers do.
Here are the regular standard deductions for 2025 tax returns (the ones you must file by April 15, 2026):
Married couple filing jointly: $31,500 (up from $29,200 in the 2024 tax year)
Single or married filing separately: $15,750 (up from $14,600)
Head of household: $23,625 (up from $21,900)
And here are the standard deductions for taxpayers age 65-plus:
Married filing jointly (if one or both spouses are 65-plus): $34,700 (up from $32,300 in 2024)
Single or married filing separately: $17,750 (up from $16,550)
Head of household: $25,625 (up from $23,850)
5. Many retirees get a new tax break
Along with the higher standard deduction, the OBBB included a brand-new tax break of up to $6,000 for people age 65 and older that could reduce or fully offset taxes on Social Security income for millions of Americans.
The provision, which AARP supported including in the OBBB, applies to people who are at least 65 at the end of 2025. Qualifying individual taxpayers with a modified adjusted gross income (MAGI) of up to $75,000, and spouses filing jointly with a combined MAGI of up to $150,000, can deduct up to $6,000 each from their taxable income.
The deduction is reduced at higher income levels, up to $175,000 for single filers and $250,000 for couples. Above those thresholds, you are not eligible. It is also temporary — under the OBBB, it is scheduled to sunset after the 2028 tax year.
6. Full retirement age changes
Under a law Congress passed in 1983, full retirement age (FRA) for Social Security — the age at which you become eligible to claim 100 percent of the retirement benefit calculated from your lifetime earnings — has been going up incrementally from 65 to 67, based on year of birth. That drawn-out change is nearly complete.
FRA will settle at 67 for people born in 1960 and after, but for those born in 1959, it’s 66 and 10 months. You’ll reach it in 2026 if you were born from March 2, 1959, through Jan. 1, 1960.
To Read More: https://www.aarp.org/money/retirement/biggest-changes-2026/
12 Key Habits for Achieving Financial Freedom
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
Financial freedom means having enough savings, investments, and cash on hand to afford the lifestyle you want for yourself and your family. It also means budgeting to grow a nest egg, allowing you to retire or pursue your dreams. These 12 habits can put you on the right path.
1. Establish Clear Financial Goals
Individuals have different financial goals. Outline your objectives and get specific about amounts and deadlines. Determine your short and long-term lifestyles, how much you need to reach your milestones, and at what age you will be. Count backward from your deadline and establish financial mileposts.
2. Create a Practical Budget
Create a monthly household budget to ensure bills are paid and savings are on track. Maintaining a budget is a routine that reinforces your goals and helps squash the temptation to splurge.
3. Reduce Credit Card Debt
Credit cards and other high-interest consumer loans are toxic to wealth-building. Make it a point to pay off the full balance each month. Student loans, mortgages, and similar loans typically have much lower interest rates, and paying these lower-interest loans on time will build good credit.
4. Automate Your Savings
Pay yourself first. Ideally, emergency and retirement money should come from your account the day you receive your paycheck. You can also choose an automatic deposit into an emergency fund, which can be tapped for unexpected expenses.
Enroll in your workplace retirement plan and capture any employer matching benefit. Tax-advantaged retirement accounts have rules that make it difficult to get your hands on your cash should you suddenly need it, so that account should not be your emergency fund.
5. Begin Your Investment Journey
The magic of compound interest helps you grow your money exponentially. An online brokerage account makes it easy for individuals to learn how to invest, create a manageable portfolio, and make weekly or monthly contributions.
Tip
See Investopedia's choices for Best Online Brokers for Beginners.
6. Monitor and Improve Your Credit Score
Your credit score helps determine the interest rate offered to you when buying a new car or refinancing a home. It also impacts the amount you pay for essentials like car or life insurance premiums. Maintain your payment schedules and check your credit score often to ensure your good habits are paying off.
Important
Consumers in the U.S. are eligible to request a free copy of their credit report annually from the three reporting companies, Equifax, Experian, and TransUnion, at AnnualCreditReport.com.1
7. Master Negotiation Techniques
Many Americans hesitate to negotiate for goods and services. However, small businesses, in particular, may be open to negotiation. Buying in bulk or positioning yourself as a repeat customer provides discounts at larger chain stores.
8. Continue to Educate Yourself Financially
Review relevant changes in tax law to ensure that all adjustments and deductions are maximized each year. Keep up with financial news and developments in the stock market, and do not hesitate to adjust your investment portfolio accordingly.
9. Properly Maintain Your Assets
According to J.P. Morgan, house prices were expected to increase by 3% in 2025.2 Maintaining real estate will help safeguard or even increase its value. Taking good care of other items like cars and lawnmowers helps them last longer and saves money in the long run.
To Read More: https://www.investopedia.com/articles/personal-finance/112015/these-10-habits-will-help-you-reach-financial-freedom.asp
The Seven Deadly Sins Of Personal Finance
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
Ten years ago, I wrote that I particularly like Wilder's list of the seven enemies to financial success (which is my phrase, not his). I still like them. He writes:
If you want to become and stay the quiet millionaire, you must plan and manage your financial way of life…You must be proactive in order to obtain the financial life you want. By doing this, you will overcome the seven major obstacles to financial success.
Wilder is saying that we know there are certain common barriers to wealth. These obstacles arise for everyone. Because of this, it's possible to plan in advance to cope with them. First, however, we have to be able to name these enemies so that we can prepare the proper weapons to fight them.
The Seven Enemies of Financial Success
According to Wilder, the seven enemies of financial success are:
Lack of discipline. Without discipline, it's difficult to build wealth. In fact, it's impossible to get rich — slowly or otherwise — if you spend more than you earn. The math just doesn't work. Wilder also warns against compulsive spending, and he urges readers to track where their money is going.
Materialism. Stuff will not enrich your life. It's so very easy to find yourself “keeping up with the Joneses”, succumbing to lifestyle inflation. But materialism breeds discontent. Instead, Wilder says, focus on intellectual and spiritual pursuits to obtain fulfillment.’
Debt. Not all debt is bad, of course. A reasonable mortgage on a sensible home is fine. But consumer debt — or a bad mortgage on a big house — is an enemy to financial success. In fact, bad debt may be the biggest enemy to financial success.
Taxes. It's our responsibility to pay the taxes we owe, but we're under no obligation to pay more than that. “It is not unpatriotic to reduce paying your taxes,” Wilder writes. We should instead actively work to keep our tax burden as low as possible.
Inflation. Inflation is wealth's silent enemy. It will not destroy you all at once. But it's always there, nibbling at the corners of your life, consuming a little cash every year. It's impossible to keep inflation completely at bay, but you can learn to mitigate its effects.
Investment mistakes. Poorly structured investment portfolios can be a killer. This enemy is fought through education, through an understanding of diversification and asset allocation, by taking the emotion out of investing.
Emergencies. The final enemy to financial success is the unexpected: unemployment, death, illness, and legal complications. Without a plan for emergencies, you leave yourself at the mercy of the fickle fates. Carry adequate insurance and maintain an emergency fund!
I've fought all of these enemies at one time or another. I still fight some from time to time. I feel like I have a good handle on investment mistakes and saving for emergencies, but my tax bill this year was onerous due to my own poor planning. And, of course, I've always struggled with discipline.
The Seven Deadly Sins and the Last Four Things
The Seven Deadly Sins (and the Last Four Things) by Hieronymus Bosch
The Seven Deadly Sins of Personal Finance
Wilder's seven enemies to financial success always reminds me of Catholicism's traditional list of seven deadly sins. This catalog of transgressions has a long, complicated (and intersting) history. Today, the seven deadly sins are considered to be:
Vanity (or Pride). An inflated belief in your own abilities.
Envy. The desire to have what others have.
Gluttony. Consuming more than you need, especially with regards to food and drink.
Lust. A passion or longing for bodily pleasure.
Wrath (or Anger). The tendency toward indignation and the desire for vengeance. Hatred toward others.
Greed. The desire for material wealth or gain.
Sloth. The avoidance of work. Laziness. A failure to act or make use of your talents.
What would happen if we combined Wilder's idea — seven enemies to financial success — with this list of seven deadly sins? If we were to make a list of seven deadly financial sins, what would those be? Off the top of my head, these seem like good candidates:
Sloth. The avoidance of work. Laziness. A failure to act or make use of your talents. Procrastination. Expecting others to solve your problems.
Envy. The desire to have what others have. Comparing yourself to others. Keeping up with the Joneses.
Gluttony. Consuming more than you need. Succumbing to lifestyle inflation, the endless desire to have more. Never being satisfied with what you already have. The inability to defer gratification. Impatience.
Aimlessness. A failure to plan for the future. A lack of purpose or direction. Failing to track your progress is also a form of aimlessness.
Improvidence. A lack of prudence or care in managing your resources. Spending mindlessly. Wasting what you already have. Not taking care of your possessions. Replacing the things you own before they need to be replaced.
Myopia. Making decisions without considering greater implications. Focusing on small, easy steps that make no real difference (clipping coupons, maybe) while ignoring the big things that destroy your financial future (paying too much for housing, for instance).
Ignorance. A lack of financial education. Putting blind faith in outside advisors — or the news. Failing to do your own research.
Although this list is spontaneous, I like it. These really do feel like seven barriers that prevent people from succeeding with money. But I'm sure it's possible to come up with other (possibly more grievous) sins.
What do you think? If you were to list the seven deadly sins of personal finance, what would you include? And why?
https://www.getrichslowly.org/
5 Reasons Not to Use Debit Cards When You Shop Online
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
But when shopping online, there are reasons to consider using a credit card instead.
Using a debit card for online purchases can mean enduring greater losses if you're a victim of fraud. Plus, you're giving up valuable consumer protections and rewards each time you make a purchase with debit in a store or online.
Here are all the reasons you may want to stop using debit and use a credit card instead.
1. You may be putting yourself at risk for fraud
It's easy to assume you won't be liable for fraudulent purchases made with your debit card or checking account number, but this isn't the case. Where most credit cards come with zero fraud liability thanks to rules enacted in the Fair Credit Billing Act (FCBA), the same protections don't apply to transactions made with a debit card.
In fact, someone who finds your debit card number could wipe out all the money in your accounts. If you don't notice or report it in time, you won't have any way to get your money back.
According to the Federal Trade Commission (FTC), your level of liability depends on when you notice the fraud and report it. For example, if you report fraud within two business days after it's noticed, you're only liable for up to $50 in losses. If you report fraud within two to 60 days of your statement being mailed to you, you're only liable for up to $500. If you fail to report fraud once it's been 60 days from the date your statement was mailed to you, the FTC notes that you could lose "all the money taken from your ATM/debit card account, and possibly more; for example, money in accounts linked to your debit account."
2. You're missing out on rewards
In addition to putting yourself at risk for fraud, there are plenty of ways you're missing out when you shop online with a debit card. For example, you could be earning cash back or travel rewards if you made the same purchases with a rewards or travel credit card. These rewards can add up quickly, making it easier to see the world or splurge on merchandise, gift cards, and more.
While you can typically earn 1% to 3% back with a rewards or travel credit card, you can also double up on rewards by shopping through a cash back, travel rewards, or airline portal. You can also shop in portals with a debit card in some cases, but you'll mostly be limited to earning airline miles or cash back. (See also: How to Use Airline Shopping Portals to Cash In On Rewards)
3. You won't earn any sign-up bonuses
Using a debit card when you shop online also means giving up on the possibility of earning big sign-up bonuses. Keep in mind that many rewards credit cards offer consumers the chance to earn bonuses worth $500 or more when they meet a minimum spending requirement within a few months.
You may think you need to pay the annual fee on a credit card to qualify for sign-up bonuses or ongoing rewards, but this is far from the truth. The reality is, there are plenty of rewards credit cards that dole out sizable bonuses, ongoing rewards, and more without charging a fee each year. (See also: Don't Make These 6 Credit Card Sign-up Bonus Mistakes)
To Read More: https://www.wisebread.com/5-reasons-not-to-use-debit-cards-when-you-shop-online
5 Pieces of Financial Advice to Avoid at All Costs
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
You should never entrust a money decision entirely to someone else. I know, I know: Sometimes you'd rather pass the buck. But remember, we're talking about your security, your future, your peace of mind.
It's one thing to hire an investment adviser to help you choose funds for your IRA, or to cheerlead a spouse as he or she sets up a 529 plan to help pay your child's college tuition. It's quite another to tune out completely.
Find an hour or so a month to peruse a personal finance Web site or a magazine like Money or Kiplinger's, which will keep you up-to-date on the basics. The blog at Mint.com is also a great resource, with posts on everything from choosing a mortgage to spotting medical bill errors. By educating yourself in these simple ways, you'll sidestep all sorts of traps. Here's some common advice you should disregard—and more profitable leads to follow instead.
Don't Buy It: "Your child's college degree is a great investment."
A blanket statement like this is missing a crucial qualifier: An affordable college degree is a great investment. The unemployment rate for Americans 25 years of age and older is a lot lower for college graduates than for those with only a high school diploma (3.9 versus 8.1 percent).
But that doesn't mean you should tell your kids to set their sights on any school—regardless of whether it will leave you with a crushing amount of debt. All too often, parents fail to strategize when it comes to paying for education and end up getting off the track to retiring comfortably.
Ironically, this does kids a major disservice: If you lack sufficient retirement savings down the line, your children are the ones who'll bear the burden of supporting you.
A Better Idea: Think in terms of long-run affordability. (This goes for you and your child, since I firmly believe kids must borrow for school before parents dip into their savings or take out a loan.) Mark Kantrowitz, publisher of FinAid.org, says students should limit their total borrowing to an amount no greater than what they can reasonably expect to earn in their first year of full-time work; borrow more, and the odds of running into payback problems and default soar.
Check out typical starting salaries at Salary.com; even if your child doesn't have a specific career in mind yet, it's a great exercise for families to do together, to start getting grounded in postcollege reality.
When it comes to financing options, remember that federal Perkins and Stafford loans offer the best deals; private loans are risky and can end up being far too expensive. The maximum Stafford loan amount a dependent student can borrow for all undergrad years is $31,000.
Parents who want to chip in should first figure out if they can afford to do so by using the T. Rowe Price Retirement Income Calculator and then look into federal PLUS loans.
Finally, your child should apply to at least one public institution; if money is extremely tight, there's also the option of attending two years of community college (whose credits are usually transferable) and finishing at a four-year school.
Don't Buy It: "Renting is a waste of money."
Buying a home can of course be a wise investment, especially considering today's record-low mortgage rates. But that doesn't mean choosing home ownership over renting is right for everyone. In some regions of the country, the cost of owning may still be higher than that of renting (to account for total ownership expenses, including property tax and maintenance, my rule of thumb is to add about 30 percent to the base mortgage amount).
And while home values may be stabilizing in many parts of the United States, that doesn't mean they're suddenly going to start rising at a fast and furious pace.
Over the next five to seven years, you still might not see a home's value appreciate the roughly 8 to 10 percent it would need to simply to cover the costs of relocating (which at the very least include the real estate agent's typical 6 percent commission, as well as movers' fees).
A Better Idea: Do the math carefully before you consider buying. Ask yourself: Do you have any inkling that you'll want to move in the next five to seven years, whether for a job, a fresh start, or a new experience? If so, purchasing a home is not a smart choice. Keep renting until you can commit to settling down for longer, and tune out everyone who says you're throwing away money.
To Continue To Read More: https://www.oprah.com/omagazine/financial-advice-to-ignore-suze-orman-financial-advice#ixzz2BC2Qum7Q
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
One former Powerball winner has firsthand experience of landing an astronomical sum - but the windfall became the most destructive event of his life. It comes after a father who won $31million in the lottery died two years later after the "worst thing ever".
Andrew 'Jack' Whittaker came to regret the ticket that preceded devastating family tragedies, marital breakdown, repeated thefts and a troubling gambling problem.
Here, we examine the disturbing downward spiral Whittaker endured following his win.
On Christmas Eve 2002, Whittaker bought a ticket at a grocery store in his hometown of Hurricane, West Virginia, US, after pulling in to fill up his vehicle.
Though he rarely played, he hit the jackpot with what became the largest single winning ticket in US lottery history - $315m.
Yet this wasn't a rags-to-riches tale, as Whittaker, an American entrepreneur who operated a thriving construction business, was already worth a substantial $17m. Despite his prior experience managing substantial wealth, the Powerball windfall proved too much to handle, and his life quickly began to unravel.
Rather than spreading his winnings across multiple payments over time, he opted for a lump sum payout, walking away with $113m after taxes.
He was far from tight-fisted with his newfound fortune, pouring $15m into the construction of two churches while also establishing the Jack Whittaker Foundation, which provided financial assistance to individuals for expenses such as car payments and other bills.
Nevertheless, he proved to be a divisive winner. Divorce accountant Bob Rufus recalled witnessing a heated confrontation between Whittaker and his wife's divorce attorney, recounting: "Jack was ready to start throwing punches. He was very volatile."
The Powerball winner had initially vowed the prize money wouldn't change who he was, telling Fox News he was "doing God's work with all this money" and adding: "I am helping a lot of people and I plan to help a lot more."
Yet following his windfall, he soon turned up to his local strip club, Pink Pony, placing $50,000 in cash behind the bar.
The bar manager at the time told the Washington Post: "My worst nightmare was waking up in the morning and reading in the paper that Jack Whittaker got rolled [robbed] at the Pink Pony. I said, 'Please put that money away.'"
He later returned to Pink Pony and allegedly boasted about having over a million dollars in cash sitting inside his Lincoln parked outside the venue.
Reports indicate that two individuals subsequently drugged him before breaking into the vehicle to steal the money. Both faced charges but avoided jail time, and the cash was later discovered near a trash can.
Astonishingly, Whittaker failed to heed the warning, and $200,000 was stolen from the same vehicle outside the same strip club just five months later.
Whittaker became a notorious local figure following his lottery windfall, splashing out on a Lamborghini and becoming renowned for hurling cash from his car window.
After countless large sums were stolen from him, he was questioned about why he continued carrying such vast amounts of money, to which he responded: "Because I can."
Tragically, just two years after striking it rich, Whittaker lost his granddaughter, Brandi Bragg, who was only 17-years-old.
Brandi was discovered in a plastic trapline behind an abandoned van. Prior to her death, Whittaker had reportedly been giving his granddaughter $2,000 per week, in addition to purchasing four cars for her.
Divorce accountant Bob Rufus commented: "He gave a crazy stipend to his 17-year-old granddaughter and that attracted some bad characters: nothing good came of it."
• Winner of $590M lottery jackpot sued her own son and met tragic end before resolving bitter feud
• $167million Powerball winner hits rock bottom as he's arrested for 'bizarre' crime
TO CONTINUE TO READ MORE:
It comes after a Powerball winner who bagged $315M made one mistake which led to 17 years of tragedy.
Powerball winner wished he 'tore up ticket' after $315m jackpot destroyed him
No Such Thing as Enough Money
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
There are some great financial blogs that provide good answers, such as here and here. And then there are a variety of books that tackle this question in their own ways: Ego Is the Enemy, The Last Lecture, the Bible, to name a few.
Another book that resonates with me, perhaps because of its instructive format, is How Will You Measure Your Life? by the late Clayton Christensen.
He comes to the startling realization:
“I had thought the destination was what was important, but it turned out it was the journey.”
That to me is the answer to the question. Though it is, in a way, a non-answer. As with many of life’s mysteries, there is no definitive conclusion.
There is never enough money.
Don’t get me wrong. I don’t mean that you can always use more money to achieve a perfect life. Rather, I mean the exact opposite.
No amount of money will insulate you from suffering.
This week Elon Musk’s wealth jumped by $36 billion in a single day, bringing his net worth close to $300 billion. Yet, even he has experienced some very public setbacks, including the tragedy of losing his first child.
“The race is not to the swift or the battle to the strong, nor does food come to the wise or wealth to the brilliant or favor to the learned; but time and chance happen to them all.” (Eccles. 9:11)
There is no such thing as enough money, as there is no destination of absolute happiness. It’s all about simply having the capacity to notice the truly joyful things along the journey.
Pay attention to the wrong things, and life starts to feel empty. As Christensen writes:
“In your life, there are going to be constant demands for your time and attention. How are you going to decide which of those demands gets resources? The trap many people fall into is to allocate their time to whoever screams loudest, and their talent to whatever offers them the fastest reward.”
His solution is to focus on what provides lasting happiness:
“Intimate, loving, and enduring relationships with our family and close friends will be among the sources of the deepest joy in our lives.”
I am writing this because yesterday we had to say good-bye to a special member of our family. Our dog Sunny, who I referenced in this previous blog, developed a severe case of intervertebral disc disease. We woke one morning to find her acting strange, and within 48 hours she was paralyzed. With a heavy sigh, the neurologist gave us the bad news that her chances of any type of recovery were minimal. At best, she would need consistent pain management. That was no way for her to live.
I am extremely grateful for the gift of having her in my life.
In the afternoon, my wife took Sunny for her last walk. We gently set her in the kids’ red wagon. Then she pulled her around the neighborhood, taking her one last time around her favorite trees and brightly colored fire hydrants. The late October sky was unseasonably warm and clear. The white sun brightened Sunny’s golden fur.
When my wife and Sunny came back around the corner, I felt as rich as possible -- to have known Sunny, to have such a caring and loving partner, to have a tragic day made picture perfect in so many ways.
That’s enough.
There is never enough money, if you can’t see the riches in front of you now.
The question shouldn’t be: how much money is enough? It should be: how much more clarity do you need to see the rich, joyful things happening all around you?
https://rootofall.substack.com/p/no-such-thing-as-enough-money
The Relationship Between Money and Marriage
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
The most important decision you'll ever make
Warren Buffett's financial wealth is only rivaled by his wealth of wisdom. Rarely does a day pass without someone in the finance industry quoting the Oracle of Omaha on social media. Heck, Warren Buffett's influence is so great, people have essentially made careers out of quoting him.
Yet, with all of his knowledge on investing and business, he says the most important decision a person can make has nothing to do with investing and business. At the 2009 Berkshire Hathaway annual meeting, he said:
“Marry the right person. I’m serious about that. It will make more difference in your life. It will change your aspirations, all kinds of things.”
You don't make it to Buffett's level of stature with a track record of being wrong often, and researchers seem to agree with him on this point. Studies show that marrying the right person can significantly improve our health, career success and wealth.
Marriage will change you in many ways. By definition, marriage -- joining two into one -- is disruptive. Often, for the better. It is about pursuing new things while sacrificing others. A major contributor to that disruption though is money.
Although we've long moved on from the ancient practice of marrying for the sake of status, money is an irrevocable part of marriage, at times, for better, and at times, for worse. Here is what research has uncovered about the relationship between money and marriage.
The relationship between money and marriage
Married people are wealthier than single people.
A 2005 study tracking people in their 20s, 30s and 40s found that married people experienced a 77% increase in wealth over single people. In fact, married individuals in the study saw their wealth rise 16% for each year of marriage. This makes sense considering married couples can combine incomes and share expenses.
However, it may not tell the whole story. You can't expect to tie the knot and just start watching the money roll right in. More affluent people are more likelier to get married in the first place. A report by the American Enterprise Institute details the wide gap in marriage rates by income. About a quarter of “poor” adults aged 18 to 55 are currently married, compared to 56% of middle- and upper-class adults.
Wealthier couples are happier.
A study published in the Journal of Happiness Studies suggests that married individuals are generally happier than the unmarried.
What about happiness among married couples?
Turns out, money is one of the biggest contributors to marital happiness. That's what University of Maryland sociology professor Philip Cohen found after analyzing data from the General Social Survey, a long-running study of Americans’ views and behaviors.
The survey shows a class divide when it comes to marital happiness. Of upper-class married couples, 70% said they are "very happy" while only 53% of lower-income couples could say the same.
TO READ MORE: https://rootofall.substack.com/p/the-relationship-between-money-and-marriage
Europe Just Bragged About Losing to Gold
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
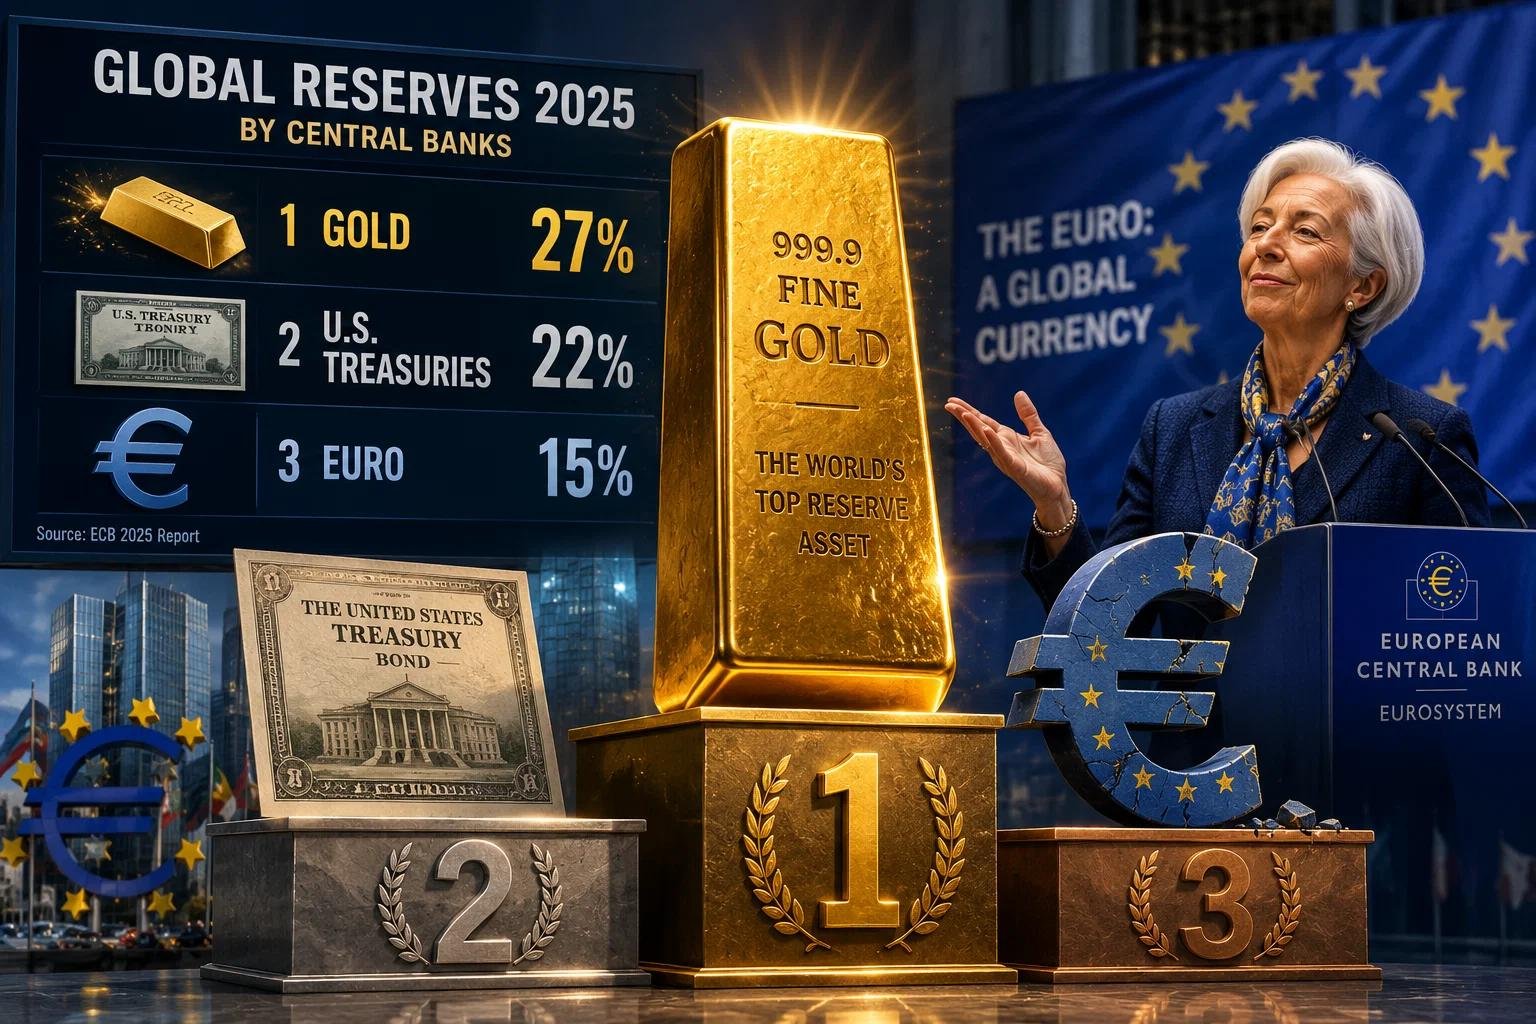
Last week, the European Central Bank published its 2025 report card, with ECB President Christine Lagarde celebrating “an opening for the euro to enhance its global appeal.”
The report bragged that the euro remains the second most used currency in the world, as well as the second most held in reserve, behind only the dollar.
The key word is “currency.”
Because in reality, 2025 was the year that gold took the top spot, making up 27% of global reserves held by governments and central banks. That pushed US Treasuries into second place with 22%, and the euro into third, making up 15% of global reserves.
A metal that pays no interest and earns no yield is now the biggest slice of global reserves, up from just 20% a year earlier.
The world is, in fact, trying to diversify away from the dollar. Central banks have spent years quietly trimming their dollar exposure, looking for somewhere safer to park their national savings.
But they are not choosing euros.
Then why, the ECB may counter, was 2025 a record year for international borrowing in euros?
Because there is more debt in everything than ever — global debt keeps smashing new highs, so a record pile of euro IOUs is less an achievement than a symptom of the times.
But to give credit where it's due, the euro is genuinely in first place in one market, according to Lagarde: "The euro became the leading currency in the green and sustainable international bond market."
That's the debt Europe sells to bankroll the very net-zero crusade that gutted its own economy. So the euro's crowning achievement of 2025 was becoming the world champion at borrowing money to make itself poorer.
If you ever needed one sentence to explain why nobody wants this currency, there it is.
Because leading the world in the things that make you poorer is the entire European model. Across the continent, governments spent two decades waging war on their own cheap energy in the name of net zero — turning their backs on nuclear power that supplied a third of Europe's electricity in 1990 and barely 15% today.
They saddled themselves with some of the highest power prices in the developed world and watched their industry pack up and leave. They threw open their borders, then aimed their police and courts at the citizens who objected.
The result is a continent so hollowed out that Mississippi, the poorest state in America, now produces more wealth per person than France or Italy.
But sure, this is the euro’s moment...
Meanwhile, central banks added roughly 850 tonnes of physical gold in 2025, a slight step down from the record-shattering pace of the prior two years, but bought at the highest prices in human history.
Poland led the gold-buying pack last year, followed by China, Turkey, and India.
But for a stretch of 2025, the single biggest gold buyer on the planet wasn't a country at all — it was Tether, the company behind the world's biggest dollar-backed stablecoin.
In the third quarter alone it bought more gold than any central bank on earth, and by the end of January it was sitting on roughly 148 tonnes — nearly 4.8 million ounces, worth about $22 billion — enough to rank among the top 30 gold holders in the world, ahead of the likes of Australia and South Korea.
This is exactly why the gold story is far from over.
The extra gold central banks have bought since 2022 laid the foundation for a price that has nearly tripled since — yet even that represents only a modest reallocation out of US dollars.
So what happens when they move even another 5% of their $10 trillion in reserves into gold?
With no single currency able to replace the dollar, and the reasons to diversify only growing, gold looks set to keep climbing as the world's largest reserve asset.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S. Everyone from central banks to a stablecoin giant is racing into gold — which is why it's trading near record highs. We think owning the companies that produce it beats buying bullion at the top.
That's the whole idea behind Strategic Assets, Schiff Sovereign's monthly investment research. We hunt for profitable real-asset businesses with clean balance sheets, real catalysts, and a low multiple of free cash flow.
And it's working. We've seen it multiply the value of several precious metals companies, with others still in the buy range today. The same setup is now lining up well beyond the metals — in energy and other real assets — as nations around the world scramble to secure the critical resources a fragmenting world runs on.
This Is A Key Sign You Have An Unhealthy Relationship With Money
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
“Whenever things are in order, it brings us a sense of peace,” Severine Bryan, DBA, financial empowerment educator and coach, and founder of Sev Talks Money, tells TZR in an email.
“Having our finances in order doesn't necessarily mean we are debt-free, but it allows us to have a clear picture of where we are at. It is very important to know what is coming in and what is going out so we are not flying blind.”
She says she likes to think of organizing finances like taking a trip to New York City. “I can leave Georgia and end up in California if I don't know the details of the trip and if I don’t put specific plans in place,” she explains. “When I have a plan, I will go directly to NYC. And even if I take a detour, I will know how to get back on track to get there.” Ahead, Bryan and two other financial coaches explain how they help clients get back on track — and why it’s never too late to do so.
What A Financial Coach Does
Whether you consult a financial psychologist, money mindset coach, or similar type of financial expert, they all do variations of the same thing — help you figure out your relationship to money and how your past (upbringing) affects your present spending and saving habits.
“Part of what we're doing in financial therapy is to be able to really look with clarity at our circumstances — and how those circumstances change from moment to moment,” Financial Therapist Amanda Clayman tells TZR. She aims to help clients learn how to use certain strategies to get a money routine or practice in place.
Bryan adds that a financial coach can also help clients set financial goals, create a plan to achieve those goals, and provide accountability to help them follow the plan. “We also help the client dig deep to find what motivates them to achieve certain goals,” she explains.
“Because, many times, the goal is not money, but the things that money provides, such as freedom to make choices.” This can mean anything from wanting to eat out to buying a particular car or taking a certain vacation. “I think of a financial coach similarly to a football coach,” she adds. “The football coach gives the plays during training, but on game day, the quarterback is the one that has to make the calls.”
Finances can be a very difficult topic to discuss, Taryn Bushrod, money mindset coach and founder of Taryn’s World, tells TZR in an email. “Doing so exposes people’s vulnerabilities, and that can be extremely uncomfortable,” she says. “The first thing I do with a new client is build a relationship, so they are comfortable enough to start sharing pertinent information I need in order to help them start seeing results.” She then focuses on behavioral factors that impact spending.
“In doing so, you can identify the root cause of your actions and redirect your spending habits, which, in turn, could result in redirecting your funds.”
TO READ MORE: https://www.thezoereport.com/wellness/relationship-with-money?fbclid=IwAR3SsiSiZ3gONSAjnuc_z8XSUXZE38MbQa4LOpH8FAdojaC1Y4I4oj3neZY