Not All Income Is Created Equal
Not All Income Is Created Equal
One of the most common financial pitfalls people make is thinking that all income is created equal. It’s an easy mistake to make; after all, a dollar is a dollar . . . right?
Well, that’s what I thought. What completely re-shaped how I spend my time and energy, though, is learning that one dollar can actually be worth less than another, simply based on how it's produced.
It’s a tricky concept to explain, so let’s jump right into some examples.
Is Your Income Being Devalued?
One of the best ways to illustrate this is to look at the 2020 tax bracket.
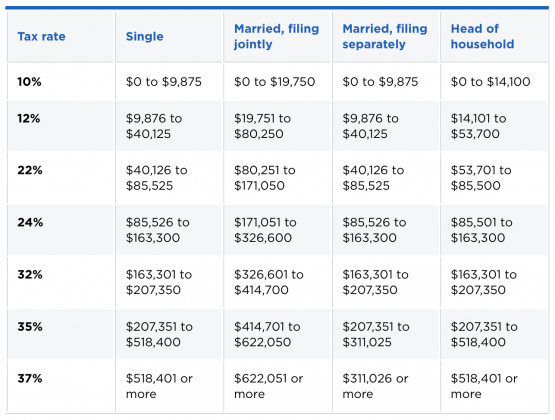
Credit: Nerdwallet
At its most basic level, this graphic shows that every dollar earned above $518,401 (when single) is taxed 2% higher than the prior bracket.
In other words, if you earn more than $518,401 per year, every additional dollar is worth 2% less than in the lower bracket.
Make sense?
This not only devalues your money, it devalues your time. After all, if you’re getting paid a certain wage per hour, your time is now worth 2% less at the highest bracket.
The point of all of this is to say that you need to figure out where the dollars are worth the most, and how to use the minimum amount of time and effort to create those dollars. That’s how you leverage your time for maximal benefit.
To put it another way, would you rather spend an hour to earn $250, taxed at 35%, or spend that same hour earning the same $250, but taxed at 10%?
The tax amount makes a huge difference–especially when we’re talking about numbers much greater than $250 (as we all know, it’s not what you earn that matters. It’s what you keep).
Income and the Cash Flow Quadrants
In order to put this all into perspective, let’s take a moment to revisit the CashFlow Quadrant, concept presented by Robert Kiyosaki in his book of the same name.
To continue reading, please go to the original article here:
https://passiveincomemd.com/not-all-income-is-created-equal/
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
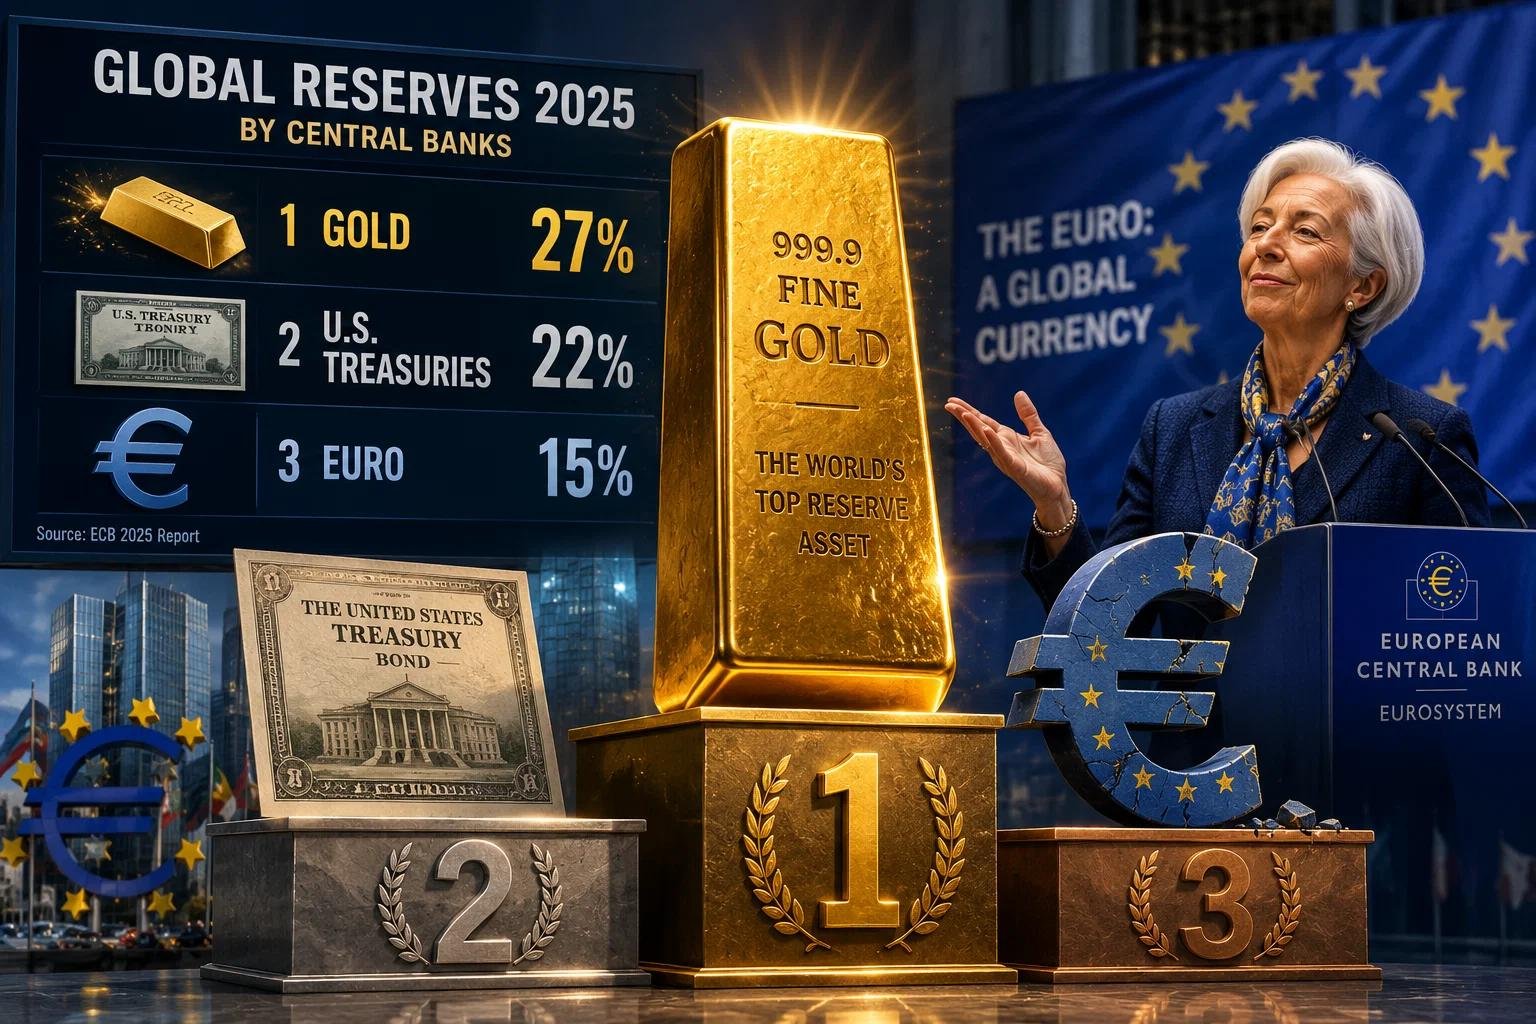
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
Green Policy is Deadlier Than Guns
Notes From the Field By James Hickman (Simon Black / Sovereign Man May 29, 2026
Every year around this time, a silent killer sneaks its way onto European shores and slaughters people by the tens of thousands. Last year, it killed more people in just three months than the number of civilians killed in the war in Ukraine all year. It killed three times as many people as traffic accidents do. And it killed FOUR times more Europeans than gun violence killed in America. I'm not talking about COVID. Or even the legions of migrants invading the continent.
4 Bad Habits That Could Affect Your Money More Than Tariffs and Inflation
Written by Chris Adam GoBankingRates
The Trump administration’s discussions about tariffs and inflation have led many consumers to question how well they’re prepared for the future regarding their finances. After all, some experts have raised concerns that tariffs could lead to higher prices on products and services people use each day.
But there may be a way to protect personal finances that has little to do with moves by the White House.
Expert Issues Warning Over US Bank Accounts Sitting Idle
Rudro Chakrabarti Mon, April 20, 2026
Money Can Now Be Turned Over To State. Secure your money ASAP
Katelyn Fugate thought she was doing something nice for her young son. A few years back, she opened a savings account for him — a small starter fund he could build on one day. Recently, she decided to check in on it.
The balance was zero. Fugate told Scripps News she went to check the balance hoping to start adding to it again. Instead, she found the account empty. (1) The bank had declared it dormant after five years of inactivity, closed it and shipped the money off to the state's unclaimed funds department. Worse, when Fugate went looking for it, she couldn't find the money at the bank or the state.
Argentina Got This Warning Before Its Collapse. America Just Got It Last Week.
Notes From the Field By James Hickman (Simon Black / Sovereign Man) April 20, 2026
In early December 2001, ‘normal’ life very suddenly ceased to exist in Argentina— anything that remotely resembled a functional society came to an abrupt end. And that is by no means an exaggeration. The banking system collapsed. Financial transactions ground to a halt. Desperate people looted supermarkets for food, and then grocery shelves emptied. Energy ran short. Riots broke out in the streets, and police were shooting citizens in the face.
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2