How To Handle A Windfall
How To Handle A Windfall
By J.D. Roth| Updated: 11 September 2019
When my father died in 1995, he left behind a small life insurance policy that awarded each family member $5,000. It wasn't much, but it was the best he could do based on the fact that he had cancer. He hadn't been much of a planner, and hadn't been good with money, so that $5,000 per person was actually a significant amount.
At the time, I was deep in debt. I had over $20,000 in credit card balances, and was gradually adding more all of the time. If I'd been smart, I would have taken the proceeds from my father's life insurance and used them to immediately repay $5,000 in debt. But I wasn't smart. I used $1,000 to pay off debt (and patted myself on the back for it), but spent the rest on a new computer, software, and accessories. It didn't take long to realize that this was a dumb decision.
You see, when you receive a windfall, whether it's a tax refund, an inheritance, a gift, or from any other source, it's like you've been given a second chance. Although you may have made money mistakes in the past, you now have a chance to fix those mistakes (or some of them, anyhow) and start down the path of smart money management.
It can be tempting (as I well know) to spend your windfall on toys, trips, and other things that you “deserve,” but doing so will leave you in the same place you were before you received the windfall. And if that place was chained to debt, you'll be just as unhappy as you've always been.
Since my father died, I've received a few other small windfalls (and a very large windfall when I sold Get Rich Slowly). With time, I've developed a system for handling these situations.
If you receive a chunk of cash, I recommend that you:
Keep 5 percent to treat yourself and your family. Let's be realistic. If you receive $1,000 or $10,000 or $100,000 unexpectedly, you're going to want to spend some of it.
No problem. But don't spend all of it. I used to recommend spending 1 percent of a windfall on yourself, but from talking to people, that's not enough. Now I suggest spending 5 percent on fun. That means $50 of a $1,000 windfall, $500 of a $10,000 windfall, or $5,000 of a $100,000 windfall. Don't be tempted to spend more!
To continue reading, please go to the original article here:
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
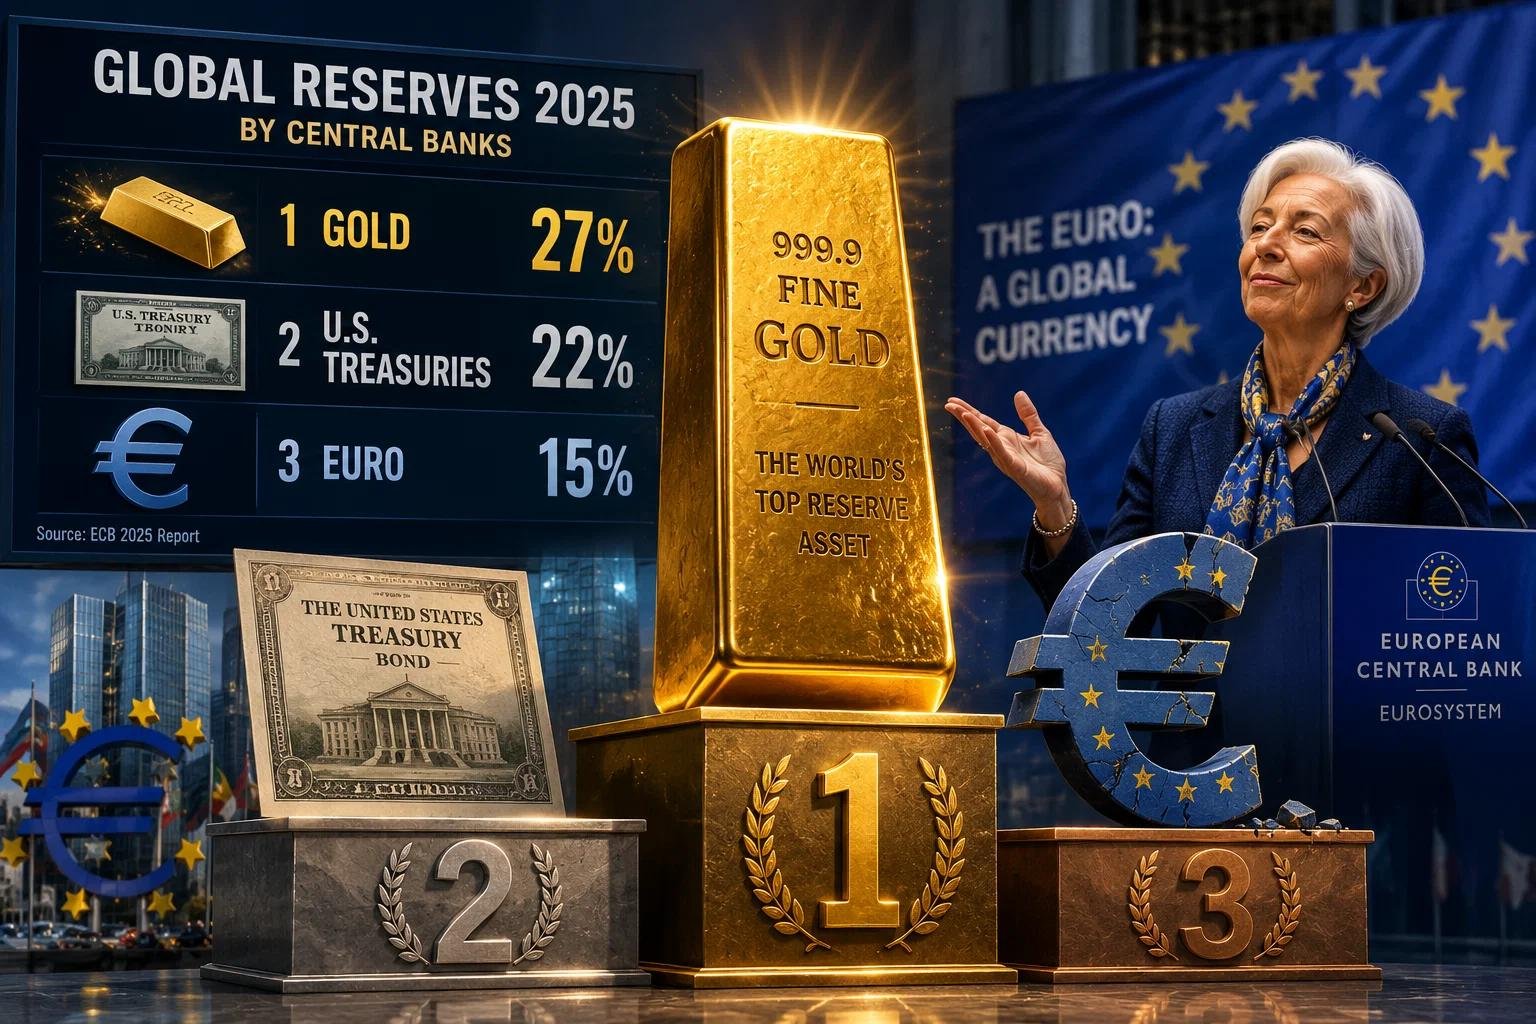
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
Green Policy is Deadlier Than Guns
Notes From the Field By James Hickman (Simon Black / Sovereign Man May 29, 2026
Every year around this time, a silent killer sneaks its way onto European shores and slaughters people by the tens of thousands. Last year, it killed more people in just three months than the number of civilians killed in the war in Ukraine all year. It killed three times as many people as traffic accidents do. And it killed FOUR times more Europeans than gun violence killed in America. I'm not talking about COVID. Or even the legions of migrants invading the continent.
4 Bad Habits That Could Affect Your Money More Than Tariffs and Inflation
Written by Chris Adam GoBankingRates
The Trump administration’s discussions about tariffs and inflation have led many consumers to question how well they’re prepared for the future regarding their finances. After all, some experts have raised concerns that tariffs could lead to higher prices on products and services people use each day.
But there may be a way to protect personal finances that has little to do with moves by the White House.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.