Avoiding the fate of the dodo: How To Prepare For An Uncertain Future
By J.D. Roth
Our financial decisions are based on our expectations for the future.
We save for retirement because we expect we’ll live a long time in old age, a period where we expect to be relatively unproductive. We invest in stocks because we expect the market to provide outsized returns when compared to other asset classes. We set aside emergency savings because we expect that bad things will happen — if not tomorrow, then next week (or next year).
We base our expectations on past experience — both our own experience and the experiences of others.
We expect to live a long time in old age because statistically most of our contemporaries live a long time in old age. We expect the stock market to provide excellent returns because for the past 100 years, that’s what the stock market has done.We expect bad things to happen because bad things always happen.
Generally speaking, there’s nothing wrong with this method of planning. It works.
When we base our expectations for the future based on what’s happened in the past, we tend to get good results. We accumulate money for when we’re no longer able (or willing) to work. Our investments grow. We have a cash cushion for when the car breaks down or little Jimmy breaks his leg.
Beyond All Expectations
But what happens when the old patterns break? What happens when past data becomes meaningless? That’s the subject of an intersting article from Nick Maggiulli at Of Dollars and Data.
He tells the story of how the dodo went extinct. Evolving in an ecosystem without predators, these birds had no fear of humans. They had no expectation that another creature might hunt them down and eat them and end the species.
The Dodo
Maggiulli writes:
From the perspective of the dodo, the arrival of humans (or any other large predator) was outside the realm of its evolutionary grasp. Anything the dodo had approached previously had not tried to eat it. However, the arrival of humans broke the old pattern. It was beyond all expectations.
This idea is directly relevant to how investors use historical financial data to make decisions about the future. We assume that history is a great guide for what is to come, which is only sometimes true. We rely heavily on previous patterns…until they break. This is the classic black swan problem explained by Nassim Taleb, and highlights the difficulty with relying on financial history to make predictions.
“Just like the dodo,” Maggiuilli says, “investors are on their own island of financial history with no clue what will wash ashore from the seas of tomorrow.”
To continue reading, please go to the original article here:
7 Surprising Benefits of Failure
By Kentin Waits WISEBREAD
Everyone loves a success story, and the world is filled with them. But what about stories of failure? Can't they be as just as educational? Just as inspirational? Equally insightful?
After all, a single big win is often built on several losses. It's a truth perfectly captured in the words of Japanese industrialist and automaker, Soichiro Honda, "Success is 99% failure."
Brazil’s Massive Crash Is A Sign Of Things To Come In The West
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 29, 2026
On Sunday night, Brazil re-elected its left-wing president, Lula da Silva. On Monday morning the São Paulo stock market fell so hard at the open that the exchange halted trading for the first time since the pandemic. When trading resumed, Brazil’s stock market kept falling.
6 Attitudes That Breed Financial Failure
By Kentin Waits WiseBread
Financial success or failure is often the result of attitudes — both conscious and unconscious — that affect our behavior. No amount of budgeting and self-control can help us when we’re up against ingrained ideas about money management, spending, and debt. If you’re having a tough time shifting your financial behavior, maybe it’s time to change your mind about money. Here are six common attitudes that work against us financially.
Plan B Options for folks on Social Security
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 27, 2026
In the early morning hours of February 7, 1937, a young American named Stirling Dickinson got off a train in central Mexico and rode into San Miguel de Allende on a mule-drawn cart.
He and a Princeton classmate were months into a trip around Mexico looking for a quiet place to write, and a Mexican opera singer had told them to try San Miguel.
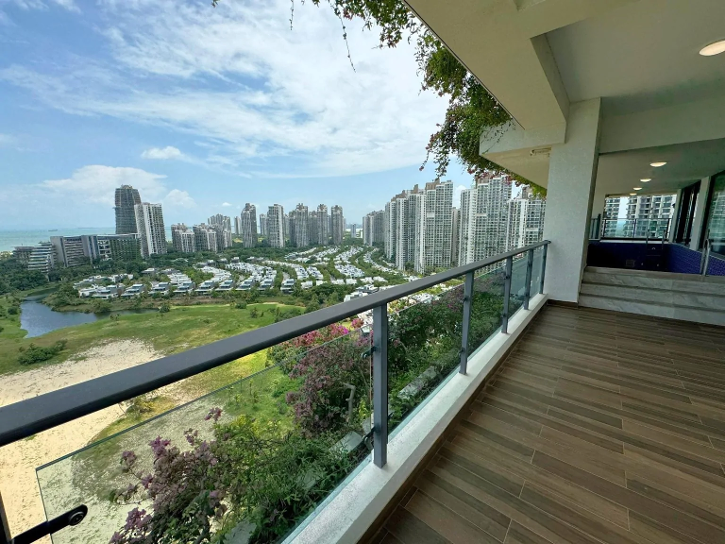
A Condo in this Ghost City Gets You Ten Years Residency
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 22, 2026
On March 6, 2016, Malaysia’s prime minister, Najib Razak, turned up for the grand opening of a city that did not exist yet, two kilometers off the coast from Singapore.
It was called Forest City, and the plan was enormous. One of the largest property developers in the world came in to build four artificial islands in the strait and put a “smart, green” city of 700,000 people on them, at a cost of roughly $100 billion.
Avoid These 4 Common Mistakes When You Get Rich Overnight
September 4, 2025 by Laura Bogart GoBankingRates
You’re about to score a financial touchdown. Maybe you’ve crushed it at work and landed a sweet promotion. Perhaps you’ve won a lottery or stumbled into a side hustle that suddenly pays off. As you near the end zone, heart pounding, head full of dreams, you can’t afford (literally) to fumble. Whether you’re blindsided by unexpected taxes or tripped up by bad financial advice, you have a lot to lose if you drop the ball.
6 Common Excuses for Not Saving Money By Tara Struyk
Have you ever settled on a new exercise program, only to get a bad cold a few days in and happily throw yourself on the couch, relieved to have a handy excuse? Excuses must be human nature; I know I usually make them when I'm facing something that’s new, that's hard, or that I just don’t enjoy. And I’ve certainly made excuses when it comes to money.
In the years that I’ve been writing about personal finance and investing, I’ve also heard my fair share of excuses, mostly from readers who don’t agree with my advice. The problem is, unlike good financial habits, excuses are easy to come by, even though most of them just don’t stand up to reason. Check out some of the ones I’ve heard most frequently so far.
How To Make Strategic Cash Bucketing Work For You
Last Edited Sep 16, 2026| Angelena Mascilli
Cash bucketing – or categorizing your funds based on specific expenses or goals – can help you organize your financial life.
Cash and other liquid assets may be the ideal place for buckets of money that you may need to access soon to cover expenses or capitalize on new investment opportunities.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
Tomorrow’s Election Changes Nothing About The National Debt
Notes From the Field By james Hickman (Simon Black/Sovereign Man) November 2, 2026
Johnny Moon was homeless and unemployed in the early 2000s. A high school dropout with a bad drug habit, Moon was hardly someone that banks would consider creditworthy.
And yet, over the course of a single year, he was able to borrow more than $600,000 to buy five different investment properties.