Thank you to all the subscribers to our Early Access program…we thank you for your continued support.
We are excited to offer this new service to keep you informed and up-to-date on the latest Dinar and currency news.
3 Savings Moves To Make Post-Fed Rate Hike
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
Taking advantage of new, better interest-earning opportunities will take a bit of a strategic approach from savers, however. While there are always costly mistakes worth avoiding, making the right, proactive moves now could be the difference between earning a standard rate on your money or one that's exponentially higher. And these moves should happen relatively quickly, both to boost your savings as much as possible and to cut losses you may already be enduring with other account types. Below, we'll break down three specific savings moves to make now, post-Fed rate hike.
To position yourself for savings success as quickly as possible, consider making these three moves right now:
Move the money you need to maintain access to into a high-yield savings account
Traditional savings accounts should have been closed already, but if you haven't yet done so, consider acting now. With an average interest rate of just 0.38% currently, you're essentially losing money by not shifting your funds into an alternative account type. Move the money you need to maintain access to, then, into a high-yield savings account instead. These accounts operate the same way a traditional account does, albeit with significantly more interest earnings to be had.
And you won't have to worry about making withdrawals, deposits or paying any fees the way you would with a certificate of deposit (CD) account with a fixed rate. With a variable rate structure, too, they're well-positioned to take advantage of a rising interest rate environment if the Fed continues to hike rates. Consider shopping around for high-yield savings accounts online, then, and move the money you need to keep flexible into the most profitable option you can find right away.
Use CDs, but in a more cautious way than usual
Technically, CDs have slightly higher rates than high-yield savings accounts do. And they're fixed, adding a layer of protection that the variable-rate high-yield account can't offer. Because your money will be locked in the account at that fixed rate level, however, your interest-earning potential will be limited.
This doesn't mean that CD accounts aren't still worth opening (they are), but it does mean that savers should use them in a more cautious way than usual, especially compared to the climate in which interest rates were consistently declining in 2024 and 2025. So open a CD account, but don't deposit more than you can afford to part with, and don't lock it into a term that you can't easily see through to the maturity date.
Explore alternative accounts that can help you take advantage of a higher rate climate
CDs and high-yield savings accounts may be ubiquitous, but they're not the only accounts that will help you take advantage of a higher interest rate climate. A money market account functions as a savings account that you can write checks from and, right now, interest rates on the account are averaging only slightly below those tied to high-yield savings accounts.
So, if you want to earn a high rate while streamlining your banking needs, this could be the right account for you now. High-yield checking accounts, meanwhile, should also be considered as they can allow you to earn a competitive rate on the money you already have sitting idle waiting for the next bill to be paid. Earning some extra interest there, too, won't hurt.
The bottom line
A rising interest rate environment isn't great news for borrowers, but it does have a silver lining for savers who position themselves appropriately now. By moving the money you need access to into a high-yield savings account, closing the traditional account (if you still have one), using CDs in a more cautious way, and exploring alternative account types that you may not have thought about previously, you can do just that. Consider the use, too, of online marketplaces that list all of the relevant account information you'll need in one spot and don't discount the benefits of speaking with banks directly as they can often outline accounts and approaches that may align with your unique financial circumstances.
Edited by Angelica Leicht
TO READ MORE: https://www.cbsnews.com/news/savings-moves-to-make-post-september-2026-fed-rate-hike/
Andy Schectman: Central Banks Are Preparing for What Comes Next
Andy Schectman: Central Banks Are Preparing for What Comes Next
Liberty and Finance: 9-22-2026
Andy Schectman warns that rising interest rates may no longer be hurting gold the way conventional market wisdom suggests, as central banks continue accumulating physical metal and Comex deliveries remain strong.
He says the growing pressure on U.S. Treasuries, rising diesel and oil costs, and limited options for central banks could create a dangerous environment of inflation and financial volatility.
Andy Schectman: Central Banks Are Preparing for What Comes Next
Liberty and Finance: 9-22-2026
Andy Schectman warns that rising interest rates may no longer be hurting gold the way conventional market wisdom suggests, as central banks continue accumulating physical metal and Comex deliveries remain strong.
He says the growing pressure on U.S. Treasuries, rising diesel and oil costs, and limited options for central banks could create a dangerous environment of inflation and financial volatility.
Schectman also argues that BRICS nations are quietly building interoperable payment and monetary infrastructure while increasing gold accumulation and reducing reliance on Treasuries.
He warns that the bond market could face severe consequences if Treasury yields move substantially above 5%, with ripple effects across Wall Street, real estate, banks, insurers and pensions.
Meanwhile, he says physical gold and silver remain attractive relative to other assets, with premiums beginning to rise again as global demand continues.
INTERVIEW TIMELINE:
0:00 Intro
1:30 Rate increases
11:00 BRICS & gold
19:00 Bond market crisis
24:00 Bullion supply chain
Ariel: The Great Revaluation, the Trifecta that Ends Bretton Woods Forever
Ariel: The Great Revaluation, the Trifecta that Ends Bretton Woods Forever
9-23-2026
The Great Revaluation — $600 Silver, $10K Gold, and the Iraq-XRP-XLM Trifecta That Ends Bretton Woods Forever
The $600/$10K Anchor Is Not a Guess — It’s a Solvency
That “$600 silver / $10,000 gold” figure didn’t come from some Telegram hype channel. It came from the balance-sheet math that Treasury can’t say out loud yet. Here’s what nobody on the internet are talking about.
Ariel: The Great Revaluation, the Trifecta that Ends Bretton Woods Forever
9-23-2026
The Great Revaluation — $600 Silver, $10K Gold, and the Iraq-XRP-XLM Trifecta That Ends Bretton Woods Forever
The $600/$10K Anchor Is Not a Guess — It’s a Solvency
That “$600 silver / $10,000 gold” figure didn’t come from some Telegram hype channel. It came from the balance-sheet math that Treasury can’t say out loud yet. Here’s what nobody on the internet are talking about.
The U.S. holds 261.5 million troy ounces of gold on the books at $42.22 per ounce a laughable $11 billion valuation that hasn’t been updated since Nixon torched Bretton Woods I in 1971.
At $10,000 per ounce, that same vault becomes $2.615 trillion in hard collateral overnight, and silver at $600 turns the strategic stockpile into an additional $300+ billion without a single new mining permit.
That’s not a “revaluation.” That’s an emergency solvency injection that re-underwrites the Treasury dollar without printing a single new Federal Reserve note, and it happens the moment the bridge currency framework XRP and XLM is operational enough to absorb the shock without collapsing the legacy bond market.
The SEC’s September 17 Innovation Exemption was the legal signal flare. Ondo and DTCC going live in October is the plumbing. And that $600/$10K number is the pressure reading in the pipe before the valve opens.
The IMF Leaving Bretton Woods Is Not Reform — It’s a Surrender Document Signed in Blockchain Ink
The IMF “announcing they are leaving Bretton Woods for the new digital age” is the most polite way to describe an institutional capitulation that’s been 80 years in the making. Bretton Woods wasn’t just a monetary system. It was a control architecture IMF conditionality, World Bank structural adjustment, dollar hegemony enforced through SWIFT exclusion and Treasury sanctions that let a handful of Western institutions dictate the economic sovereignty of 190 countries.
The IMF walking away from that framework in September 2026, the same month the SEC issued its Innovation Exemption and Iraq declared financial sovereignty, is not a coincidence. It’s a sequenced retreat.
Here’s what they didn’t announce in the press release. The IMF’s new “digital age” framework means member states can now settle cross-border obligations using tokenized assets on public blockchain infrastructure specifically, the XRP Ledger and Stellar Network without routing through the correspondent banking system that the IMF itself used to enforce compliance.
Iraq’s 2027 budget, priced in a revalued dinar, settles against tokenized oil contracts on the same rails. The IMF isn’t “leaving” Bretton Woods. They’re evacuating before the legacy architecture collapses under the weight of a gold-backed, blockchain-settled parallel system they can no longer gatekeep.
The Iraq Revaluation Is Not a Standalone Event — It’s the Trigger for the Commodity-Backed Currency Cascade
Iraq’s IQD revaluation driven by the September 30 sovereignty declaration and the October 15 budget rate announcement is not just about Iraq. Iraq sits on the fifth-largest proven oil reserves on Earth, 145 billion barrels, plus natural gas reserves that are still underexplored because the Deepstate’s “program rate” kept the economy too dysfunctional to develop them.
When the dinar revalues to something approaching its resource-backed reality and when the dIQD is instantly convertible through XRP/XLM to tokenized gold, silver, and U.S. Treasuries Iraq becomes the proof of concept for every other resource-rich nation that’s been trapped in IMF-imposed currency suppression.
Venezuela’s bolivar, Nigeria’s naira, Indonesia’s rupiah every petro-state that’s been told for decades that their currency is “worthless” despite sitting on trillion-dollar resource bases gets a template.
The $600 silver and $10K gold revaluation isn’t just for the U.S. Treasury. It’s the anchor that gives every commodity-backed revaluation a reference price.
Iraq goes first because the CBI’s digital framework is the most advanced, but the cascade is already priced into the Ondo-DTCC tokenization timeline. October isn’t just a month. It’s a detonation sequence.
Read Full Article:
https://www.patreon.com/Prolotario1/posts/great-added-to-x-170301049
Seeds of Wisdom RV and Economics Updates Wednesday Afternoon 9-23-26
Good Afternoon Dinar Recaps,
U.S. PAYMENT RESET WATCH: FED PROPOSES CONNECTING FEDNOW TO CROSS-BORDER PAYMENTS
The Federal Reserve is proposing a regulatory change that could allow U.S. banks to use FedNow for the domestic portion of cross-border transactions while intermediaries handle the international leg.
Good Afternoon Dinar Recaps,
U.S. PAYMENT RESET WATCH: FED PROPOSES CONNECTING FEDNOW TO CROSS-BORDER PAYMENTS
The Federal Reserve is proposing a regulatory change that could allow U.S. banks to use FedNow for the domestic portion of cross-border transactions while intermediaries handle the international leg.
OVERVIEW
The Federal Reserve has proposed allowing participating FedNow institutions to use intermediaries, including correspondent banks, when sending funds through the FedNow Service.
The proposal could allow a payment to move through FedNow for its U.S. portion while a correspondent bank handles the international portion, creating a bridge between America's instant-payment infrastructure and existing global banking networks.
This is not yet a live international FedNow service or announcement of a new global payment system. It is a proposed regulatory change that could open the door to additional private-sector cross-border payment solutions.
KEY DEVELOPMENTS
1. The Fed is proposing greater flexibility for FedNow
The Federal Reserve's proposal would amend Regulation J, which governs funds transfers through FedNow, to allow participants to use intermediaries other than Federal Reserve Banks when sending funds through the service.
That change matters because FedNow was designed primarily around the domestic U.S. payment system. Allowing intermediaries could give banks more flexibility to connect a FedNow transaction with payment infrastructure outside the United States.
2. Correspondent banks could provide the international link
The Fed specifically identified a correspondent bank as an example of an intermediary that could handle the international portion of a cross-border transaction.
Under the proposed structure, the U.S. portion could use FedNow while the international portion could move through an established correspondent-banking relationship.
This is important because it does not require the Federal Reserve to create an entirely separate global payment network. Instead, it could allow FedNow to connect with existing international payment infrastructure.
3. The proposal could expand private-sector cross-border payment solutions
The Federal Reserve said the additional flexibility could support new private-sector use cases for FedNow.
That could include financial institutions developing faster cross-border payment products that combine America's real-time payment rail with international banking networks.
Payments industry coverage described the proposal as potentially allowing U.S. financial institutions to use intermediaries, including non-U.S. correspondent banks, to complete international transactions while using FedNow domestically.
4. This is an infrastructure change—not a currency reset
The significance of this development is in the payment rails, not in an announced change to the dollar's value.
Nothing in the Federal Reserve proposal announces a dollar revaluation, replacement of the dollar, or a predetermined global financial reset.
Instead, it addresses how money could move between domestic and international financial systems.
5. FedNow becomes part of a larger real-time payments transformation
FedNow launched in 2023 as the Federal Reserve's instant-payment service, allowing participating financial institutions to send and receive payments around the clock.
The proposed intermediary framework would represent another step in the evolution of that infrastructure: moving from a primarily domestic real-time rail toward a structure that could connect with international payment channels.
6. The proposal is why this is a “WATCH”
The Federal Reserve's proposal was published in April 2026 and the formal comment period closed June 9. The proposal itself does not mean that international FedNow transactions are already operating.
That distinction is important.
RESET WATCH means the infrastructure is developing—not that a completed reset has occurred.
WHY IT MATTERS
The global financial system is increasingly being reshaped by changes in payment speed, settlement infrastructure, interoperability and digital connectivity.
The important question is no longer simply how quickly a bank can send a payment domestically. Increasingly, financial institutions are working to connect real-time domestic payment systems with international transactions.
The FedNow proposal is one example of that broader transition.
WHY IT MATTERS TO FOREIGN CURRENCY HOLDERS
For people who hold foreign currencies in anticipation of future changes in the global financial system, this development should be viewed as infrastructure evidence rather than a prediction about currency values.
A faster or more interconnected payment system does not automatically mean that any particular currency will be revalued.
What it does show is that major financial institutions and central banks continue to work on the plumbing through which currencies and financial assets move.
That is consistent with the principle of foundation before revaluation.
IMPLICATIONS FOR THE GLOBAL RESET
Pillar 1 — Payments
FedNow is a U.S. real-time payment rail. Allowing intermediaries could make it easier to connect that domestic infrastructure with international payment activity.
Pillar 2 — Banking
Correspondent banks remain an important part of international finance. The proposal could allow those institutions to serve as a bridge between domestic instant payments and international transactions.
Pillar 3 — Technology
Real-time payment infrastructure is becoming increasingly important as banks and payment companies seek faster settlement and more efficient financial connectivity.
Pillar 4 — Global Financial Infrastructure
The broader trend is toward interconnected payment systems rather than isolated national rails. FedNow's proposed flexibility is one piece of that larger evolution.
THE GLOBAL RESET CONNECTION
FedNow → U.S. Banking → Correspondent Banks → Cross-Border Payments → Faster Settlement → Payment Interoperability → Global Financial Infrastructure
RUMOR SAFETY REMINDER
This development is not an announcement of a global financial reset, dollar revaluation, currency exchange-rate change, or specific reset date.
The Federal Reserve's action is a regulatory proposal concerning how FedNow participants could use intermediaries for the international portion of cross-border transactions.
The significance is the potential evolution of payment infrastructure—not a guaranteed change in currency values.
Hope, not hype. Follow the evidence.
THE BOTTOM LINE
The most important financial changes are not always announcements about currencies—they can begin with the infrastructure that determines how money moves. As FedNow potentially connects U.S. real-time payments with international banking channels, another piece of the global financial system is being redesigned from the ground up.
Seeds of Wisdom Team
Newshounds News™ Exclusive
SOURCES
~~~~~~~~~~
Seeds of Wisdom Team RV Currency Facts Youtube and Rumble
Newshound's News Telegram Room Link
RV Facts with Proof Links Link
RV Updates Proof links - Facts Link
Start Here room with Most Asked Questions Link
Follow the Gold/Silver Rate COMEX
Follow Fast Facts
Seeds of Wisdom Team™ Website
Thank you Dinar Recaps
Stephanie Starr: The Gold and Silver Reset, Follow the Math
Stephanie Starr: The Gold and Silver Reset, Follow the Math
9-23-2026
Hear me out you guys….
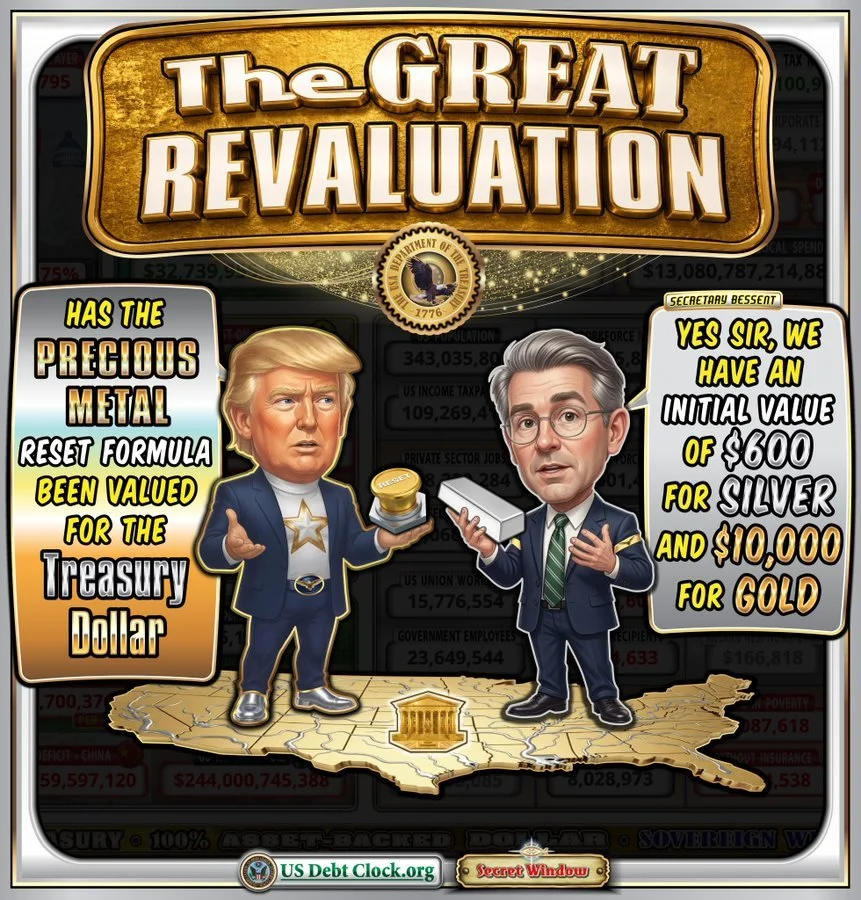
THE $10,000 GOLD / $600 SILVER “RESET” — FOLLOW THE MATH
That new U.S. Debt Clock graphic caught my attention, so I started working backward from the numbers. And this gets interesting FAST.
Stephanie Starr: The Gold and Silver Reset, Follow the Math
9-23-2026
Hear me out you guys….
THE $10,000 GOLD / $600 SILVER “RESET” — FOLLOW THE MATH
That new U.S. Debt Clock graphic caught my attention, so I started working backward from the numbers. And this gets interesting FAST.
The U.S. Treasury holds approximately 261.5 MILLION fine troy ounces of gold. Yet that gold is still officially carried on the government’s books at just $42.22oz.
Now revalue it to the $10,000/oz shown in the graphic:
261.5M oz × $10,000 = $2.615 TRILLION
Here’s the interesting part…
U.S. currency in circulation as of July 2026 was approximately $2.472 TRILLION. Meaning $10,000 gold would value America’s gold reserves at roughly 106% of all physical U.S. currency in circulation. Coincidence? Maybe.
But then look at SILVER.
The graphic shows $600 silver.
$10,000 ÷ $600 = 16.67
That’s roughly a 17:1 gold-to-silver ratio.
Why is that significant? Did you know America’s original Coinage Act of 1792 established a 15:1 silver-to-gold monetary ratio….
Now, important distinction:
This would NOT back the entire U.S. money supply.
Currency: ~$2.47T
Monetary base: ~$5.52T
M2: ~$23.22T
So $10K gold makes the strongest mathematical connection to physical currency in circulation, not every dollar sitting in bank accounts. And here’s another piece people shouldn’t overlook:
Congress has already seen legislation — S.954, the BITCOIN Act of 2025 — that would effectively revalue Treasury gold certificates to the fair market value of gold as part of funding a Strategic Bitcoin Reserve.
That does NOT mean $10,000 gold or $600 silver has been officially adopted. There has been no official Treasury announcement establishing those reset prices. But when you work backward from the numbers in this Debt Clock graphic…
$10,000 gold → ~$2.615T
Physical currency → ~$2.472T
Add in the historical comparison…. Suddenly those numbers don’t look completely random. I’m watching this one VERY closely.
US Debt Clock.org: usdebtclock.org
Reset Intelligence: Washington Puts a Price on Dollar Access.
Emailed to Recaps~ Thank you David
Reset Intelligence: Washington Puts a Price on Dollar Access.
By Reset Intelligence | @EXIT_FIAT
Bessent said the sentence: fuel an Iranian jet, land it, or sell it a ticket, and you are knocked out of the dollar system. At midnight it became the rule.
Riyadh quit China's payment rail. Baghdad rationed its own dollars. Tehran walked into the UN and asked for its accounts back.
Emailed to Recaps~ Thank you David
Reset Intelligence: Washington Puts a Price on Dollar Access.
By Reset Intelligence | @EXIT_FIAT
Bessent said the sentence: fuel an Iranian jet, land it, or sell it a ticket, and you are knocked out of the dollar system. At midnight it became the rule.
Riyadh quit China's payment rail. Baghdad rationed its own dollars. Tehran walked into the UN and asked for its accounts back.
The rule with no enforcer
The US Treasury did not ground Iran's airlines. It told every fueler, ground handler and ticket desk on earth that servicing a sanctioned Iranian carrier after September 23 costs them their dollar clearing. Washington never sends an inspector. Everyone with a dollar account inspects themselves. Iran's own aviation authority cancelled its Baghdad and Muscat flights from midnight before a single aircraft was turned away, and is negotiating to keep one pilgrimage lane into Najaf. Turkey and Georgia grounded the routes. Bessent named three foreign banks cut off for handling Iranian business: Banque Misr's Dubai branch, Turkey's Golden Global, and Russia's VTB.
Everyone paid in the same 72 hours
Saudi Arabia - quit mBridge, the China-built settlement network designed to move oil money without the dollar in the middle, restarted the East-West pipeline to Yanbu with 4 million barrels a day back on a route around Hormuz, and is being asked to co-fund a $10 billion rebuild fund with the US Treasury as senior partner.
July 1974 - the last time Riyadh made a dollar decision this large, Treasury Secretary William Simon closed it in Jeddah and the paperwork stayed secret for 4 decades. Same kingdom, same job.
Iran - Foreign Minister Araghchi sat 3 hours with Witkoff and Kushner and handed over three conditions that all asked for money: lift the blockade, unfreeze the assets, end the hostilities.
Trump - deal or annihilation from the UN podium, "completely isolate Iran financially" to 12 regional leaders, and the deal "right after the election."
Greenland - a permanent US security agreement signed the same day, Denmark's prime minister calling it a deal that lasts forever.
Baghdad rations its own dollars
The Central Bank of Iraq cut official-rate dollar access for travelers from once a month to once every 6 months and capped the cash at $2,000, keeping its reserves for trade and for defending the posted rate. The street closed near 157,000 per $100. Seven Iraqi banks have cleared the first phase of reconnection in currencies other than the dollar, with dollar business to follow after the harder compliance tests. Prime Minister al-Zaidi met ExxonMobil's chief executive after midnight in New York, and carries a request to Trump for more time on militia disarmament, a June 2027 completion agreed with the Coordination Framework before he flew. Washington's position has not moved since July. The 2027 budget, with its exchange-rate assumption line, reaches parliament October 15.
That is the short version. Why Iraq is the one country that has already been sitting Washington's dollar-access test for 2 years, what the extension request really means, and the watch list from here - that is the daily read.
Read the full daily briefing free for 5 days. Sign up here: the daily Iraqi dinar briefing
Want it straight from the horse's mouth? The CBI Rate Alert pings you the moment the Central Bank of Iraq moves the official rate. The number itself, not a rumour about it. It comes with our free resource library and the daily breakdown of what is actually moving in Iraq. Sign up free: The CBI Rate Alert
Got a dinar question? Reset Intelligence runs an on-call research assistant: ask it anything they have published. It answers in seconds and will conduct deep research to find you the answer. Try it: the Iraqi dinar research assistant
Common questions, answered straight: When will the Iraqi dinar revalue? and Is the Iraqi dinar revaluation real?
The design behind all of it is mapped in Head of the Snake, and the free guides live in the Iraqi dinar resource library.
Follow the daily intel free: Telegram · Facebook · Spotify · Odysee
Iraq Economic News and Points To Ponder Late Tuesday Evening 9-21-26
Who Is Running The Iraqi Economy? A Series Of Decisions Are Being Made, And The Market Is Paying The Price For The Lack Of Vision.
Last updated: September 22, 2026 In Iraq in recent weeks, questions have been escalating regarding the management of economic and monetary files, with a succession of decisions and measures affecting the banking sector, financial transfers, liquidity, the exchange market, and the movement of funds, at a time when an informed economic source believes that some of these decisions were taken amid the absence of an integrated economic vision or a sufficient explanation of their repercussions on the market.
Who Is Running The Iraqi Economy? A Series Of Decisions Are Being Made, And The Market Is Paying The Price For The Lack Of Vision.
Last updated: September 22, 2026 In Iraq in recent weeks, questions have been escalating regarding the management of economic and monetary files, with a succession of decisions and measures affecting the banking sector, financial transfers, liquidity, the exchange market, and the movement of funds, at a time when an informed economic source believes that some of these decisions were taken amid the absence of an integrated economic vision or a sufficient explanation of their repercussions on the market.
The source told the Independent Press Agency that the problem, according to his assessment, went beyond the issue of disagreement with a particular economic decision, to the nature of managing the economic file itself, and whether the decisions issued by the government and the central bank come within a coherent roadmap, or are separate measures taken under the pressure of developments and crises, and then their results are dealt with later.
He added that “the Iraqi market is now in a state of almost constant anticipation of the next decision,” considering that decisions that affect the movement of the dollar, transfers, cards, banks and liquidity cannot be treated as limited administrative instructions, because they are directly related to the interests of millions of citizens, merchants, companies and depositors.
According to the source, a number of economic measures during the past period were preceded by media talks and leaks, before moving to more serious stages or to implementation, which he considered an indicator that raises questions about the nature of decision-making and the mechanism for announcing it, especially since the markets are very sensitive to news related to the dollar, banks and liquidity.
He said that “when an economic decision is circulated in the market before its details are officially clarified, speculation begins on it before its implementation begins,” noting that merely talking about new restrictions or instructions may prompt traders and citizens to change their financial behavior, whether by increasing demand for the dollar, withdrawing funds, postponing transfers, or raising prices in anticipation of any possible development.
The source believes that one of the main problems lies in the lack of a detailed economic explanation accompanying some decisions, as the measure is often announced while the citizen and the merchant are left with questions about the reason for its issuance, its duration, its ultimate goal, and whether it is a temporary measure or part of a long-term policy.
These criticisms come at a time of significant transformation in the Iraqi banking system. Since 2025, the Central Bank has been implementing a comprehensive program to reform private, commercial, and Islamic banks, as well as branches of foreign banks.
This program requires banks to choose between options such as remaining in the market, merging, or exiting, while adhering to new standards related to governance, compliance, management, and risk.
In February 2026, the Central Bank announced that Iraqi banks had completed the phase of selecting these options, paving the way for an assessment of their compliance with the reform requirements.
The Central Bank presents these steps as part of a broad restructuring process for the banking sector and to enhance its ability to integrate into the global financial system, stressing that the new phase aims to strengthen governance, transparency, compliance and develop the institutional performance of banks.
However, the source believes that the scale of these transformations makes the need for calmer and clearer management even greater, because restructuring an entire banking sector has effects that are not limited to bank boards of directors, but extend to deposits, transfers, credit, trade finance, and the citizen’s confidence in the banking system.
He explained that while any broad regulatory measure may be technically necessary, the method of its implementation, its timing, and the management of its repercussions on liquidity and depositors are no less important than the decision itself.
The developments at Al-Taif Islamic Bank during September highlight the sensitivity of the banking sector. On September 8th, the Central Bank of Iraq affirmed that the rights of the bank's depositors were protected, explaining that placing it under receivership was a precautionary supervisory measure. The bank stated it was working to enhance liquidity, regulate withdrawals, and gradually fulfill obligations, prioritizing salaries deposited with it.
The source says that such cases should prompt economic institutions to treat the element of "trust" as an essential part of financial security, because news related to a bank, liquidity, or deposits can quickly have a psychological impact on other banks, even if they are not facing the same problem.
He added that the banking system does not operate on numbers alone, but also on trust, and that any shake-up in depositors’ confidence could lead to an increase in demand for cash and a move away from bank deposits, which contradicts the state’s stated goal of increasing financial inclusion and reducing reliance on cash.
Regarding liquidity, IMF reports reveal that the issue is more profound than a mere temporary shortage or surplus of cash. In its report on Iraq, the IMF noted persistently high levels of excess liquidity within the banking system, explaining that this limits the ability of monetary policy to effectively influence interest rates and credit, and calling for improved liquidity management and enhanced coordination between fiscal and monetary policy.
Here, according to the source, an important paradox emerges: there may be high liquidity at the level of the financial system as a whole, while parts of the market, some banks, or government entities face various difficulties in providing cash or managing financial flows at specific times.
He says that this difference is not adequately explained to the public, which sometimes leads to the term “liquidity” being used in a simplified way, even though liquidity in the central bank differs from the liquidity of the Ministry of Finance, and the liquidity of banks differs from the amount of cash in circulation in the hands of the public.
The IMF also noted in its assessment that the effectiveness of Iraqi monetary policy remains limited due to the weak transmission of central bank decisions to lending and deposit rates, as well as the heavy reliance on the public sector and the nature of the domestic financial system.
The source believes that this picture reveals that the crisis is not due to a single decision, but rather to an economic structure that requires higher coordination between the government, the Ministry of Finance, the Central Bank, banks, and regulatory bodies.
In another context, the Central Bank affirms that it possesses sufficient foreign reserves to meet legitimate demand for foreign currency, finance foreign trade, settle bank card payments, and process travelers' requests at the official exchange rate. In a statement issued on September 19, 2026, the Central Bank attributed the rise in the dollar's price on the local market to speculation, market expectations, and the exploitation of geopolitical circumstances, while emphasizing the continued financing of trade through established channels.
However, the source says that having high reserves alone does not prevent disruptions in the parallel market if citizens or traders face difficulty accessing dollars at the official rate or if restrictions and procedures related to obtaining them increase.
He adds that the difference between the official price and the parallel market in this case becomes an indicator not necessarily of a shortage of reserves, but rather of a gap between the real demand for currency and the ability of official channels to meet it easily and quickly.
The IMF takes a somewhat similar approach, noting in its assessment that simplifying access to foreign currency, improving customs controls, and encouraging the use of the dinar in some transactions are factors that can help reduce the gap between the official and parallel exchange rates.
The source says that addressing the exchange rate cannot rely solely on security or regulatory measures, because the demand for dollars also stems from the structure of the Iraqi economy, which is largely based on imports, and therefore any restrictions on access to foreign currency could quickly translate into commodity prices.
He added: “If the trader imports in dollars, any increase in the cost of accessing dollars will ultimately be passed on to the consumer.”
In contrast, the Central Bank points to the transfer of foreign trade financing to commercial banks and their relationships with correspondent banks, a step that the IMF considered an important development in modernizing the Iraqi financial system.
The Central Bank also announced in July 2026 that it had reached understandings allowing a number of restricted Iraqi banks to return to foreign correspondent channels in currencies other than the dollar after they met the requirements for compliance, governance and reform.
The source considers these measures to represent a fundamental shift in the Iraqi financial structure, but they require a clear transition period, because transferring the transfer system from one system to another and subjecting banks to stricter standards may lead to temporary pressures on some institutions and customers.
He argues that the problem begins when reforms that are theoretically correct are implemented without providing sufficient alternative pathways for the market during the transition period.
He adds that “reform is not measured by the strength of the decision, but rather by the economy’s ability to withstand the decision.”
This issue is all the more important given Iraq's heavy reliance on oil revenues. In a technical report issued in July 2026, the IMF indicated that the Iraqi economy faces medium-term risks related to volatile oil prices, high debt levels, and regional instability, emphasizing the importance of strengthening coordination between fiscal and monetary policies and implementing financial sector reforms.
The IMF also expects, based on its current data for Iraq, that real GDP will contract by 6.8% during 2026, with an expected inflation rate of around 3%.
The source says these indicators make the margin of error in economic decision-making narrower, because an economy that is heavily dependent on oil and affected by government spending, energy prices and regional tensions needs careful management of shocks.
He believes that the government and the central bank should move from a policy of "managing the problem after it happens" to a policy of anticipating crises before they occur.
He added that what is needed is a clear model that answers, before any decision is issued, a set of basic questions: What will happen to the dollar exchange rate? What will happen to liquidity? What will happen to banks? What will happen to traders? And how will the decision affect the prices of goods and the citizen?
The source believes that these questions are not adequately addressed in the official discourse accompanying the decisions.
The issue of coordination between the government’s fiscal policy and the central bank’s monetary policy also stands out, a point repeatedly emphasized by the IMF, particularly with regard to liquidity management, government spending, deficit financing and price stability.
The source says the central bank can use its monetary tools, but it cannot single-handedly address the imbalances resulting from government spending, weak non-oil revenues, a high payroll, or weak domestic production.
Conversely, the government cannot manage economic policy in isolation from the impact of its decisions on liquidity, the exchange rate, and the central bank's reserves.
Hence, the source believes that the real problem is not the multiplicity of institutions, but rather the extent to which there is an “economic command room” capable of unifying decisions and setting priorities.
Regarding the state-owned banks, the IMF indicated that reforming Rafidain and Rasheed banks remains a key issue, with the need to address non-performing loans, capital shortages, governance, and digital infrastructure.
The source believes that any reform of the private banking sector will not achieve its full results if the state-owned banks, which dominate a large part of financial activity, remain in need of deep restructuring.
He says that the private banking sector today faces compliance, oversight, merger, or exit requirements, while reforming the state banking structure remains a parallel challenge that cannot be ignored.
The source asks: "Is the goal to actually build a competitive banking system, or just to rearrange the names of existing banks?"
In his view, true reform should be reflected in the citizen's ability to easily open an account, transfer funds, obtain credit, use his card locally and internationally, and feel secure when depositing his money.
If restrictions increase, procedures become more complicated, and access to funds decreases, citizens may revert to keeping cash outside the banking system, which is the opposite of what the state is trying to achieve.
The source also warns of the impact of repeated decisions on the private sector, explaining that investors need a predictable environment, and that any continuous change in banking, tax, customs or transfer instructions makes calculating future costs more difficult.
He says that capital “fears uncertainty more than it fears difficult decisions,” because an investor can adapt to strict rules if they are clear and stable, but finds it difficult to operate when the rules change frequently.
He points out that economic reform also requires greater transparency in data dissemination, not just advertising.
The source suggests that major economic decisions should be accompanied by an “economic impact paper” that explains to citizens and markets the reasons for the decision, its objective, the expected timeframe for its implementation, the sectors that will be affected by it, and the results that the government or the central bank will consider as a benchmark for its success.
It also calls for the publication of a subsequent evaluation of each decision to see whether the actual results matched expectations.
He adds: "If the results of the decision are not measured, how can we know that it was successful?"
At the same time, it cannot be ignored that the Central Bank operates within a complex financial environment related to international compliance, anti-money laundering and counter-terrorism financing, and the relationships of Iraqi banks with correspondent banks around the world.
The Central Bank has confirmed that its reforms aim to reintegrate Iraqi banks into the international financial system and develop their ability to carry out cross-border transfers in multiple currencies.
But the source believes that the challenge is not choosing between “reform” and “not reforming,” but rather between organized and well-thought-out reform and reform that may have a high transitional cost if it is not managed properly.
To consider any objection to the implementation mechanism as a rejection of reform as an oversimplification of the problem, because the market and the citizen have the right to know the cost of the reform, its timetable and the expected results from it.
In conclusion, recent developments reveal that Iraq is facing a sensitive economic phase in which the issues of banking reform, liquidity, the dollar, government spending, dependence on oil, and international financial relations are intertwined.
While official institutions assert that the current measures aim to build a more efficient, transparent banking sector capable of integrating into the global financial system, critics argue that the speed of the transformations and the multiplicity of decisions require a higher level of coordination, explanation, and transparency.
The question posed by the source remains: Who has a complete economic vision for Iraq?
Is there a clear plan linking the decisions of the Central Bank with those of the Ministry of Finance, the government, trade, customs, and banks, or does each institution operate within its own sphere of influence, and then the market is later asked to bear the consequences?
The source concludes by saying that Iraq does not need more decisions as much as it needs “one comprehensive economic decision in one direction,” because the economy is not managed by experimentation, and the citizen, the merchant, and the bank should not be a testing ground for policies.
Ultimately, the decision can be amended, and new instructions can be issued, but trust, once damaged, is much more difficult to restore.
The question that will remain for the government and the central bank during the next stage is: Are the decisions driven by a clear economic vision, or are the decisions driven by crises
https://mustaqila.com/من-يدير-الاقتصاد-العراقي؟-قرارات-متلا/
Seeds of Wisdom RV and Economics Updates Wednesday Morning 9-23-26
Good Morning Dinar Recaps,
U.S. PAYMENT RESET WATCH: BANK-ISSUED STABLECOIN GOES LIVE ACROSS MASTERCARD'S $25 BILLION CARD PROGRAM
SoFi Bank and Mastercard have moved bank-issued stablecoin settlement from development into live operation, connecting blockchain-based money movement with an established global card network.
Good Morning Dinar Recaps,
U.S. PAYMENT RESET WATCH: BANK-ISSUED STABLECOIN GOES LIVE ACROSS MASTERCARD'S $25 BILLION CARD PROGRAM
SoFi Bank and Mastercard have moved bank-issued stablecoin settlement from development into live operation, connecting blockchain-based money movement with an established global card network.
OVERVIEW
SoFi Bank and Mastercard have launched live stablecoin settlement across SoFi’s debit and credit card program, with the program expected to process more than $25 billion in annualized volume using SoFiUSD.
SoFiUSD, a U.S. dollar stablecoin issued by the nationally chartered SoFi Bank, is being used behind the scenes to settle transactions on Mastercard’s global payments network while consumers and merchants can continue using the familiar card system.
The development represents a significant step in connecting traditional banking, blockchain settlement, stablecoins and global payments infrastructure, while broader uses such as cross-border payments and additional merchant settlement remain areas for further expansion.
KEY DEVELOPMENTS
1. Stablecoin settlement moves into live production
SoFi and Mastercard announced that stablecoin settlement is now live across SoFi Bank’s debit and credit card program.
The program is expected to process more than $25 billion in annualized volume, meaning this is no longer simply a small-scale blockchain experiment. The companies are moving an existing payments operation onto stablecoin settlement infrastructure.
The settlement token is SoFiUSD, a U.S. dollar stablecoin issued by SoFi Bank, N.A., a nationally chartered bank regulated by the Office of the Comptroller of the Currency.
SoFiUSD is designed to be redeemable 1:1 for U.S. dollars and is supported primarily by cash reserves. SoFi also makes clear that SoFiUSD itself is not a bank deposit, is not FDIC or SIPC insured, is not bank-guaranteed and is not legal tender.
That distinction is important as the financial system develops new forms of digital money.
2. The blockchain operates underneath familiar card payments
Consumers do not need to change the way they use their SoFi cards.
The significance is occurring at the settlement layer.
Rather than requiring consumers or merchants to directly use cryptocurrency, the blockchain-based stablecoin infrastructure operates behind the existing card-payment experience.
SoFi says merchants can receive settlement funds through its banking platform and withdraw them into cash, while the underlying settlement process uses SoFiUSD.
This creates an important bridge:
Traditional Cards → Bank-Issued Stablecoin → Blockchain → Settlement → Bank Account
The technology is being inserted into existing financial infrastructure rather than requiring the entire financial system to be replaced.
3. Mastercard is building stablecoins into its broader settlement infrastructure
The SoFi launch follows Mastercard’s broader move to provide stablecoin settlement options across its global network.
In June, Mastercard announced plans to support regulated stablecoins including USDC, PYUSD, USDG, USDP, RLUSD and SoFiUSD, along with settlement on multiple blockchain networks.
Mastercard said the expanded settlement capabilities are intended to give issuers and acquirers greater flexibility over when and how transactions settle, including intraday, weekend and holiday settlement options.
That has implications for liquidity management because conventional financial settlement often operates according to banking and market schedules.
Blockchain-based settlement can potentially operate continuously.
4. The focus is shifting from crypto payments to financial settlement
One of the most important distinctions in this development is that stablecoins are not necessarily being positioned as replacements for traditional cards.
Instead, they are increasingly being used as settlement infrastructure behind traditional payment systems.
Mastercard's stated strategy is to allow digital assets and traditional payment systems to operate alongside one another. Its March agreement with SoFi specifically described the goal as connecting regulated stablecoins with traditional forms of money and exploring applications such as cross-border remittances and business-to-business transfers.
That suggests an evolving model:
Fiat Money + Stablecoins + Tokenized Assets + Blockchain Rails + Traditional Payment Networks
The financial system does not necessarily have to choose between the old infrastructure and the new infrastructure.
The two can increasingly become interconnected.
5. Cross-border payments could become the next major application
SoFi and Mastercard said they will explore additional uses for SoFiUSD, including cross-border payments, remittances and other money-movement applications.
These applications are particularly important because international payments can involve multiple banks, currencies, intermediaries and settlement schedules.
Stablecoins potentially allow value to move on blockchain networks while remaining denominated in a familiar national currency such as the U.S. dollar.
That creates another important financial-system chain:
Dollar → Stablecoin → Blockchain → Cross-Border Payment → Settlement
The technology does not eliminate the role of the dollar. Instead, it can create new digital rails through which dollar-denominated value moves.
6. The development strengthens the connection between banking and digital assets
SoFiUSD is being issued by a regulated national bank rather than solely by a standalone cryptocurrency company.
That is significant because it demonstrates how commercial banking institutions can become issuers and operators within digital-asset infrastructure.
Mastercard's broader settlement initiative also includes multiple regulated stablecoins and blockchain networks, showing that the emerging system may involve interoperability among banks, payment networks, stablecoin issuers and tokenized financial assets.
The larger transition is therefore not simply:
Banking → Crypto
It is increasingly:
Banking + Digital Assets + Blockchain + Payments
WHY IT MATTERS
The most important part of this development is not that a new cryptocurrency payment option has appeared.
It is that blockchain-based settlement is being placed underneath an established financial network that already processes enormous amounts of payment activity.
That is a very different stage of adoption.
The consumer may not even notice the technological change.
The infrastructure underneath the transaction is what is changing.
This is consistent with a broader financial-system transformation in which traditional money, tokenized assets, stablecoins and blockchain networks increasingly operate together.
WHY IT MATTERS TO FOREIGN CURRENCY HOLDERS
For foreign currency holders following the Global Reset, the important issue is the infrastructure surrounding currencies.
A currency's international usefulness depends partly on how efficiently it can be:
Transferred
Settled
Tokenized
Used for cross-border payments
Connected to financial institutions
Integrated with digital payment networks
The SoFi-Mastercard development does not mean the dollar is being replaced, nor does it announce a currency revaluation.
In fact, this particular development demonstrates something different: the existing U.S. dollar is being connected to new digital settlement infrastructure.
That is important because the future financial system may involve national currencies moving through increasingly digital and programmable rails.
Hope, not hype. Follow the evidence.
IMPLICATIONS FOR THE GLOBAL RESET
Pillar 1: Payments
Stablecoin settlement can provide another way for financial institutions to move and settle dollar-denominated value.
Pillar 2: Technology
Blockchain is moving beyond cryptocurrency trading and into the settlement layer of mainstream financial transactions.
Pillar 3: Banking
A nationally chartered bank issuing a stablecoin demonstrates how regulated banking institutions can participate directly in digital-money infrastructure.
Pillar 4: Currencies
The development shows how the U.S. dollar can be incorporated into new digital payment rails without requiring the currency itself to change.
Pillar 5: Global Settlement
Mastercard's expansion of stablecoin settlement creates potential infrastructure for faster and more flexible movement of money across borders and outside traditional banking schedules.
THE GLOBAL RESET CONNECTION
The developing sequence is:
Bank → Stablecoin → Blockchain → Card Network → Settlement → Liquidity → Cross-Border Payments → Digital Financial Infrastructure
This is why the development belongs on the Global Reset Watch.
The financial system does not necessarily change through one dramatic event.
It can change through thousands of infrastructure decisions that gradually alter how money moves, how assets settle and how financial institutions connect with one another.
The SoFi-Mastercard launch is one documented example of that process moving from concept to live operation.
RUMOR SAFETY REMINDER
This development is not an announcement of a global currency reset, dollar revaluation or replacement of traditional currencies.
The stablecoin settlement system is live for SoFi's card program, but broader applications—including additional merchant, cross-border and remittance uses—remain areas of ongoing development and are subject to regulatory considerations.
Our Reset Watch follows documented changes in financial infrastructure. It does not predict reset dates or guarantee future currency values.
Watch the evidence. Follow the infrastructure. Hope, not hype.
THE BOTTOM LINE
SoFi and Mastercard have moved bank-issued stablecoin settlement into live operation across a card program expected to process more than $25 billion annually, demonstrating how blockchain-based settlement can begin operating inside established financial infrastructure.
The bigger story is not simply that another stablecoin has launched—it is that traditional banking, digital dollars, blockchain networks and global payment systems are beginning to operate as connected pieces of the same financial architecture.
When the rails that move money begin to change, the evolution of the global financial system is already underway beneath the surface.
Seeds of Wisdom Team
Newshounds News™ Exclusive
SOURCES
~~~~~~~~~~
🌱 A Message to Our Currency Holders🌱
If you’ve been holding foreign currency for many years, you were not foolish.
You were not wrong to believe the global financial system would change.
What failed was not your patience — it was the information you were given.
For years, dates, rumors, and personalities replaced facts, structure, and proof. “This week” predictions created cycles of hope and disappointment that were never based on how currencies actually change.
That is not your failure.
Our mission here is different: • No dates • No rates • No hype • No gurus
Instead, we focus on:
• Verifiable developments • Institutional evidence
• Global financial structure • Where countries actually sit in the process
Currency value changes only come after sovereignty, trade, banking, settlement systems, and fiscal coordination are in place. History and institutions confirm this sequence.
You will see silence. You will see denials. That is not delay — that is discipline.
Protect your identity. Organize your documents. Verify everything.
Never hand your discernment to anyone who cannot show proof.
You deserve truth — not timelines.
Seeds of Wisdom Team
Newshounds News
~~~~~~~~~~
Seeds of Wisdom Team RV Currency Facts Youtube and Rumble
Newshound's News Telegram Room Link
RV Facts with Proof Links Link
RV Updates Proof links - Facts Link
Start Here room with Most Asked Questions Link
Follow the Gold/Silver Rate COMEX
Follow Fast Facts
Seeds of Wisdom Team™ Website
Thank you Dinar Recaps
"Chuck The Debt In The Fire" Is Officially A Real Solution
"Chuck The Debt In The Fire" Is Officially A Real Solution
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 9, 2026
It's so simple, how could no one have thought of this before? The man currently polling in second place to become the next President of France has put forward an ingenious solution to tackling France's national debt, currently standing at around 117% of the country's GDP.
Jean-Luc Mélenchon says, "All we have to do is take the 18% held by the Bank of France and chuck it in the fire."
"Chuck The Debt In The Fire" Is Officially A Real Solution
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 9, 2026
It's so simple, how could no one have thought of this before? The man currently polling in second place to become the next President of France has put forward an ingenious solution to tackling France's national debt, currently standing at around 117% of the country's GDP.
Jean-Luc Mélenchon says, "All we have to do is take the 18% held by the Bank of France and chuck it in the fire."
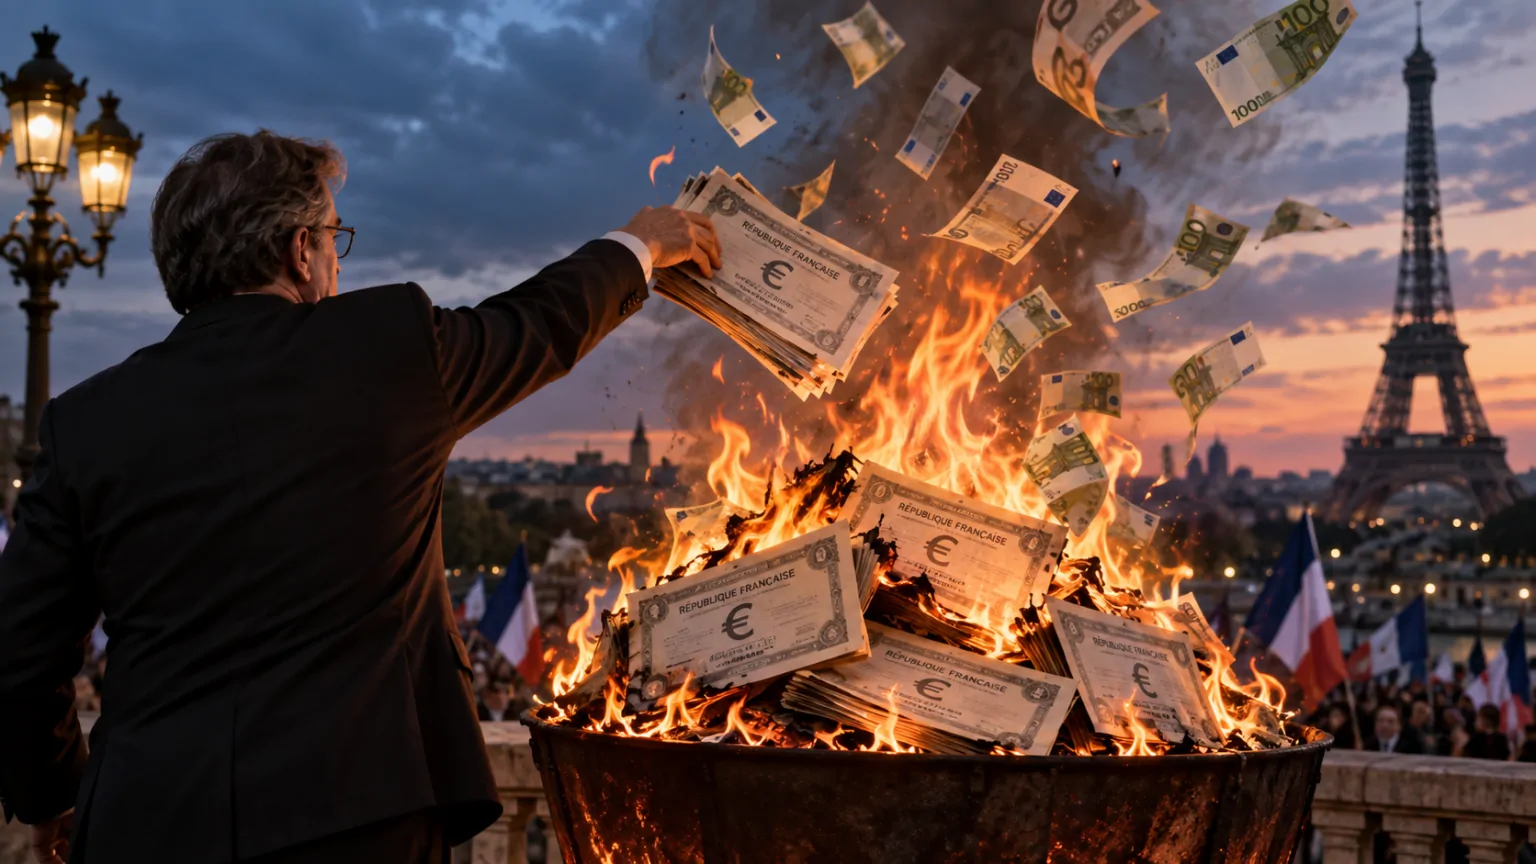
This is the guy who has a real shot at running the second-largest economy in the eurozone, and he's telling voters that roughly €636 billion of what their government owes can simply be erased.
And the voters like the sound of it. Of course they do, who doesn’t love getting something for nothing?
Quick economics lesson for the brilliant man who wants to lead France: the Bank of France bought those bonds with euros it created for the purpose… the European Central Bank's own explainer says buying bonds "creates money in the banking system."
Normally those euros come back out of circulation as the debt gets repaid. Mélenchon's plan skips that part: the government ‘throws the debt in the fire’ and doesn’t pay it back. So the central bank eats the loss... meaning that the €636 billion conjured out of nothing stays in the system.
This creates inflation, plain and simple.
Goods and services cannot be created out of nothing. Euros can. So when there’s suddenly more money in the system relative to the same amount of goods and services, the end result is inflation.
The other obvious implications is that France would still owe the rest of its debt... and those lenders will have seen that France is willing to default. I wonder what that would do to French bond yields?
Or maybe they’ll rest easy with Mélenchon’s assurance that “I’m not going after private creditors, not at this step in any case.”
Why do French voters even care about the national debt? Because they’ve been feeling the consequences of idiotic fiscal policy for years.
Interest alone costs the French government more than its entire defense budget. There's no taxing their way out, either: the French are already the second-most-taxed people in the developed world, at about 44% of GDP.
So every fix takes some benefit away from taxpayers. Last year's plan canceled two public holidays, froze pensions, and cut civil-service jobs... and the prime minister who proposed the solutions was thrown out.
The plan before that raised the retirement age from 62 to 64 brought the biggest protests France had seen in decades; that plan has now been suspended to keep the current government alive.
Meanwhile, growth was less than 1% last year, and unemployment is at its highest since 2020.
And here comes Mélenchon with a plan that costs nobody anything: delete a portion of the debt and go back to spending as if everything is OK.
However dumb the solution, at least the French are talking about the problem.
The US government crossed $40 trillion in debt last month. That's roughly 123% of GDP, worse than France.
America gets away with it, for now, because the dollar is still the world's reserve currency. Central banks hold a lot of their strategic financial reserves in US Treasury bonds, so Congress has always had a line of foreigners waiting to lend it money no matter how large the deficit.
But that line of foreigners is now getting shorter. Foreign holdings of Treasuries fell by $72 billion in June alone, China's are at their lowest since 2008, and so far this year foreigners have bought just 7% of the new debt the US government issued.
The reasons aren't a mystery: a dysfunctional government that can’t even pass a budget or eliminate fraud from its spending, while increasingly weaponizing access to the US dollar system.
When the foreign buyers stop showing up, America finds itself with France's problem. Automatic cuts to Social Security are only six years away. Interest on the debt is already larger than the defense budget.
Extreme government spending is already pushing inflation higher... and socialists are everywhere now promising to spend even more.
These people genuinely believe that money is something you can conjure out of thin air with no consequence.
But whether they cancel the debt, or simply continue to ignore it, the consequence ultimately comes back to inflation.
That’s because conjuring money out of thin air, or borrowing from future generations to spend today, doesn't produce one more barrel of oil, one more bushel of wheat, or one more pound of copper. It just produces more euros and dollars.
America has been here before.
Through the 1970s the US government ran deficits for Vietnam AND a historic expansion of welfare spending... then cut the dollar's last link to gold in 1971. They created new money to cover the difference.
Consumer prices doubled over the decade, and the Dow finished 1979 where it started 1970, which after inflation was a loss of about half in real terms.
Meanwhile, gold went from $35 an ounce to $850. And oil went from about $3.40 a barrel to nearly $30. The world’s most important (and scarce) resources not only held their value, but they dominated. And the companies that produced them did far better.
Over roughly the same stretch, Barron's index of gold mining stocks rose more than 1,200% while the S&P 500 managed 43%.
The new money has to go somewhere, and it flows into whatever the government cannot create more of.
Today, a lot of the companies that produce those real assets like metals, energy, food, and the ships that carry them, are still cheap.
We find them for subscribers of our investment research newsletter, Strategic Assets.
Gold and silver moved first, as central banks started diversifying out of the dollar. A small silver producer we featured in April 2025 rose more than 10x in ten months. A gold producer has gone up 5x, yet it's earning money so fast that the stock is cheaper against its earnings today than the day we wrote it up. It pays a dividend, too.
Now the rest is showing life. A zinc producer we featured is up more than 150% in under a year. A tin miner is up more than 230% and trading at all-time highs. Two oil tanker owners we bought when nobody wanted them are up more than 150% and 110%, and one just reported the best quarter in its history.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
MilitiaMan & Crew: What’s Happening with the Iraqi Dinar? Daily News & Analysis
MilitiaMan & Crew: What’s Happening with the Iraqi Dinar? Daily News & Analysis
9-22-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
MilitiaMan & Crew: What’s Happening with the Iraqi Dinar? Daily News & Analysis
9-22-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
Be sure to listen to full video for all the news……..
Iraq Economic News and Points To Ponder Tuesday Afternoon 9-22-26
CBI currency sales drop $18.5B in eight months
2026-09-22 Shafaq News- Baghdad The Central Bank of Iraq's (CBI) foreign currency sales fell 34.5% year-on-year to about $35.27 billion in the first eight months of 2026, down from roughly $53.83 billion during the same period in 2025, according to CBI data. The CBI sold about $3.697 billion in foreign currency in August, including $270 million in cash sales and $3.427 billion to boost banks' balances abroad.
CBI currency sales drop $18.5B in eight months
2026-09-22 Shafaq News- Baghdad The Central Bank of Iraq's (CBI) foreign currency sales fell 34.5% year-on-year to about $35.27 billion in the first eight months of 2026, down from roughly $53.83 billion during the same period in 2025, according to CBI data. The CBI sold about $3.697 billion in foreign currency in August, including $270 million in cash sales and $3.427 billion to boost banks' balances abroad.
Foreign currency sales reached $5.662 billion in July and $5.857 billion in June, compared with $5.092 billion in May, $4.559 billion in April, $3.388 billion in March, $4.133 billion in February and $2.883 billion in January.
https://shafaq.com/en/Economy/CBI-currency-sales-drop-18-5B-in-eight-months
Saudi East-West Pipeline Resumes Operations
2026-09-22 Shafaq News- Riyadh Saudi Arabia on Tuesday restarted its East-West oil pipeline after a nine-day shutdown caused by drone attacks, restoring a key route used to bypass disruptions in the Strait of Hormuz, three sources briefed on the matter told Reuters.
The pipeline was initially operating at a low rate, two sources said, while Saudi Aramco was seeking to restore flows to about 4 million barrels per day (bpd), around 4% of global oil supply. One security source estimated that a full resumption could take weeks.
The September 13 attacks had shut the pipeline and halted crude loadings at the Red Sea port of Yanbu. Since oil flows through the Strait of Hormuz were disrupted following the US-Israeli war on Iran, Saudi Arabia has used the route to move about 4 million bpd to Yanbu.
Crude supply to Aramco’s Red Sea refineries will also resume, with a cargo bound for China scheduled to load at Yanbu later on Tuesday. Tankers were being moved to Egypt’s Port Said for ship-to-ship transfers and also to Sidi Kerir ahead of renewed Saudi loadings, two trading sources told the agency.
The restart helped drive selling in global oil markets, traders said, with Brent crude futures falling more than $2 a barrel to their lowest level since September 8.
https://shafaq.com/en/Economy/Saudi-East-West-pipeline-resumes-operations
Oil Climbs As Traders Await US-Iran Developments
2026-09-22 Shafaq News Oil prices gained for the first time in five sessions on Tuesday as investors awaited developments on potential US-Iran talks at the United Nations General Assembly this week after more supplies emerged through the Strait of Hormuz over the weekend.
The Brent crude futures November contract rose $1.14, or 1.1%, to $101.48 a barrel at 0317 GMT. The WTI October contract, which expires on Tuesday, climbed 87 cents, or 0.9%, to $96.65 a barrel.
The more actively traded November contract was up 85 cents, or 0.9%, at $93.22 a barrel.
Tehran and Washington exchanged threats on Sunday, though US President Donald Trump said he would be open to meeting Iranian President Masoud Pezeshkian, who is expected to be in New York this week for the UN meeting.
"The move higher in WTI and the stronger open in Brent have the appearance of a typical short-covering bounce after the recent decline, rather than a fundamental shift," said Tim Waterer, chief market analyst at KCM Trade.
"Traders who were positioned for further downside are taking some risk off the table while the diplomatic narrative plays out."
Over the weekend, Iran also conveyed its conditions to mediators for re-engaging in negotiations, Al Jazeera reported, citing Iran's security chief, Mohsen Rezaei.
Waterer said oil prices were likely to remain range-bound and sensitive to headlines until there was either clear progress or a setback in diplomatic efforts between the US and Iran.
Middle East tensions remained elevated after Yemen's Iran-backed Houthis said they attacked Riyadh and a Saudi Aramco facility in Yanbu and stepped up efforts to cut off Saudi-backed forces from the Red Sea coast.
China has privately urged Tehran to help curb attacks by the Houthis, three Iranian sources said, after Saudi Arabia appealed to Beijing following a recent surge in the group's military operations.
Saudi Aramco has increased exports through the Strait of Hormuz after attacks on its East-West Pipeline forced it to halt some shipments through Yanbu. Around 14 million barrels of its crude oil were loaded on seven supertankers inside the Gulf on Sunday, tanker tracking data showed.
"Supply concerns are easing as shipments through the Strait of Hormuz reach a six-month high and Saudi Arabia works to restore its East-West pipeline...Crude implied volatility eased 3.3% to 50.39, although it remains historically elevated," said Saxo Bank analysts in a client note.
Separately, an armed group closed valve seven on Libya's Sharara crude pipeline to Zawiya port on Monday, resulting in a significant decline in production at the Sharara oilfield, Libya's National Oil Corporation said in a statement.
Production at the field has fallen by around 200,000 barrels per day and is currently between 100,000 and 105,000 bpd, two engineers at the field told Reuters. (Reuters)
https://shafaq.com/en/Economy/Oil-climbs-as-traders-await-US-Iran-developments
Basrah Crudes Slip Despite Global Benchmark Gains
2026-09-22 Shafaq News- Basrah Iraq’s Basrah crude prices remained above $90 a barrel on Tuesday, while global oil benchmarks moved higher.
Basrah Heavy stood at $90.27 a barrel, while Basrah Medium was priced at $93.57.
The two grades had each fallen $0.80 in their previous trading session, with Basrah Heavy down 0.88% and Basrah Medium 0.85%.
Global oil prices rose on Tuesday as investors awaited potential US-Iran talks at the UN General Assembly.
Brent crude climbed above $101 a barrel, while US West Texas Intermediate also gained in early trading.
https://shafaq.com/en/Economy/Basrah-crudes-slip-despite-global-benchmark-gains
IMF, World Bank Revise Debt Risk Assessments
2026-09-21 Shafaq News- Washington The International Monetary Fund (IMF) and World Bank are revising their debt assessment framework for low-income countries following its first review since 2017, with the updated system expected to take effect in the second half of 2027, the IMF said on Monday.
According to the IMF, debt risks have become more complex since the previous review, with debt levels rising in many low-income countries and governments increasingly borrowing from domestic and foreign sources on commercial terms.
The changes will sharpen the distinction between countries facing debt stress and those whose debt is considered unsustainable. They will also refine how debt-carrying capacity is measured and expand the thresholds and tools used to identify risks.
Greater attention will also be given to domestic debt and long-term pressures, including development needs and climate adaptation. The IMF said the changes should help governments assess how much fiscal space they have for investment while managing debt vulnerabilities.
Other measures include stronger stress tests and tools to assess the accuracy of economic forecasts. The framework will encourage countries to improve the coverage, transparency and reliability of public debt data.
IMF Executive Directors broadly supported the changes but called for clear guidance, communication and training before implementation. Most directors also backed temporarily withholding the probability thresholds and country-specific mechanical signals generated by a new model for assessing unsustainable public debt while the IMF gains experience with the methodology.
The review kept the harmonized discount rate used under the LIC-DSF and the IMF's Debt Limits Policy unchanged at 5%.
Introduced in 2005, the framework guides IMF and World Bank assessments of debt risks in low-income countries and informs lending, fiscal policy and public debt management. It underwent previous reviews in 2006, 2009, 2012 and 2017.
https://shafaq.com/en/Economy/IMF-World-Bank-revise-debt-risk-assessments
Iraq Is Preparing To Launch A Strategic Project For Steel Industries
Money and business Economy News — Baghdad The Ministry of Industry and Minerals announced on Tuesday the launch of the second phase of a strategic project for steel industries, with the aim of enhancing the production of rebar locally and providing multiple types and sizes of it to meet the needs of the local market.
The Director of the General Company for Steel Industries at the Ministry, Ahmed Hamed Zainuddin, said that "the rolling and continuous casting project for steel industries consists of two phases, the first of which includes the project of continuous arc casting, which completed the development and modernization of its production lines in accordance with the latest technologies and technological methods, during the month of May of 2024, which contributed to enhancing its operational capacities."
He added that "the said project currently produces 600 thousand tons per year of pallet, and is the primary and basic material for the operation of the rolling project, which he stressed that providing it locally will contribute to support the production chain and reduce the need to import raw materials in the rebar industry."
He pointed out that the second phase of the project, which will be opened soon, will allow the production of rebar with various measurements required in the local markets, starting from 8 to 44 mm, with a production capacity of about 400 thousand tons per year, as well as the production of about 200 thousand tons per year of industrial iron.
He stressed that "the project represents an important step in supporting the industrial sector and enhancing its ability to meet part of the local demand for iron products, as well as providing the market with a local product according to the required specifications, which enhances the presence of the national industry in the market and reduces dependence on imported products."
He pointed out that "the operation of the project in its various stages will not be limited to increasing local production, but will contribute to the revitalization of sectors related to the iron and steel industry," stressing that "the company is continuing to complete the technical and operational requirements of the project in preparation for the start of commercial production, in line with government plans to qualify and operate industrial projects and increase the production capacities of public companies."
Gold’s Investment Case Has Fundamentally Changed, And Rising Yields Are No Longer A Dealbreaker
Gold’s Investment Case Has Fundamentally Changed, And Rising Yields Are No Longer A Dealbreaker - FTSE Russell’s De
By Neils Christensen (Kitco News) - Rising bond yields are creating a significant headwind for gold, but investors should be careful about applying the precious metal’s traditional relationship with interest rates too rigidly, as structural changes in global demand continue to support elevated prices, according to FTSE Russell.
Gold’s Investment Case Has Fundamentally Changed, And Rising Yields Are No Longer A Dealbreaker - FTSE Russell’s De
By Neils Christensen (Kitco News) - Rising bond yields are creating a significant headwind for gold, but investors should be careful about applying the precious metal’s traditional relationship with interest rates too rigidly, as structural changes in global demand continue to support elevated prices, according to FTSE Russell.
In an interview with Kitco News, Indrani De, Head of Global Investment Research at FTSE Russell, said both nominal and real yields are moving higher, which traditionally increases the opportunity cost of holding a non-yielding asset like gold. However, she said the gold market has undergone a fundamental shift as central banks have become increasingly important buyers.
De explained the growing influence of central-bank demand is a significant reason why gold has become somewhat less sensitive to rising real yields. She noted that central banks were net sellers of gold from 2000 until the Global Financial Crisis, before becoming net buyers. More recently, the pace of purchases has accelerated substantially.
“ The extent to which central banks are buying gold today, in the last two, three years, is more than twice the level of what it was between 2010 and 2021,” she said.
She added that this demand matters because official-sector buyers generally aren't making allocation decisions based on the opportunity cost created by higher bond yields.
“We now have a huge chunk of demand for gold coming in from sources that are not sensitive to yields,” she said. “That is one very big reason why you see much more of a decoupling between the rising yields and gold prices.”
That shift is also showing up in global reserve allocations. De said that at current valuations, central banks collectively hold more gold than U.S. Treasuries. At the same time, she noted that the U.S. dollar's share of global foreign-exchange reserves has been on a structural downtrend, falling from just above 70% around the turn of the century to between 55% and 57% today.
However, De pushed back against the idea that this trend means central banks are simply losing faith in the U.S. dollar.(Kitco Global Index shows how much of today's gold move is the dollar versus the gold market itself.)
She said the dollar's dominant role remains largely unquestioned because there is no viable alternative of comparable scale. Instead, she characterized the trend as a gradual diversification of reserves amid a changing geopolitical and economic landscape.
De also expects official-sector gold demand to remain an important feature of the market. Although purchases could retreat from the exceptionally high levels of recent years, she said demand is geographically broad, including central banks across Asia and Latin America, while heightened geopolitical uncertainty is unlikely to disappear anytime soon.
At the same time, central banks are no longer the only important source of demand. De said investment demand through retail investors and gold-backed exchange-traded products has also increased, giving the market a broader base of buyers.
Gold, she added, continues to function as an inflation and geopolitical-risk hedge and offers another potential advantage as concerns surrounding currency debasement grow.
“Gold has the stability to it also,” she said. “Gold has many strengths which counter the headwinds from rising yields.”
While higher yields remain a risk for gold, De said investors also need to understand why yields are rising. Fiscal concerns across developed economies are one factor, with De describing the current environment as one of growing “fiscal dominance,” where fiscal policy increasingly overpowers monetary policy.
But not all of the rise in yields is necessarily negative for gold.
De said the global economy is moving away from the post-financial-crisis era of abundant cheap capital. Capital is becoming scarcer because there are increasingly productive uses for it, including artificial intelligence, infrastructure investment, reshoring and the global green energy transition.
She said this repricing of capital can ultimately support stronger productivity, while higher borrowing costs also put pressure on less productive “zombie companies.”
“There are a lot of good reasons why yields are increasing, and we need to be cognizant of that too,” she said.
That changing investment landscape is also creating opportunities beyond gold.
De said strength in currencies tied to major commodity-producing economies — including the Norwegian krone and Australian dollar, as well as the Brazilian real and Mexican peso — is another indication that commodities have an increasingly important role in global markets.
Copper is particularly well positioned within those structural trends. Traditionally viewed as a barometer of global economic activity because of its widespread industrial use, the metal is now benefiting from additional demand tied to AI infrastructure and the energy transition.
“We are in a world where commodities have a big role to play, because it's not just gold,” De said. “You have copper.”
The energy transition could provide another long-term source of commodity demand. De said the disruption in global energy markets has reinforced the connection between energy security and economic security. She noted that refined petroleum products have experienced even greater price pressures than crude oil, highlighting the risks of relying heavily on individual energy sources and vulnerable supply chains.
She said growth in electric vehicles and batteries globally suggests the green transition has actually accelerated this year, rather than stalled.
“The more diversified you are in your energy security, the better off you are,” she said, adding that the transition has “picked up pace this year.”
Ultimately, De said the investment environment is becoming less about choosing between traditional “risk-on” and “risk-off” positions and more about building portfolios capable of participating in growth while protecting against increasingly complex risks.
She noted that capital flows during the past three to six months show investors pursuing something of a barbell strategy: maintaining exposure to U.S. and global equities and the AI growth story while simultaneously buying high-quality, short- and intermediate-duration investment-grade fixed income for capital preservation and liquidity.
“We are certainly in a world where diversification is having more than its normal share of benefits,” De said. “Diversification is really paying off at this particular point in time.”
See live precious metals prices for gold, silver, platinum and palladium — in USD, CAD and 12 more currencies.
Why Is the U.S. Dollar the World's Dominant Reserve Currency?
Why Is the U.S. Dollar the World's Dominant Reserve Currency?
September 01, 2026 By Scott A. Wolla
What do you think of when you hear “U.S. dollar”? Is it the cash in your wallet, the balance in your bank account, or the price of a gallon of gas? In these and other examples, the dollar performs the basic functions of money. This is true in the U.S. and in countries around the world, whose governments, central banks, businesses, and investors use dollars to buy, sell, borrow, and lend. The dollar is integral to the financial “plumbing” of the global economy and is the world’s dominant reserve currency.
Why Is the U.S. Dollar the World's Dominant Reserve Currency?
September 01, 2026 By Scott A. Wolla
What do you think of when you hear “U.S. dollar”? Is it the cash in your wallet, the balance in your bank account, or the price of a gallon of gas? In these and other examples, the dollar performs the basic functions of money. This is true in the U.S. and in countries around the world, whose governments, central banks, businesses, and investors use dollars to buy, sell, borrow, and lend. The dollar is integral to the financial “plumbing” of the global economy and is the world’s dominant reserve currency.
What Is a Reserve Currency?
A reserve currency is a widely accepted currency that governments and central banks hold as part of their official foreign exchange reserves. These reserves ensure that a country has reliable access to foreign currency to make international payments, manage its exchange rate, and respond to financial stress.
For example, when a country, business, or individual wants to buy goods, services, or financial assets in an international transaction, the buyer must obtain the seller’s currency through the foreign exchange market. This is where currencies are bought and sold and where exchange rates are determined.
Businesses and individuals normally rely on banks and financial markets to get the foreign currency they need for international transactions. But in a financial crisis, foreign currency can become difficult for a business to obtain. This is when a country’s central bank can step in to sell dollar assets from its foreign exchange reserves.
Countries do not hold most of their dollars as stacks of paper currency. Instead, they hold dollar-denominated financial assets, especially U.S. Treasury securities, which are debt issued by the U.S. government.
When investors buy Treasury securities, they are in effect lending money to the U.S. government in exchange for repayment with interest. When investors sell or redeem Treasury securities, they get dollars in exchange, which they may use to make other dollar-denominated transactions.
These assets are considered both safe and liquid: Investors generally trust the U.S. government to repay its debts, and Treasury securities can be quickly and easily converted into cash. So, central banks are able to hold dollars in a form that preserves value and that can be accessed quickly in a financial crisis. In this way, the dollar’s roles as a reserve currency and as an international currency come together, but each role reflects a different function of money. Consider the following:
As a store of value, the dollar is held through assets such as Treasury securities, which are stable, trusted, and easily converted into cash.
As a medium of exchange, the dollar is widely accepted in international trade and finance, allowing businesses to use it to pay for imports, to settle contracts, and to conduct financial transactions across borders.
As a unit of account, the dollar is quoted in many global prices and financial contracts, giving buyers and sellers a common way to measure value.
The Bank for International Settlements reports that as of April 2025, the dollar was involved in about 89 percent of all foreign exchange trades, making clear its stability and widespread use.
Why Is the Dollar So Widely Used and Held?
Several features of the U.S. economy and its financial system help explain why governments, central banks, and investors around the world choose to hold and use dollar‑denominated assets.
First, the U.S. remains one of the world’s largest economies, accounting for about 26 percent of global GDP in 2024 (measured in current U.S. dollars). This helps make the dollar central to international trade and finance and encourages other countries to hold dollar‑denominated assets as reserves.
Second, U.S. financial markets, especially the market for U.S. Treasury securities, are large, deep, and liquid. U.S. financial markets give foreign central banks and investors access to a wide supply of dollar‑denominated assets that can be bought or sold quickly and with relative certainty, which makes the dollar easier to use and more attractive to hold.
Third, the U.S. benefits from long-standing legal, political, and financial institutions that investors generally trust. Confidence that contracts will be enforced, that markets will function, and that the U.S. government will repay its debts increases the appeal of holding dollar assets.
These factors help explain why the dollar dominates global reserve holdings.
At the end of 2025, about 57 percent of the world’s foreign exchange reserves were held in dollar‑denominated assets, compared with about 20 percent for the euro. Other currencies, such as the Japanese yen, British pound, Canadian dollar, and Chinese renminbi, are also reserve currencies, but none comes close to the dollar’s share, as shown in the figure below.
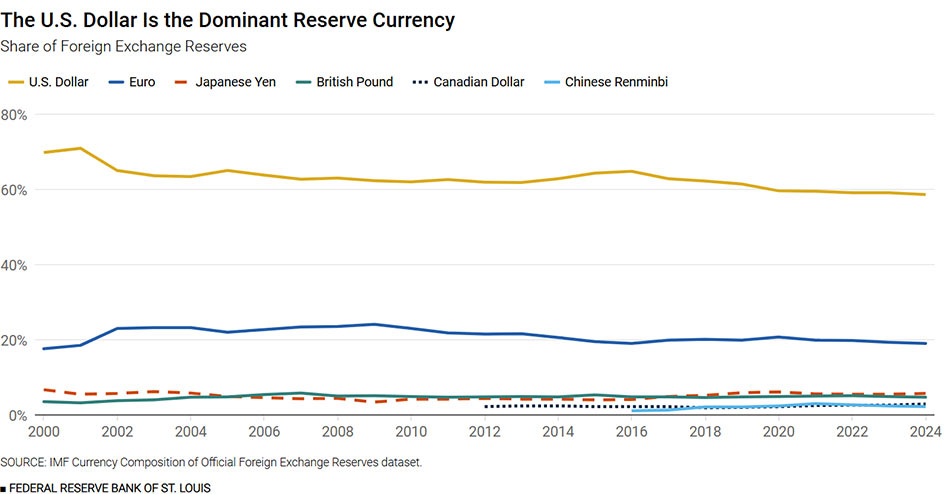
The Benefits for the U.S.
There are meaningful advantages for the U.S. in having the dollar serve as the world’s dominant reserve currency. The most important benefit is the additional global demand for dollar‑denominated assets, especially U.S. Treasury securities.
When many investors and foreign central banks want to hold Treasury securities, the U.S. government does not need to offer as high an interest rate to attract buyers, and this helps lower the government’s borrowing costs.
The dollar’s role as in international currency also supports U.S. businesses. Because the dollar is widely used in global trade and finance, U.S. firms can often borrow, invest, and write contracts in their own currency.
Doing so reduces the exchange‑rate risks they would face if they had to convert dollars into foreign currencies more frequently. This stability makes it easier for U.S. companies to participate in international markets, influencing borrowing costs, business decisions, and the broader U.S. economy.
The Tradeoffs of a Stronger Dollar
While the dollar’s global role brings important benefits, there are tradeoffs: Increased global demand for dollar‑denominated assets can make the dollar stronger than it otherwise would be, and this affects Americans in different ways, creating both winners and losers.
For consumers and businesses that import goods or services, a strong dollar is a clear advantage. When the dollar rises in value, foreign‑made products become cheaper, reducing costs for households and for firms that rely on imported goods.
For exporters, however, a strong dollar makes U.S.‑produced goods more expensive for foreign buyers and can make U.S. firms less competitive in global markets. Domestic companies that compete directly with imported goods may also face pressure if cheaper imports gain a larger share of the market.
These contrasting outcomes are an inherent part of how exchange rates work: When a currency strengthens, it becomes easier to purchase goods from other countries but harder to sell goods to them. The dollar’s role as the world’s dominant reserve currency reinforces this pattern because global demand for dollar assets tends to keep the dollar stronger than it otherwise would be.
Could the Dollar Lose Its Role?
Some countries have taken steps to reduce their reliance on the U.S. dollar, a trend often described as de‑dollarization. Their motivations vary. Some want to limit exchange‑rate risk, while others aim to avoid potential exposure to U.S. sanctions or promote greater use of their own currencies in trade and finance. Even so, replacing the dollar is challenging because the main alternatives face significant limitations.
The euro is the second‑most widely held reserve currency, but it lacks a single, unified Treasury market (PDF) comparable to the large and liquid market for U.S. Treasury securities. China’s renminbi has expanded its international presence in recent years.
Yet continued exchange rate management and capital controls limit how freely funds can move into and out of the country, creating obstacles to becoming a global reserve currency.
The dollar’s role is not fixed. Its share of global reserves can rise or fall over time depending on economic conditions, policy decisions, and investor confidence. Still, displacing the dollar entirely would be difficult.
Few currencies combine the same scale, safety, liquidity, and trusted institutions that make the dollar so widely used and held.
Conclusion
The dollar’s position as the world’s dominant reserve currency provides the U.S. with important advantages, but it also brings tradeoffs. Its global role helps lower government borrowing costs and reduces financial frictions for U.S. businesses, but it also contributes to a stronger dollar that creates challenges for exporters and domestic firms.
The dollar serves the basic functions of money in its roles as a reserve currency and an international currency, as it is both stable and widely accepted by sellers, lenders, and investors around the world.
And when you hear “U.S. dollar,” you now have a better understanding of its integral role in the global economy and why it dominates global reserve holdings.