Thank you to all the subscribers to our Early Access program…we thank you for your continued support.
We are excited to offer this new service to keep you informed and up-to-date on the latest Dinar and currency news.
The Vigilantes Are Coming For Congress
The Vigilantes Are Coming For Congress
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 30, 2026
Eight years ago in the summer of 2018, an automated monitoring system at the US government’s Social Security Agency flagged a questionable transaction and immediately forwarded it to a human worker at the agency to investigate.
It took more than a year for a Social Security employee to look into it. And it was painfully obvious— Social Security was paying too much ‘supplemental security income’ to the recipient.
In fact, the guy receiving the benefits check every month was legally obligated to report this overpayment... but he did not.
The Social Security employee then contacted the recipient to question him. No response. The employee tried a second time. No response.
Then, in the words of Social Security's inspector general, "the employee took no further action."
The government worker just shrugged and closed the case. There was no attempt to recoup the overpaid money. The recipient continued to be overpaid. No follow-up.
Today, eight years after the waste was discovered, literally nothing has happened to correct the mistake.
And that's just one case.
It comes from a report that the inspector general just released, in which he audited 100 random transactions that had been flagged by the same automated monitoring system.
Every single one of the 100 flagged transactions were all similar instances of waste or outright fraud.
Yet out of the 100 flagged transactions, Social Security employees simply ignored 63 of them. 17 were marked ‘complete’ when they were not complete. Only 20 out of the 100 were actually handled properly.
That means that Social Security failed to fix fraudulent and/or wasteful overpayments 80% of the time.
Bear in mind that, in total, the automated monitoring system has flagged over 400,000 cases of potential waste and fraud. At a similar 80% failure rate, that’s potentially billions of dollars that taxpayers are flushing down the drain.
And that’s only for Supplemental Security Income; it doesn’t count fraud and waste from the actual Social Security retirement checks. Or Medicare. Or Medicaid. Or anything else for that matter.
Everyone knows about the rampant fraud at Minnesota’s infamous ‘Learning Centers’. And fraud like that requires courageous people to put their safety at risk to document the fraud.
In this case, Social Security's own internal system flags nearly EVERY SINGLE CASE of fraud and waste. And yet the agency still did nothing 80% of the time.
So taxpayers are essentially footing the bill TWICE— once for the overpayment, and then more money to pay lazy workers who do nothing about it.
Social Security is hardly alone. Earlier this year, Vice President JD Vance said his anti-fraud task force had found 186,000 dead people collecting food stamps.
In January, the FCC's inspector general found phone companies billing Lifeline, the federal program that pays for low-income phone service, for 94,000 dead customers in California.
And by the government's own accounting, improper payments— money sent to the wrong person, in the wrong amount, or for the wrong reason— come to about $3 trillion since 2003.
None of this is secret. Yet nothing ever changes.
When the inspector general asked why Social Security employees didn't work the alerts, he said the agency bureaucrats “could not provide an explanation."
I'd say the explanation is pretty obvious. They’re either in on it, or they don’t care. Either way it should be grounds for termination.
Unfortunately it’s impossible to fire anyone who works for the federal government.
Remember when the executive branch tried mass layoffs across more than a dozen agencies last year? 20 state attorneys general sued. Judges issued injunctions. And the job cuts were tied up in court for months, with taxpayers footing the legal bills.
A private company full of workers being paid to do nothing would quickly go bankrupt. The federal government just piles on more debt to cover it, and then pretends the exploding debt is consequence-free.
Well, the bond market disagrees.
The 10-year Treasury yield has skyrocketed past 5.25%, its highest level in decades. And one of the reasons is that bond investors are tired of lending to a government that operates like this.
We’re supposed to believe that ‘democracy’ will deliver us from this, that voters will hold politicians accountable and elect a Congress that will cut the deficit. I’m not holding my breath.
Given the astonishing rise in yields, it looks like the bond market is going to hold Congress accountable. As yields continue to rise, borrowing will eventually become so expensive that Congress will be forced to cut spending.
Maybe that happens when government bond yields hit 6%. Maybe 8%. Maybe 10%. Nobody knows for sure. But there is an interest rate that will be so high, Congress will be forced to take action and cut spending.
When those cuts do finally come, they'll be far more painful than what it would take to fix this now.
Seriously, cutting the deficit today should be simple: fire the people who ignore the alerts. Stop the fraud the government already knows about. It should be pretty easy.
But at the moment, no one seems interested in any meaningful cuts... which means the bond market will keep pushing yields up.
In finance, whenever bond investors get tired of loaning money to governments and push yields higher, they’re known as ‘vigilantes’. In this case, vigilante justice for Congress can’t come fast enough.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S. When the bond market finally forces the issue, spending cuts will only be part of the answer.
A government that can't borrow cheaply prints the difference, and that inflation comes straight out of your paycheck and your retirement account.
That's what a Plan B is for. Our flagship service, Plan B Confidential, is built for exactly this.
It covers everything from real assets that hold their value when the dollar doesn't, to foreign residency and second citizenships, offshore banking, and legal ways to cut your tax bill, all backed by boots-on-the-ground research from countries around the world.
Canada's Plan To Balance The Budget: Change The Definition Of ‘Spending’
Canada's Plan To Balance The Budget: Change The Definition Of ‘Spending’
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 2, 2026
It was a big week for creative problem-solving. Britain fixed a failed government energy company by starting a second, Canada is balancing its budget by renaming the spending, and Boston paid $335,000 to call itself racist and failed. Here are a few of the most absurd stories in case you missed them.
Britain fixes its failed government energy company with a second one
Before the 2024 election, Britain's Labour Party promised that a new state-owned company called Great British Energy would help families save up to £300 a year on their energy bills.
So far electric bills have increased instead.
Not to worry. On Tuesday, Prime Minister Andy Burnham announced his fix: create a SECOND state-owned energy company to basically do the same job as the first.
After all, when one state-owned enterprise fails miserably, the only logical solution is to create a second state-owned enterprise and expect a different result.
Canada's plan to balance the budget: change the definition of ‘spending’
We've long said that when the deficit and inflation numbers become bad enough, politicians will simply reinvent the way they calculate these figures.
Canada has now done just that.
Prime Minister Mark Carney has promised to balance Canada’s gruesome budget deficit. But his plan is to change the definition of the word ‘spending’.
Carney’s big idea is to only count day-to-day operating costs as ‘spending’. And anything else that he deems to be an ‘investment’ won’t count.
We all understand the difference. In your own household, the electric bill is considered an expense. Purchasing shares of Newmont Mining is considered an investment.
Now, my wife has tried to stretch this definition a time or two by insisting that a beach vacation or pretty necklace is actually an investment.
Carney is applying this same logic to an entire national economy. It’s completely subjective and inconsistent, plus it lacks any transparency.
Giving money away on woke priorities? Not an expense! It’s an investment in community! Paying Canadians to turn in their completely legal firearms? Not an expense! It’s an investment in safety! (more on this below)
Carney has now reinvented the math, making Canada look just as ridiculous as WeWork when then CEO Adam Neumanm spoke of his company’s “Community-Adjusted Earnings”.
Canada's last line of defense is the gun owners it's disarming
Mark Carney isn’t done with his insanity. He recently told the New York Times that it's his job to look at the "extreme tail risk" that Donald Trump orders military action against Canada.
According to Carney himself, in the absurd likelihood of a US invasion, US forces would overrun Canada's defenses within a week, possibly within two days. After that, Carney will be counting on "small groups of irregular military or armed civilians" to fight on with ambushes and sabotage, like the Afghan mujahedeen against the Soviets.
The trouble is that Canada has banned more than 2,500 makes and models of "assault-style" firearms since 2020, and the government is paying gun owners to hand them in.
So apparently Canadians are expected to fight house to house with hockey sticks... until the government comes for those too.
Boston paid $335,000 to call itself racist... and failed
If any place in America can say it made the right call on slavery early in its history, it's Massachusetts. The state's chief justice declared slavery finished in 1783; he cited the state constitution that "all men are born free and equal."
Yet the city government in Boston has still chosen to put itself on trial more than two centuries later.
In 2022 local politicians set up a task force to study reparations for slavery, with one member positively giddy that the research would give it the "evidentiary pool from which to argue for [reparations]."
So the city spent $335,000 of taxpayer money to hire a Tufts University team led by historian Kerri Greenidge.
She came with all the right awards. Her 2022 book The Grimkes, about a slaveholding family that produced two famous abolitionist sisters, had been a finalist for the National Book Critics Circle Award and won a prize from the American Historical Association.
Apparently if you write about slavery, no one bothers to check whether it's accurate. They just give you awards.
But it turns out Greenidge’s book was "riddled with factual errors." It cites letters held at the University of Michigan which don’t actually exist. It references other historians’ research that doesn’t exist. In short, it’s about as accurate as a Hollywood adaptation.
Ms. Greenidge naturally clapped back and claimed that pointing out her errors is an "attack on Black women [in] academics..."
So, Boston was willing to spend taxpayer money to call its own taxpayers racists, and the expert they hired turned out to be another race grifter with no credibility.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
The UN’s Bankruptcy Can’t Happen Fast Enough
The UN’s Bankruptcy Can’t Happen Fast Enough
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 28, 2026
Every September, world leaders take turns at the podium of the United Nations General Assembly in New York and give pointless speeches. If they really cared about CO2 emissions, they’d skip the event entirely, because the only thing coming out of their mouths is lies and hot air. But a few days ago when it was Argentina's turn, President Javier Milei spoke honestly and boldly.
He told the auditorium the UN "has become a useless organization whose only purpose is to sustain a caste of fatally arrogant parasites masquerading as well-intentioned bureaucrats."
He then piled on a heap of charges to prove his point.
Milei e said the UN "allowed chaos, violence and international terrorism to flourish," and that it had "sheltered bloodthirsty dictatorships and regimes that stone women in the streets."
Of course, this type of hypocrisy is nothing new for the UN.
We're talking about a body that has appointed China, Cuba, and Venezuela to their Human Rights Council.
Then Milei turned to the pandemic. He said UN agencies pushed lockdowns that were "a global experiment in social control disguised as science," which he said is why Argentina quit the World Health Organization.
"There's no shortage of words or resolutions. What is lacking is consequences."
He's right, and the proof is the people in that very room who run the place.
The United Nations, along with other ‘supranational’ bodies like the EU and NATO, has become a sort of retirement home for failed politicians who destroyed their own countries with terrible ideas and worse execution.
In June 2024, after running his country into the ground, Belgian prime minister Alexander De Croo came out of a national election with barely 5% of the vote.
He resigned that night and left behind a deficit so large that the EU opened disciplinary proceedings against Belgium.
Yet while Belgian voters threw him out for being incompetent, the United Nations made de Croo the head of its its development agency (UNDP) with a $5 billion annual budget to advise poor countries on how to manage their finances.
It's the same job the UN gave to former New Zealand prime minister Helen Clark in 2009, a few months after voters threw her out.
Then theres António Guterres, former Portuguese prime minister who was thrown out of elected office by the voters. The UN then elevated Guterres to the unelected office of running its refugee agency. And he later became Secretary General in 2017.
Speaking of former Portuguese politicians, António Costa resigned as prime minister of Portugal in November 2023, hours after police arrested his chief of staff in a corruption investigation.
Police found more than €75,000 in cash inside the prime minister's official residence, stuffed in envelopes hidden between books and in champagne crates.
Prosecutors put Costa himself under investigation, after which EU leaders decided he was fit to be President of the European Council, the group of the EU's 27 national leaders that sets the bloc's direction.
Former British prime minister Gordon Brown was thrown out of office by his voters in 2010. The UN subsequently invented a brand-new title for him: "Special Envoy for Global Education."
And another ex-prime minister who was ousted from office, the ridiculously unpopular and failed Keir Starmer, is reportedly waiting in the wings for his fancy (and unelected) EU/UN post. Rumor has it that he wants to be the next secretary general of NATO… or even of the UN.
This is the pattern that Argentina’s president has correctly identified: incompetent politicians who couldn't manage their own countries are often put in charge of global organizations.
Unsurprisingly, the UN's track record looks exactly like you'd expect.
Last year the world had more armed conflicts than in any year since it was founded in 1945; ironically, the UN was founded "to save succeeding generations from the scourge of war." Great work!
The UN passed nine rounds of sanctions to stop North Korea's nuclear program. North Korea carried out six nuclear tests anyway.
UN peacekeepers have spent 20 years trying to keep Hezbollah's weapons out of southern Lebanon. Hezbollah armed itself anyway.
In 2015, it promised to end extreme poverty by 2030. Poverty is still everywhere.
The UN is also a gigantic financial failure. All of these ex-politicians rake in pretty serious salaries, in addition to massive benefits ranging from security details to tax-free earnings. It literally pays to be a failed politician.
Partly as a result of such lavish spending, the UN is now in serious financial straits...
In January, the UN's secretary-general even warned of the organization's "imminent financial collapse" and "race to bankruptcy".
The same guys who want to tell developing nations how to manage their finances can't manage to stay afloat themselves.
The biggest irony is that these are the same politicians that their respective democratic nations already threw out. Yet now they've all been elevated to jobs where they can't be fired, don't answer to voters, and were never elected by anyone.
Milei was right: what is lacking is consequences.
The only real consequence the UN may ever face is bankruptcy… and that can't come fast enough.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
Xi Xinping Said America Is Finished. Congress, Take The Hint!
Xi Xinping Said America Is Finished. Congress, Take The Hint!
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 25, 2026
Chinese President Xi Jinping landed at Joint Base Andrews Wednesday for a three-day state visit, and Donald Trump was waiting for him at the foot of the red carpet. That’s highly unusual. US presidents typically receive foreign leaders at the White House.
In fact, with the exception of popes, no president had met a foreign leader on the tarmac since 1962, when JFK went out to greet British Prime Minister Harold Macmillan.
Judging by the media’s reaction, however, you would think Trump bent the knee and swore fealty to his communist overlords.
There was a short clip of US troops on their hands and knees, smoothing the carpet before Xi stepped out of the plane. It went viral. Chinese were gleeful, and Americans were disgusted, at what appeared to be a humiliation ritual... even though smoothing out the red carpet is pretty standard.
The over-analysis continued. When B-1 bombers passed overhead— Trump flinched and Xi didn't move a muscle— the Twitterverse exploded with commentary about what that means for American primacy.
Then there were hot takes on Xi’s every smile, every Trump fidget. Commentators claimed that Xi speaking Mandarin through his translator was ‘asserting language dominance’ over Trump.
It’s all ridiculous. I honestly don’t remember an event where so much irrelevant minutia was over-analyzed for hidden meaning.
The larger point is that the US is clearly treating China like an equal— something that America does not do for anyone else. When the President of France, or Ukraine, or anywhere else comes to town, the President receives them at the White House.
China, on the other hand, is now a peer... not a superior. But definitely not a junior partner.
The biggest takeaway, though, seems to be lost on everyone... but hit me right between the eyes.
At a formal White House ceremony the next morning, Xi declared that "the Thucydides Trap can be overcome. . ."
The Thucydides Trap, of course refers to the famous ancient Greek historian who wrote of the Peloponnesian Wars between Athens and Sparta. Athens was a declining power and Sparta was the rising power; and the theory asserts that rising and declining powers often go to war against one another.
World War I was an obvious example of the Thucydides Trap. Britain was in decline. Germany was rising fast. War became inevitable.
When Xi made this assertion, most of the media coverage treated his remarks as a wonderful message of peace and reassurance.
BUT NO ONE BOTHERED TO QUESTION HIS PREMISE, i.e. that America is permanently in decline and will be surpassed by China.
Xi obviously likes this analogy because he views China as the rising power... eventually the world’s superpower... and the US as the declining power.
What he essentially said was: America is finished, we're going to pass you... and while that historically has led to war, I’m going to be super magnanimous and claim that I prefer peace.
Talk about being presumptuous. This guy comes to America’s house and tells everyone that he’s going to dominate?!?
Obviously he believes this— he's the one who has been steering China for 14 years.
And yes, America is in decline. Between the $40 trillion in debt, Social Security running dry in a few years, foreign central banks dumping dollars for gold, and a Congress too dysfunctional to fix any of it, that much is indisputable.
But America is not in PERMANENT decline.
The problems that the US faces can be fixed with some rational thinking and a few hundred signatures: cutting fraud and waste. Immigration reform. Social Security reform. Regulatory reform to boost productivity growth.
None of this is difficult. But Congress can't seem to muster the will to make it happen, and voters keep sending the same corrupt idiots to office.
But if you think America has a debt problem, China has even worse debt challenges. Plus their entire economy is run by communist bureaucrats and businesses who ‘innovate’ by stealing other people’s intellectual property.
And that doesn’t even scratch the surface of their biggest challenges.
America needs some sensible politicians to fix its problems. China needs a time machine.
They’d have to go back in time to reverse their one-child policy... or undo decades of communism that created a business culture where screwing up means getting shipped off to a ‘reeducation’ facility.
Say the wrong thing and you get disappeared like Jack Ma, who was the richest man in China until he criticized the regulators in 2020, then vanished for three months, and now gets rolled out for the occasional proof of life.
There's a reason why wealthy Chinese people leave the country. People who have the means hit the exits.
And, seriously, eight decades later, these guys are still whining about Taiwanese independence. Get over it already!
Undoing all of that requires a complete cultural reset.
So when he boasts about becoming the next dominant superpower, Xi is way over his skis.
America has a regulatory problem. China is literally communist. Nothing happens there without the Party's permission, and it has to steal every idea it can't come up with itself.
Yes, China has had a good run for the past ~20 years. America’s has been miserable. But past performance is no indication of future returns.
If anything, Xi’s remarks should shame Congress into finally lifting a finger to do the right thing and pass sensible reform.
And you'd think more of the pathetic press would have the dignity to call that out as well.
Unfortunately, Congress and the media tend to attract the worst people on earth, so don't hold your breath waiting for either one to find a spine.
Time will tell if America can reverse course... and if China can live up to Xi’s fantasy. But that's why it makes sense to have a Plan B.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
America Keeps Threatening the Lenders It Can't Afford to Lose
America Keeps Threatening the Lenders It Can't Afford to Lose
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 24, 2026
Late last week, Congress and the White House established a new law authorizing the President to impose tariffs of up to 100% on any country that ranks among the five biggest buyers of Russian oil or gas.
This law had broad, bi-partisan support and passed by a whopping 86-11 margin in the otherwise deadlocked Senate, and 262-159 in the House of Representatives.
Their big idea is to penalize anyone who supports Russia economically by buying their oil & gas, and that specifically singles out China and India— the biggest buyers of Russian crude.
In fairness, India and China aren’t buying Russian oil to help prop up Putin or assist him in winning the war. They don’t really care. They just like the fact that Russian oil is REALLY cheap right now. It’s a good deal, and they like scoring good deals for their country.
At the moment there is no international law preventing anyone from buying Russian oil & gas; this restriction is something the US wants to impose in order to force Russia into a peace over Ukraine.
And it may very well be a good idea in terms of bringing an end to the war in Ukraine. We make no judgment on the moral implications.
Unfortunately the world is not so black and white, especially when you have a $40 trillion national debt. When your fiscal situation is in such dire straits, you have to weight the pro’s and con’s.
And the con’s are numerous: given its gargantuan national debt and the need to borrow an ADDITIONAL $2 trillion per year just to finance the budget deficit and stay afloat, the US government has to rely on foreign creditors more than ever.
In short, America desperately needs cash-rich foreigners to continue buying US government bonds.
It’s a bit difficult to shove this rule down their throats and tell foreign countries, “We will force you to stop buying cheap Russian oil,” yet simultaneously ask those same countries to loan you hundreds of billions of dollars.
The strangest part is that this is nothing new.
Back in February 2022, days after Russia invaded Ukraine, the US and its allies froze about $300 billion of the Russian central bank's reserves.
Again, whether it was justified is beyond the point. US government bonds had long been considered the safest asset on earth. But every central banker on the planet learned that day that US Treasury bonds were only safe as long as their country stayed on America's good side.
That’s why foreign governments and central banks have been quietly diversifying away from US government bonds and buying gold... because no other government can freeze the physical gold in their own vaults.
In fact, for the first time in decades, the world's central banks now hold more gold than they hold US Treasury securities.
China in particular has cut its Treasury holdings in half since 2013, and they're now at their lowest level since 2008.
Japan, the biggest foreign lender of all, has seen its Treasury holdings fall every month since April.
At peak (in 2011), foreigners owned nearly half of all marketable US Treasury bonds. Now foreigners’ share of Treasury securities is down to just over 30%.
That’s a fairly slow burn over 15 years; it’s not panic selling. But it’s a clear and obvious trend.
These same foreign nations have also been openly discussing how to rely less on the US financial system.
The BRICS countries, led by China, India, Russia, and Brazil, met in Delhi earlier this month and agreed to settle more of their trade in their own currencies.
This is a big deal; if India starts accepting Chinese yuan, or Russia accepts Indian rupee, these nations by definition won’t need to hold as many US dollars. And a decline in demand for US dollars translates into less demand to hold dollar-denominated assets like US government bonds.
Xi Jinping arrived at the White House yesterday, and he came to negotiate on trade as the leader of one of America's three largest creditors.
China has serious leverage; even though they have been selling their Treasury bonds slowly over time, they still own a ton of them. And if Xi wanted to, he could dump them in a heartbeat and cause a complete collapse of the bond market. Interest rates would skyrocket.
To be clear, such a move would wound China as well. But America would be hurt the most. It’s a nuclear option he could exercise, and it gives him real negotiating power.
America seems to think it’s still the 1990s when everyone was begging to buy US government bonds... which is exactly what gave them the leverage to be able to weaponize the US dollar.
That is simply no longer the world we live in. US finances are incredibly weak. And every time America tries to flex its US dollar power over the financial system, more foreign lenders walk away.
It’s not clear to me if anyone in Washington even understands this reality. No one seems to be questioning, “Will this action increase or decrease foreigners’ demand to buy US dollars and US government bonds?”
And I doubt anyone is really doing any real analysis to weight the benefits of, say, peace in Ukraine, against the potential costs of losing more foreign lenders.
By the way, if you’re thinking, “Big deal, America can finance its own deficits,” it cannot.
The entirety of ALL net private savings in the US, i.e. the total amount that corporations and households manage to save, is only about $2.2 trillion each year. The budget deficit for FY2026 is projected to be about $2.1 trillion.
So basically the US economy would need to dump 95% of its total net savings into US government bonds, leaving just $100 billion to finance EVERYTHING ELSE in the economy, from data centers to mortgages to every other investment.
This is why the US needs foreigners so much. When you burn up that much money, you can’t afford to turn away any lender.
If they keep alienating foreigners, there will essentially be only one lender remaining— and that’s the Federal Reserve, which has the ability to create money out of thin air.
We all saw how that works during the pandemic, when the Fed created roughly $5 trillion to finance all of the debt-fueled government bailouts. The result of that money creation was 9% inflation.
This is why we continue to write that real assets make so much sense.
The Fed can create money by the trillion, and the government can borrow to oblivion. Neither can print an ounce of gold or a barrel of oil. And that’s why real assets tend to hold their value, and often climb, exactly when paper money is falling apart.
Owning a piece of the companies that produce real assets— metals, energy, productive technology— is a great way to protect yourself from higher prices and inflation.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S. Since 2022, Schiff Sovereign's investment research service, Strategic Assets, has focused on exactly those companies: the metals, energy, food, and ships an economy actually runs on.
A company gets featured only when it is already profitable, carries little or no debt, and trades cheap against the cash it is generating. Two precious metals producers on our research list are up more than 300% and nearly 400%, and earlier this year we locked in gains of more than 10x on a small silver producer.
Right now we are giving away a free sample issue so you can see what's inside.
"Chuck The Debt In The Fire" Is Officially A Real Solution
"Chuck The Debt In The Fire" Is Officially A Real Solution
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 9, 2026
It's so simple, how could no one have thought of this before? The man currently polling in second place to become the next President of France has put forward an ingenious solution to tackling France's national debt, currently standing at around 117% of the country's GDP.
Jean-Luc Mélenchon says, "All we have to do is take the 18% held by the Bank of France and chuck it in the fire."
This is the guy who has a real shot at running the second-largest economy in the eurozone, and he's telling voters that roughly €636 billion of what their government owes can simply be erased.
And the voters like the sound of it. Of course they do, who doesn’t love getting something for nothing?
Quick economics lesson for the brilliant man who wants to lead France: the Bank of France bought those bonds with euros it created for the purpose… the European Central Bank's own explainer says buying bonds "creates money in the banking system."
Normally those euros come back out of circulation as the debt gets repaid. Mélenchon's plan skips that part: the government ‘throws the debt in the fire’ and doesn’t pay it back. So the central bank eats the loss... meaning that the €636 billion conjured out of nothing stays in the system.
This creates inflation, plain and simple.
Goods and services cannot be created out of nothing. Euros can. So when there’s suddenly more money in the system relative to the same amount of goods and services, the end result is inflation.
The other obvious implications is that France would still owe the rest of its debt... and those lenders will have seen that France is willing to default. I wonder what that would do to French bond yields?
Or maybe they’ll rest easy with Mélenchon’s assurance that “I’m not going after private creditors, not at this step in any case.”
Why do French voters even care about the national debt? Because they’ve been feeling the consequences of idiotic fiscal policy for years.
Interest alone costs the French government more than its entire defense budget. There's no taxing their way out, either: the French are already the second-most-taxed people in the developed world, at about 44% of GDP.
So every fix takes some benefit away from taxpayers. Last year's plan canceled two public holidays, froze pensions, and cut civil-service jobs... and the prime minister who proposed the solutions was thrown out.
The plan before that raised the retirement age from 62 to 64 brought the biggest protests France had seen in decades; that plan has now been suspended to keep the current government alive.
Meanwhile, growth was less than 1% last year, and unemployment is at its highest since 2020.
And here comes Mélenchon with a plan that costs nobody anything: delete a portion of the debt and go back to spending as if everything is OK.
However dumb the solution, at least the French are talking about the problem.
The US government crossed $40 trillion in debt last month. That's roughly 123% of GDP, worse than France.
America gets away with it, for now, because the dollar is still the world's reserve currency. Central banks hold a lot of their strategic financial reserves in US Treasury bonds, so Congress has always had a line of foreigners waiting to lend it money no matter how large the deficit.
But that line of foreigners is now getting shorter. Foreign holdings of Treasuries fell by $72 billion in June alone, China's are at their lowest since 2008, and so far this year foreigners have bought just 7% of the new debt the US government issued.
The reasons aren't a mystery: a dysfunctional government that can’t even pass a budget or eliminate fraud from its spending, while increasingly weaponizing access to the US dollar system.
When the foreign buyers stop showing up, America finds itself with France's problem. Automatic cuts to Social Security are only six years away. Interest on the debt is already larger than the defense budget.
Extreme government spending is already pushing inflation higher... and socialists are everywhere now promising to spend even more.
These people genuinely believe that money is something you can conjure out of thin air with no consequence.
But whether they cancel the debt, or simply continue to ignore it, the consequence ultimately comes back to inflation.
That’s because conjuring money out of thin air, or borrowing from future generations to spend today, doesn't produce one more barrel of oil, one more bushel of wheat, or one more pound of copper. It just produces more euros and dollars.
America has been here before.
Through the 1970s the US government ran deficits for Vietnam AND a historic expansion of welfare spending... then cut the dollar's last link to gold in 1971. They created new money to cover the difference.
Consumer prices doubled over the decade, and the Dow finished 1979 where it started 1970, which after inflation was a loss of about half in real terms.
Meanwhile, gold went from $35 an ounce to $850. And oil went from about $3.40 a barrel to nearly $30. The world’s most important (and scarce) resources not only held their value, but they dominated. And the companies that produced them did far better.
Over roughly the same stretch, Barron's index of gold mining stocks rose more than 1,200% while the S&P 500 managed 43%.
The new money has to go somewhere, and it flows into whatever the government cannot create more of.
Today, a lot of the companies that produce those real assets like metals, energy, food, and the ships that carry them, are still cheap.
We find them for subscribers of our investment research newsletter, Strategic Assets.
Gold and silver moved first, as central banks started diversifying out of the dollar. A small silver producer we featured in April 2025 rose more than 10x in ten months. A gold producer has gone up 5x, yet it's earning money so fast that the stock is cheaper against its earnings today than the day we wrote it up. It pays a dividend, too.
Now the rest is showing life. A zinc producer we featured is up more than 150% in under a year. A tin miner is up more than 230% and trading at all-time highs. Two oil tanker owners we bought when nobody wanted them are up more than 150% and 110%, and one just reported the best quarter in its history.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
Sometimes This Time Really Is Different
Sometimes This Time Really Is Different
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 21, 2026
Some time in the middle of the second century AD, on the shores of the extremely picturesque Lake Iznik in modern-day Turkey at the site of the ancient city of Nicaea, a boy named Cassius Dio was born into a locally prominent family. His father was a Roman politician, his mother was Greek, and young Cassius Dio grew up in a bilingual household speaking Greek and Latin at a time when the Roman Empire was at its absolute peak.
pic
There was widespread peace and prosperity— so much so that the emperor at the time, Antoninus Pius, spent his entire 20+ year reign without ever coming within 500 miles of a Roman legion.
His was the most peaceful reign the empire ever had. The imperial government busied itself with foreign trade missions, including to Han China; and with perfecting the delivery of clean drinking water across the empire— a feat that wouldn't be repeated until 1804.
In short, the Romans had a 19th century standard of living as far back as the 2nd century AD, and this is the environment of wealth and abundance in which young Cassius Dio grew up.
But by the time he was an adult and had followed in his father's footsteps to become a politician, things had changed.
In the decades between his childhood and adulthood, Rome had taken a turn for the worse. The empire had seen multiple wars, plague, barbarian incursions, and assassinations of several emperors.
At one point the Praetorian Guard had even auctioned off the empire to the highest bidder.
But Cassius Dio knew his history, and he knew that Rome had seen tough times before. There had been the civil war between Julius Caesar and Pompey, the depravity of Caligula, and the insanity of Nero. Yet Rome always came back better and stronger than ever.
So Cassius Dio assumed at first that this time would be no different. Rome was in the midst of difficult times by the 190s and early 200s, but it would recover stronger than ever, just as it had in the past.
It was only later in life, after watching things go from bad to worse that he realized this time actually was different. Rome was not coming back.
And it was at this point that he wrote, rather bitterly in his histories of the empire, "Our history now descends from a kingdom of gold to one of iron and rust."
This is how we opened our Plan B conference this past weekend in Panama City, Panama— with a historical tale. We told the story of Cassius Dio and explained that, yes, dominant superpowers often go through tough times, and they often recover.
France under Louis XIV went through multiple peasant rebellions and a civil war, yet it recovered and maintained its status as a superpower.
The US went through World Wars and financial crises, and also maintained its status as the dominant superpower.
But sometimes superpowers reach a point where this time really is different. Nothing is certain, and recovery is still possible. But it makes perfect sense to prepare for challenging times ahead.
If the US dollar, for example, loses its status as the global reserve currency, there will absolutely be consequences, and the impact will be widely felt. Ditto for the rising US national debt.
The rest of our event focused ways to mitigate those consequences.
We had attendees and speakers from all over the world, which was quite refreshing. We even had the mayor of Panama City open the event, welcoming our guests at dinner on Thursday night, and come again to our farewell dinner on Saturday night.
It was really nice to see someone of influence in government who was bending over backwards to support anything and everything that our members needed.
My friend and partner Peter Schiff was also on stage with me, and he told the audience where he sees serious cracks in the bond market. This has major implications for the US dollar, the prospect for inflation, and the general future of the United States.
Peter and I both agree that not all is lost. I presented some very simple ideas for the US to get back on track, none of which are remotely controversial.
Bottom line, with the prospect of continued productivity growth from AI, robotics, small modular nuclear reactors, and cheap energy, combined with some modicum of fiscal responsibility, the US can still be OK.
But, at least at the moment, there does not seem to be any interest in Congress to rein in spending and stop the explosion of the national debt.
And this is why having a Plan B is so important. It would be completely foolish to believe that a $40 trillion national debt, the looming insolvency of Social Security, $2 trillion annual deficits, and an annual interest bill that mops up 25% of tax revenue will all be consequence-free.
That's why we presented so many options from around the world. We had speakers presenting about second citizenship programs, foreign residency, global real estate, tax planning, multiple options for gold storage, as well as some discussion about tokenization and crypto.
We even had bankers from a well-capitalized private bank opening accounts for people on the spot.
This is important stuff. A good Plan B is like an insurance policy— you don't wait until your house burns down, you get sensible coverage in advance to mitigate specific risks.
The whole point of a Plan B is to be in a position of strength regardless of what happens, or doesn't happen, next. It’s not complicated, but it takes some sensible and deliberate planning.
For more than 15 years we've been providing some of the best research in the world on these topics.
Every month it covers second citizenships, foreign residency, foreign banking, and legal tax strategies, with boots-on-the-ground reports from more than 120 countries and a Rolodex of vetted service providers for when you decide to take action.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
Doing The Math: Interest Expense Is Going To $2 Trillion Annually
Doing The Math: Interest Expense Is Going To $2 Trillion Annually
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 17, 2026
It was January 2000. AOL had just announced it was buying Time Warner in what was then the biggest merger in history. Fourteen dot-com companies had bought Super Bowl ads, one of them starring a sock puppet that sold dog food. The US economy was growing at one of its fastest paces ever; GDP was up nearly 5% the year before— and that’s real growth, before adding inflation, which itself was just 1.4%.
Pic
Unemployment was 4%, the lowest in thirty years. And there was no other country on the planet that could come close to rivaling America's dominance.
Best of all, the federal government was running a surplus… a real one. It was so strong that, even excluding the Social Security surplus, the government took in $86 billion more than it spent.
So the Treasury didn't need to borrow any money. Naturally it still held bond auctions, because when you issue the global reserve currency, you have to give investors a safe place to park their money. But Treasury was retiring more debt than it issued, and even started buying its own bonds back early.
And after wondering what “the meaning of the word is is”, Bill Clinton bragged that the country was "on track to pay down nearly $300 billion in debt” by the end of the year.
And in the middle of all that, the 10-year Treasury yield hit 6.79%.
In other words, investors wanted a 6.79% annual return to hold extremely safe US government bonds… at a moment when America was on top of the world and the government's finances were in their best shape in decades.
That interest rate was not a crisis. After all, the government didn’t have to borrow to keep the lights on or the military funded or Social Security solvent. So they didn’t really care.
The Treasury's interest bill was shrinking as a share of tax revenue every single year.
Imagine that.
Fast forward to earlier this week, and after a hot inflation report and with oil back above $100, the same 10-year yield briefly crossed 5%.
The reaction was instant panic.
Imagine being able to go back in time for a moment... back to January 2000. Imagine talking to an economist back then. You explain that you’re from the future, and that in 2026, the national debt is $40 trillion and growing faster than the economy. The foreign central banks that used to buy America's debt are dumping Treasuries and buying gold instead.
You explain that there are wars in Ukraine and Iran, socialism is creeping back into American politics, and Congress can barely function.
You then ask the economist from January 2000 to guess where they think the 10-year yield would be, given all of that bad news.
They'd probably guess 10%, maybe 12%, and they'd be amazed to hear it only just crossed 5%.
So why did it take so long?
Because after the 2008 financial crisis, the Fed cut rates to zero... and left them there for seven years. There were a few ceremonial hikes, but when COVID arrived, the Fed slashed rates right back to zero.
It was able to do this because the Fed conjured trillions of dollars out of thin air... and used that money to buy bonds and suppress yields.
The 10-year was so low, in fact, that the federal government could issue those notes at less than 0.5%.
For thirteen years money was essentially free, and an entire generation came to believe that was normal. It wasn't, and that era is clearly over.
Think about what an opportunity that was: when you can borrow at 0.5%, $2 trillion in debt costs just $10 billion a year. Investing that money at even a measly 1% means the government would be making money on its debt.
A 1% hurdle rate is not particularly high. But Congress couldn’t manage even that much.
Despite racking up tens of trillions in debt, there's realistically nothing to show for all of that money: the national debt has quadrupled since the financial crisis, while the economy has only doubled.
Now, each year, much of the national debt matures, and the Treasury doesn't have the money to pay it back. So they have to issue new debt to repay the old debt.
Problem is, the new debt is issued at much higher rates. They were paying 0.5% on the old debt. The new yield of 5% is TEN times the interest on the same amount of debt.
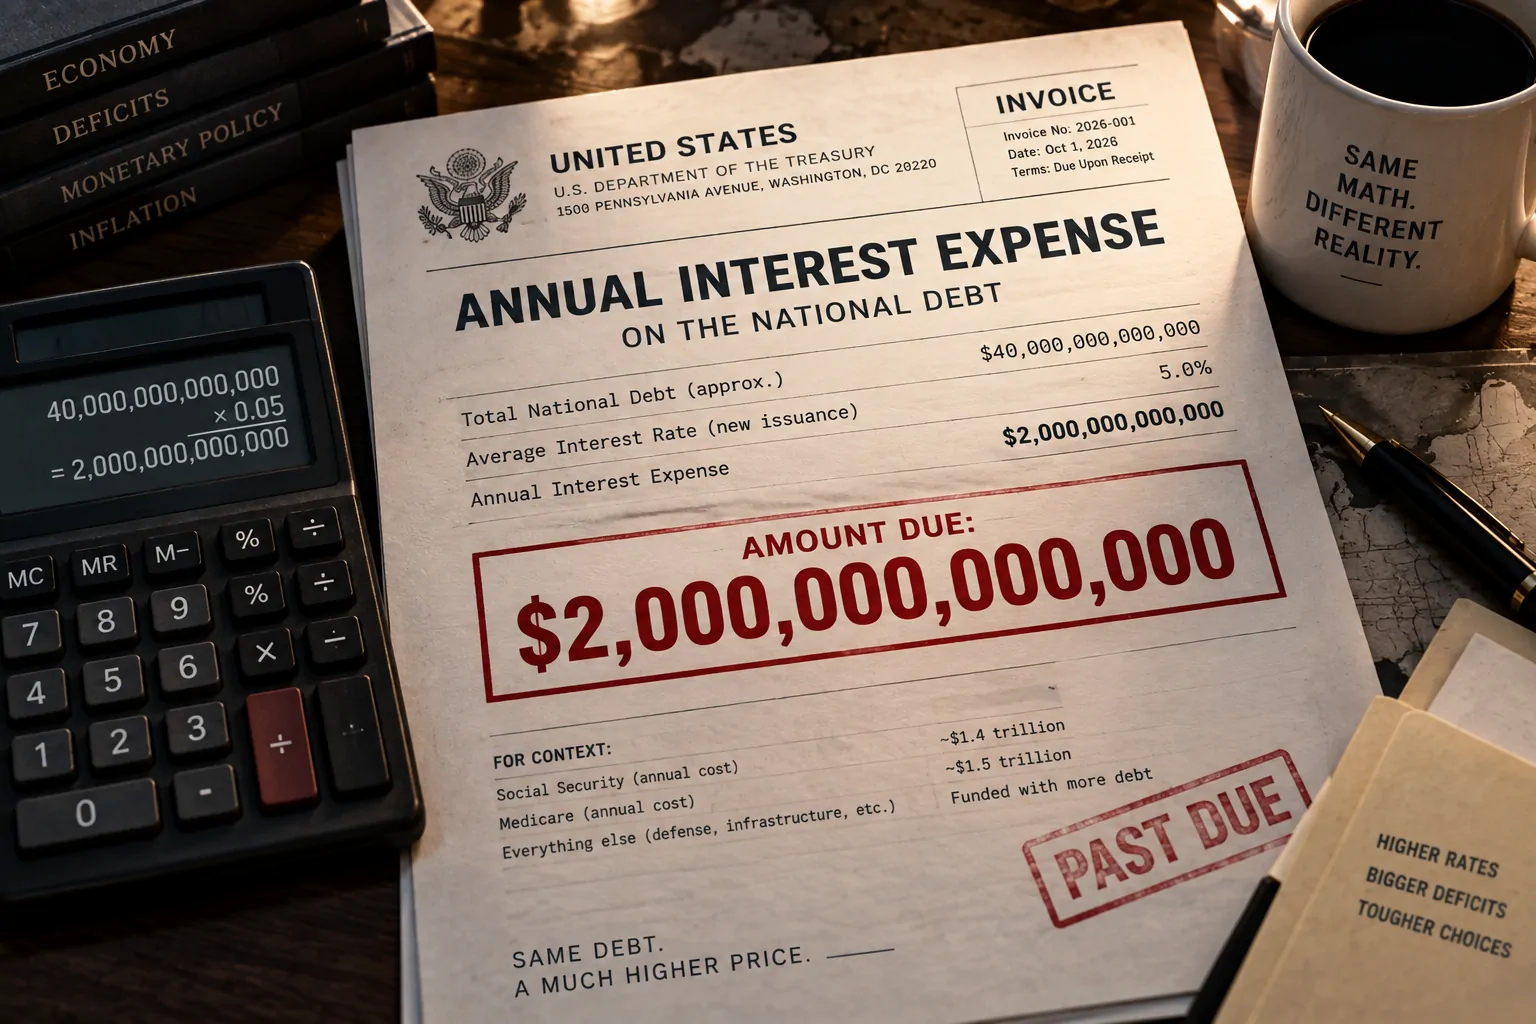
And with an average maturity of about six years, most of the $40 trillion rolls over within just a few years... which means before long the annual interest bill will reach $2 trillion per year.
Add nearly $3 trillion for Social Security and Medicare, and that’s the vast majority of tax revenue.
Literally everything else, including the military, roads, and light bill at the White House, is funded with more debt.
In 2000, the government could shrug at a 6.79% yield because it was paying debt down. Today everyone's panicking at 5% because Congress borrows $2 trillion a year and can't stop.
So, is Congress going to suddenly find its inner fiscal discipline?
I'm not holding my breath.
That leaves exactly one way to get the 10-year back down, and it's the same way the Fed did it back in 2020: conjure more money out of thin air and make capital infinite.
And as the world discovered shortly after in 2021 and 2022, the consequence of that policy is inflation.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S. In 2000, a 6.79% Treasury with 1.4% inflation was a fantastic deal. Today's 5% Treasury with the inflation that's coming is a losing one.
Real assets are where you come out ahead: gold, energy, and industrial metals rise when the dollar falls. The profitable, debt-free companies that produce them are what we research in Schiff Sovereign's Strategic Assets.
They Called Refining a Dying Business. Diesel Just Hit $6.
They Called Refining a Dying Business. Diesel Just Hit $6.
Notes From the Field By James Hickman 9Simon Black / Sovereign Man) September 16, 2026
On Sunday afternoon, the power went out at ExxonMobil's refinery in Channahon, Illinois, a southwest suburb of Chicago. Oil refineries run at tremendous heat and pressure, so whenever the power goes out, all that heat and pressure has to go somewhere. It’s basic physics. Hence why the plant burned it off through the flare stacks, with black smoke visible for miles.
They Called Refining a Dying Business. Diesel Just Hit $6.
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 16, 2026
On Sunday afternoon, the power went out at ExxonMobil's refinery in Channahon, Illinois, a southwest suburb of Chicago. Oil refineries run at tremendous heat and pressure, so whenever the power goes out, all that heat and pressure has to go somewhere. It’s basic physics. Hence why the plant burned it off through the flare stacks, with black smoke visible for miles.
The power came back around 7 p.m., but the plant stayed down, and as of Monday ExxonMobil still hadn't said when it would restart, likely up to a week.
Bear in mind this is a plant that processes about 275,000 barrels of crude a day— close to 10% of the region's fuel supply.
But that’s not what caused the highest diesel prices ever.
Even before this refinery was taken out of commission, the national average price of diesel went above $6 a gallon last week for the first time ever. Filling up a long-haul semi truck now costs more than $1,000.
It's important to note that a barrel of crude oil is almost useless until somebody turns it into something. A refinery cooks the crude and breaks it apart into gasoline, diesel, jet fuel, heating oil, the raw material for plastics, etc.
Everyone knows about the squeeze on oil due to the war with Iran. But the shortage of REFINERIES is another issue.
Sure, the wars have taken a toll on refineries and other fuel plants. Iran bombed Bahrain's only refinery, shut ever since. It also wrecked half of Shell's Pearl GTL in Qatar, the world's largest plant for turning natural gas into diesel, jet fuel and lubricants. Ukrainian drones, meanwhile, have cut Russia's refining by roughly a third.
And the rest of the world's refineries can’t pick up the slack.
US refineries are already running at almost 98% of capacity. There's no spare refining capacity, and that’s because governments have treated refining as the enemy of humanity for the past decade.
For example, ten years ago Britain had six refineries. Then the UK government announced a ban on new gasoline and diesel cars and piled punitive taxes specifically on refineries, and today Britain is down to four.
I guess the “Just Stop Oil” fanatics are happy now. They actually declared victory last year and hung up their hi-vis (oil-based) vests, and quit (oil-based) gluing themselves to things, because "no new oil" had become official government policy in the UK.
California, meanwhile, imposed a new penalty tax on refinery margins, and then passed climate change regulations for refineries that are virtually impossible to achieve.
Unsurprisingly, in the past year, California lost two refineries: Phillips 66's in Los Angeles and Valero's in Benicia near San Francisco. That’s 17% of California's refining capacity.
Then Newsom panicked and changed his tune, realizing that California fuel prices would surge. He suddenly promised to "work closely with refiners." He directed his own energy commission to pause the punitive refinery tax for five years. He even pushed legislators to consider paying hundreds of millions of dollars to Valero to keep their plant open.
Too little, too late. The refiners left, or idled their plants. You can only bite the hand that feeds so many times before they take action.
But of course, everyone will pay for Newsom’s idiocy, because diesel moves everything. So much of American imports arrive at California ports (like the Port of Long Beach), and trucks haul it across the country from there. Trains do the rest.
And nearly every big truck and freight train runs on diesel, which is now a lot more expensive in California. So the cost of Newsom’s lunacy is paid by every consumer.
Harvest is starting across the Midwest right now, and everything from tractors to grain dryers burns fuel. Phosphate (another critical fertilizer ingredient) is mined and hauled with diesel.
So the farmer pays $6 a gallon, the trucker pays $6 a gallon… and consumers reimburse these costs in the form of higher prices.
And let’s not forget, winter is coming.
Heating oil is diesel by another name (it comes out of the same refinery), and about 5 million American homes heat with it, more than 80% of them in the Northeast. One Gulf oil executive warned last week of "a very difficult winter coming in Northwest Europe. This is only the beginning."
Bottom line, the power outage at Channahon is a problem. But it’s a small problem compared to the larger war on refineries.
With the spare refineries gone, even the slightest issue at remaining refineries now shows up in the price of diesel, food and everything else that moves on a truck.
Unexpected disruptions from war and power outages are one thing.
But governments deliberately villainizing refiners and chasing them out of town, for the crime of creating the energy the world desperately relies on, is another.
Their green policies and ESG mandates also helped drive a decade of underinvestment in the physical things civilization runs on: ships, mines, oil fields, smelters... and refineries.
Now the world is in the midst of a destructive war. When there is no spare capacity, every disruption has to be resolved by price, and the companies that own the scarce, strategic assets collect the difference.
And owning a piece of those companies yourself is the best way to protect yourself from higher prices and inflation.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S.
That's the whole point of Schiff Sovereign's investment research newsletter, Strategic Assets: profitable, low-debt companies that own or move real things, bought while they're still cheap.
Two oil tanker owners we featured when nobody wanted them are up more than 180% and 130%— one of them runs the ships that haul diesel— and our palm oil grower is up nearly 140%.
"Grow Our Way Out of Debt” Is Code for Inflation
"Grow Our Way Out of Debt” Is Code for Inflation
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 14, 2026
Last week, Treasury Secretary Scott Bessent sat down for a fireside chat at Southern Methodist University in Dallas and told the room what the plan is for the national debt.
"We don't have a revenue problem," he said. "We have a spending problem." Contain the spending, add 3% growth, and America can "grow our way out of this."
That’s a nice idea... and, it’s possible. The key part there is the spending freeze: arrest the growth in federal spending, and the deficit will eventually melt away.
The problem, of course, is that Congress won't even cut obvious fraud. So I don’t think taxpayers should hold their breath for sudden fiscal responsibility.
The growth side of his approach is feasible. But what does "grow our way out" of the debt actually mean?
The national debt is now a little over $40 trillion. Meanwhile the entire US economy— everything produced by every business and every worker in the country over a full year— is about $32.5 trillion.
This means the debt is 123% of GDP, i.e. the all-important debt-to-GDP ratio is 123%.
That ratio is the key indicator that bond investors watch. And it's the number Secretary Bessent is talking about when he says the US can grow its way out of debt.
The whole point is to bring that percentage down, from 123% today to something more like 80% or 90%.
Notice what he did NOT say. He didn't say the debt would shrink. He didn't say the deficit would go away. Growing your way out means the debt keeps getting bigger… it just grows at a slower pace, while the economy grows at a much more rapid pace.
Specifically, the US national debt has been growing at an average 6.7% per year over the past few years... which means ‘growing our way out’ will require the US economy to expand by at LEAST 7% per year, just to make a dent in the debt-to-GDP ratio.
Now go back to Bessent's number: he’s talking about 3% growth.
And when he says 3%, he means real growth, i.e. the economy producing 3% more goods and services than it did the year before. That means more cars, more houses, more software, more oil… more actual stuff.
But we just established that the economy will require 7% growth in order to fix the debt challenge.
So where, exactly, is the other 4% supposed to come from?
It comes from inflation. In short the economy produces 3% more stuff, but the stuff costs 4% more. In total that gets you to more or less 7% GDP growth, while the debt increases by 6.7%.
And with that, you have a tiny improvement to America’s dismal debt-to-GDP ratio.
This is already the path that they’re on; in the last year, America’s total (i.e. nominal) GDP growth was 6.5%. Of that, only 2% was real growth, i.e. the production of more goods and services.
The rest, about 4.5%, was from rising prices.
So "growing our way out" is really just a polite way of saying inflation. And the government is effectively telegraphing a 4% inflation target. As it happens, that's about where inflation already is right now.
In other words, the plan is to make everything else more expensive faster than the debt grows, and to call that a fix.
Four percent a year doesn't sound like much. But it compounds, and at that rate a dollar loses about a third of its purchasing power in ten years.
The solution is to own the stuff they can't conjure out of thin air.
A government can print money by the trillion, but it can't print an ounce of gold or a barrel of oil, or anything else that’s real or critical to the economy.
That's why real assets tend to hold their value when the currency is losing value... and why the businesses that produce those assets— gold miners, energy companies, copper producers, chip makers, etc.— often do spectacularly well.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
P.S. Real assets are the whole premise of Schiff Sovereign's investment research newsletter, Strategic Assets: profitable, well-run companies that produce the things a government can't print, researched while they're still cheap.
We locked in gains of more than 10x on a small silver producer we featured last year, and a gold producer has gone up 5x yet still trades cheaper against its earnings than the day we wrote it up. Two oil tanker owners we covered when nobody wanted them are up more than 150% and 110%.
25 Years Later— A Reminder That The World Can Change In An Instant
25 Years Later— A Reminder That The World Can Change In An Instant
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 11, 2026
At a time in my life which now seems centuries ago, I was once a young lieutenant, barely a year out of West Point, and I had recently been assigned to lead an electronic warfare platoon.
Whenever my unit wasn't deployed or in the field, most of my duty days were spent in a top-secret facility called a SCIF— the kind of place that was guarded by military police and didn't have any windows.
But every Tuesday morning at 9 a.m. sharp, my unit would formally assemble at the brigade motor pool to conduct routine PMCS checks— Army-speak for vehicle maintenance.
September 11, 2001, started like any other Tuesday morning.
Being on time in the Army is considered late, so naturally we all showed up to the motor pool around 10 minutes early. And the regular business after the formation only lasted about 5 minutes.
But in that brief 15-minute window, from the time we were milling around the motor pool to the time I was going back to the SCIF, the entire world changed.
I was about to walk into the building when one of my sergeants approached me and said, "Sir, I don't know if you heard, but terrorists just flew planes into the World Trade Center."
My reaction was disbelief. This dude is crazy. But the look on his face suggested he was serious.
I mumbled some meekish "whaaaaat" sort of reaction and exhaled a pfff of confusion, but then walked inside where the military police at the desk were refreshing CNN.com. I saw the screen. Images of carnage in New York. It was real.
After handing over my little Nokia bar phone, I was buzzed in and walked down one of the halls where someone had set up a TV— an old-school cathode ray tube mounted on a big rolling cart, just like the ones my teachers used back in middle school.
NBC was on. The chipper, perma-smile morning crew was still trying to anchor the horrific news coverage and doing their best to make sense of what was happening. Then legendary news veteran Tom Brokaw took over and brought those of us in the room— and the rest of America— up to speed.
Everyone over the age of 35 or so has their own version of this 'where was I' story about 9/11.
They're called 'flashbulb memories,' and they're forever emblazoned in our brains. It made me realize that my dad wasn't kidding around when he once went into vivid detail about the moment he heard that JFK had been shot.
We’ve experienced a few others over the past 25 years.
Many of us remember where we were when we heard about the 2008 Global Financial Crisis. I certainly do— my best friend called me and told me to turn on CNBC. It was Sunday September 14, 2008... and they were broadcasting live footage of Lehman Brothers employees filing into their office with cardboard boxes to clean out their desks.
The global financial system nearly collapsed the following day.
Similarly, many of us remember where we were when we first realized that COVID was real.
All of these flashbulb events over the past quarter century— with today being the 25th anniversary of 9/11— are reminders that the world can change in an instant.
Even if you’re too young to remember 9/11, you probably at least remember the pandemic. Everything changed, practically overnight.
To be frank, there will be others. We may see a day similar to the September 2008 financial crisis, when Americans tune in to see the bond market collapsing and Treasury yields surging... because foreigners are dumping their US government bonds all at once.
The irony is that a large part of America’s $40 trillion national debt... and hence the challenges with deficits, inflation, etc... is in large part due to the seismic shift after 9/11.
Before 9/11, America was in solid shape. The federal government was running a small budget surplus. And while the economy was slowing a bit and working off its hangover from the excesses of the tech boom in the 1990s, life was good.
But America went to war less than four weeks later on October 7, 2001. It lasted for twenty years and cost trillions upon trillions of dollars. Spending surged. The bureaucracy expanded. The surveillance state exploded.
And it all kicked off a borrowing spree that continues to this day. With the national debt now in excess of $40 trillion, more than 125% of GDP, America’s standing is waning rapidly.
Yes, there’s plenty of good news today and cause for optimism.
But the reality is that foreign ownership of US government bonds is falling. Even allies are starting to diversify. And it’s not hard to understand why: the US debt situation is a complete disaster.
So if this trend continues, we could absolutely experience another flashbulb-type event, where the whole world witnesses, in real time, the loss of America’s primacy.
The reaction will be similar to what most of us experienced on 9/11: total disbelief.
To be clear, nobody dies when yields spike, and a bond market crash is nothing like watching the towers fall. But the disbelief will be identical, because almost no one thinks it can happen here. It’s not supposed to happen here.
But it can. It just might. And if it does, just like the other flashbulb events— 9/11, the 2008 financial crisis, and the pandemic— the world could change dramatically in just 15 minutes.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
Here’s An Obvious Example Of A Critical Resource Shortage
Here’s An Obvious Example Of A Critical Resource Shortage
Notes From the Field By James Hickman (Simon Black / Sovereign Man) September 10, 2026
In July, the Canadian uranium miner Cameco stopped producing at its mine in northern Saskatchewan (known as ‘Cigar Lake’) for two weeks. Cigar Lake itself was fine, nothing was wrong with the mine. The problem was their sulfuric acid plant— a crucial ingredient in processing uranium ore— broke down.
Normally they would have just bought sulfuric acid from somewhere else while they fixed their company-owned acid plant. But this year that's not so easy.

About half the world's seaborne sulfur moves through the Strait of Hormuz, and since the war with Iran began, those shipments have almost completely stopped. China, the world's largest exporter of sulfuric acid, restricted its own exports in May to make sure they had enough.
So a simple mechanical problem at an acid plant caused a two-week shutdown of the world’s largest uranium mine.
Two weeks is a really long time for a huge mine like Cigar Lake to have an unscheduled shutdown; that’s because uranium is already in critical supply— there simply isn’t enough uranium being produced right now to keep up with demand.
The math is easy: miners produced roughly 155 million pounds of uranium in a year. Reactors burn about 185 million pounds. So there’s already a significant deficit.
For the past several years, the deficit between uranium production versus reactor demand was covered by stockpiles that had been building up over decades. So the nuclear industry effectively burned through its uranium ‘savings’.
But those stockpiles of uranium are now basically depleted... which means that nuclear power companies will need to rely on uranium production in order to meet their needs.
This is a problem... and one that we can quantify.
Because uranium is literally THE most important resource for a nuclear reactor, the reactor companies tend to line up their uranium supply needs years and years in advance through forward contracts and term agreements.
There’s no black magic here— it’s a pretty predictable quantity. A 2GW nuclear plant, for example, already knows exactly how much electrical capacity they have, so they know how much fuel they need to serve their customers... hence they can forecast their future uranium needs.
For this year at least, US nuclear power companies have more or less the amount of uranium that they anticipate needing. But next year they’ll be in a deficit... and one that grows each year.
By 2030, US nuclear power companies will be short 40% of their anticipated uranium needs. By 2033, they’ll be short 91%. Basically all of it.
Big deal, right? Existing uranium producers can simply mine more.
But that’s not really happening... at least, not at current prices.
Kazatomprom (based in Kazakhstan) is the largest uranium miner in the world. And their management is deliberately pulling back on production right now.
The company believes that it's simply not worth mining and selling uranium at the current price. Why bother producing at your full potential now when they KNOW the price is going to rise in the future, hence they make a LOT more money in the future if they mine less now.
OK well, the big shortage in the 2030s is still a few years away. So the industry has time to start more mines and bring new uranium production online.
Well, that’s easier said than done.
A company called NexGen Energy discovered a major uranium deposit in Saskatchewan back in 2014. They finally got their construction license this March, started building in August, and expect their first ore in 2030.
In other words, SIXTEEN years from discovery to production— and that's about average for the industry.
You can’t just turn on uranium production like a light switch; it takes years and years to make most things happen in business, and uranium mining is no different.
This is common across many real assets— there has been years of underinvestment. Very few new uranium mines. Very little oil & gas exploration. Not enough new shipyards, refineries, smelters, etc.
It takes several years... plus a lot of risk capital... to discover a new resource deposit and bring a mine to life. Years.
Demand can grow much more quickly. Just look at the increase in electricity demand (thanks in large part to data centers). When electricity demand surges, but the supply of the fuel required to generate electricity is stagnant, the end result is higher prices.
And not just higher electricity prices— higher prices for the fuel as well, i.e. higher natural gas prices, higher uranium prices, and even higher coal prices.
(Coal is especially interesting— it was basically chased out of town. NO ONE wanted to invest in a new coal mine thanks to Greta Thunberg. Yet the International Energy Agency now expects coal-fired power generation to rise this year to make up for energy imbalances. Stagnant supply meets rising demand.)
That's tough news for anyone with an electricity bill. But you can also be on the other side of it and make money from this trend.
When supply and demand is so fundamentally unbalanced, the companies that produce these scarce resources tend to perform extremely well.
This is the primary investment ethos for our investment research newsletter, Strategic Assets.
We look for the most critical resources that the economy runs on; we find sectors where there has been chronic under -investment and focus on undervalued yet successful companies with great management and balance sheets.
Energy has been good to us. Two oil tanker owners we featured when nobody wanted them are up more than 150% and 110%.
A small South American oil producer we featured last month has no debt and sells every barrel at the wellhead to one of the largest oil companies on earth— so shipping is someone else's problem. A typical new well takes years to pay for itself. This company's fastest did it in 37 days.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
The Candlestick Makers Are Back, and This Time They're Not Joking
The Candlestick Makers Are Back, and This Time They're Not Joking
Notes From the Field By James Hickman (Simon Black / Sovereign man) September 3, 2026
In 1845, the French economist Frédéric Bastiat petitioned parliament on behalf of the nation's candlestick makers. They were being ruined, he wrote, by an unscrupulous rival that was flooding the market with light at a price no honest candlestick maker could match.
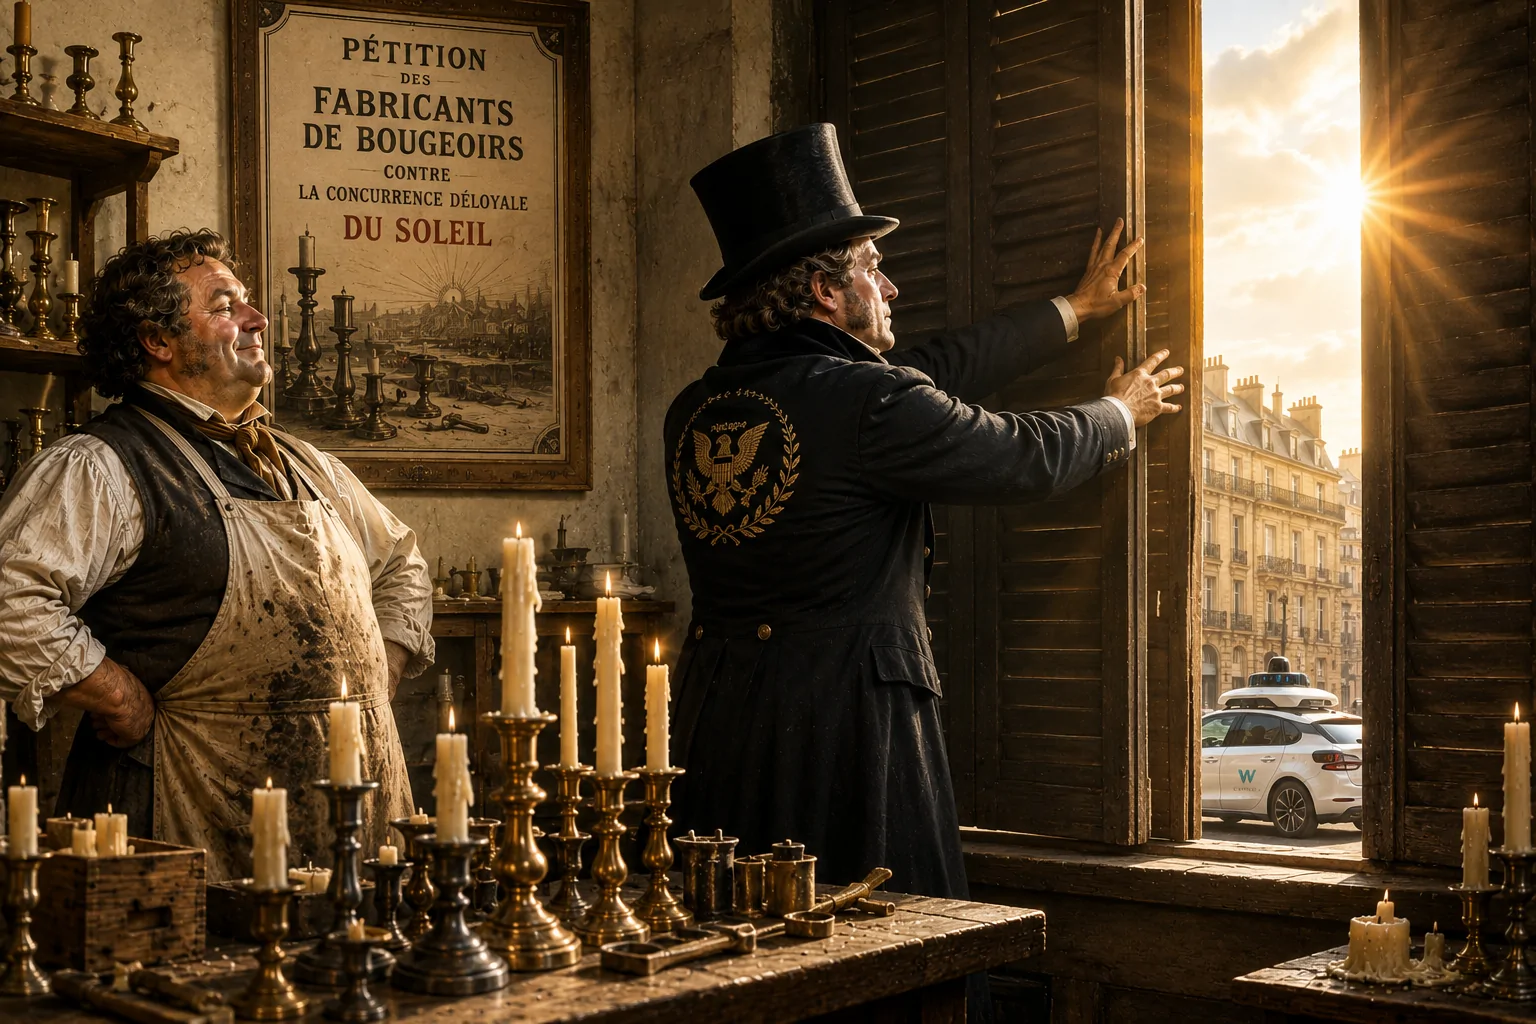
This light-producing rival, of course, was the sun.
And Bastiat satirically demanded "a law requiring the closing of all windows, dormers, skylights, inside and outside shutters, curtains… in short, all openings, holes, chinks and fissures" to ensure that no sunlight could enter French homes.
Think of the jobs this would create. "If more tallow [curtains] be consumed, there will arise a necessity for an increase of cattle and sheep," the petition argued. "Thousands of vessels would soon be employed in the whale fisheries [for oil]."
Bastiat, one of history's most famous proponents of free markets, was obviously joking. He wrote the petition to mock the tariff wall that sheltered France's industries from cheap foreign goods— block the cheaper competitor, protect the domestic producer, count the jobs saved.
No one counted the cost of protectionism: everyone else paying more for everything, and the whole country became poorer.
Yet decade after decade since, every new innovation has been met with exactly this kind of uproar. And nobody is joking.
It wasn't so long ago that taxi drivers were up in arms over Uber undercutting their prices. In June 2015, nearly 3,000 of them shut down parts of Paris, burning tires and blocking airport roads, because Uber's cheap service didn't require the professional taxi license that could cost $270,000.
The French government caved within a day, ordering police to seize the unlicensed Uber drivers' cars.
Now the wheel has turned. Waymo's robotaxis launched in Atlanta in June 2025, bookable through the Uber app of all places. And Uber drivers say the competition is cutting their pay.
Naturally the Atlanta Rideshare Drivers Union wants the city to slap a $0.50 to $1.00 fee on every robotaxi ride, paid into a "driver transition fund," plus a ban on robo pickups at the Atlanta airport.
If only they could tax the sun for the candlestick makers.
The federal government runs the same play, just bigger.
In January 2025, the Commerce Department finalized its ‘Connected Vehicle Rule’, which bans cars with Chinese-linked software from the US market, starting with the 2027 model year.
The stated reason is national security: keeping foreign adversaries out of the cameras, microphones, and GPS units on American streets.
That's a real concern, to be fair. But then came the carve-outs.
Volvo, majority-owned by China's Geely, got authorization in May to keep selling. Ford, after talks with the department, decided its China-built Lincoln Nautilus doesn't need an exemption at all.
But Polestar— owned by the same Chinese parent as Volvo— was shut out and is leaving the US market.
The Commerce Department doesn't publish these decisions or its reasoning, so nobody outside the building knows why one Geely brand got a green light and the other got kicked out of America.
Let’s be honest: if these Chinese cars were really a security threat, there would be no carve-outs to negotiate. There would be a flat ban. No exceptions.
The real threat of cheap Chinese cars is to the profits of American automakers; Chinese cars are very inexpensive— like a decent quality mid-size SUV for around $20k. So many US buyers would start driving Chinese that the American automakers would either have to adapt and compete... or suffer catastrophic losses.
The end result of these bans is less competition, meaning Americans end up paying more for their vehicles.
Just add this to the long list of things which governments, from city councils to federal regulators, make more expensive.
Yesterday we wrote about how federal influence over local building codes adds $132,000 to the average new home.
Today it's how they're making buying a car and taking a quick trip more expensive.
Ask California how it's doing on that nonexistent high-speed rail… $15 billion and 18 years in, without a mile of track. Or ask Europeans, where climate fuel mandates are already tacking surcharges onto every plane ticket.
The receipts are everywhere: everything the government touches becomes more expensive.
College tuition is up about 1,200% since 1980— the surge began as soon as the federal government made itself the nation's student lender.
Since Obamacare passed, the average family health insurance premium has nearly doubled.
Even junk food became more expensive due to government food subsidies; in fact the moment 18 states pulled soda and snacks off the food stamp list, PepsiCo cut prices on Doritos and Lay's by up to 15%.
Housing, transportation, food, healthcare, education— all swamped by government interference, all quickly became less affordable.
And underneath all of it, bringing the whole pot to a boil, is the inflation that politicians and regulators caused with their own spending.
Yet who do they blame? Greedy corporations.
Inflation has nothing to do with greed. It has everything to do with incompetence and irresponsibility.
Bastiat's joke was that nobody would ever actually file the candlestick makers' petition. Yet 181 years later, what started as satire is taking place every single day.
A political class that treats cheaper goods and services as a threat is deliberately choosing to make the country poorer.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
PS: A government that treats cheaper as a threat isn't going to start choosing growth anytime soon. That's exactly why we publish Plan B Confidential— our flagship research on legal, practical ways to diversify your savings, your income, and even your residency beyond any single government's bad decisions.