Why We Go Wrong
John Lim | January 16, 2021
I’VE LONG BEEN flummoxed by the difficulty people have managing money. It all seems so intuitive: Save, invest, repeat. Buy more when the market falls and a lot more when it crashes. Rebalance by adding more to losing asset classes—which today means buying value and international stocks.
Now, don’t get me wrong: I’m no financial genius. I’ve made my share of blunders. But I also know that being a do-it-yourself investor has saved me boatloads of money. When I’ve encouraged colleagues to do the same—imploring them that “it’s really not that hard”—I’ve received only steely stares and blank looks.
It’s slowly dawned on me that the financial demons people wrestle with are real and of Herculean proportions. Finance is a minefield that few navigate without getting maimed. It’s replete with mirages—what you see is often not what you get. Our instincts hurt us more often than they protect us. Actions that are sensible in every other realm of life lead us astray in finance.
What follows is an exploration of eight key concepts that many—and perhaps most—investors struggle with. The biggest paradox of all: While managing money may appear simple, it’s anything but.
1. Compound interest is the key to wealth. We’re woefully ill-equipped to wrap our heads around the wonder that is compound interest. Warren Buffett described his eureka moment at age 10. “That’s where the money is,” he told himself, referring to the power of compound interest.
The miracle of compound interest is a collision of two intangible concepts—exponential growth and a long time horizon. It’s well known that people struggle when making decisions that have consequences well into the future. Economists refer to such myopia as “present bias,” a universal human tendency to favor the present over the future.
The abysmally low U.S. savings rate exemplifies this mindset. But it also reflects a failure to grasp the immense power of exponential growth over long stretches of time. In brief, we each need our own eureka moment.
Consider the story of the Lenape Indians. In 1626, they sold the island of Manhattan to Peter Minuit for a mere $24. That was the greatest swindle in U.S. history, right? If you compound $24 at 7% a year—which is the average after-inflation return of the stock market—what would it be worth today? Almost $10 trillion. Let that sink in.
2. Laziness is a virtue. Life teaches, and common sense affirms, that hard work pays off. Sloth was so disdained in medieval times that it was labeled one of the seven deadly sins. Yet lazy investing leads to superior, not inferior, results.
To continue reading, please go to the original article here:
6 Attitudes That Breed Financial Failure
By Kentin Waits WiseBread
Financial success or failure is often the result of attitudes — both conscious and unconscious — that affect our behavior. No amount of budgeting and self-control can help us when we’re up against ingrained ideas about money management, spending, and debt. If you’re having a tough time shifting your financial behavior, maybe it’s time to change your mind about money. Here are six common attitudes that work against us financially.
Plan B Options for folks on Social Security
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 27, 2026
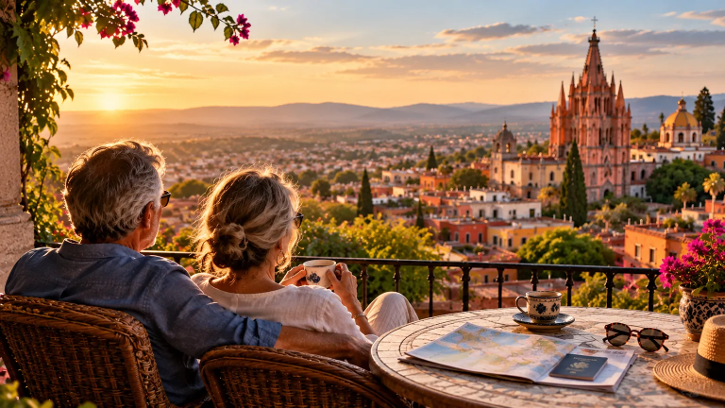
In the early morning hours of February 7, 1937, a young American named Stirling Dickinson got off a train in central Mexico and rode into San Miguel de Allende on a mule-drawn cart.
He and a Princeton classmate were months into a trip around Mexico looking for a quiet place to write, and a Mexican opera singer had told them to try San Miguel.
A Condo in this Ghost City Gets You Ten Years Residency
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 22, 2026
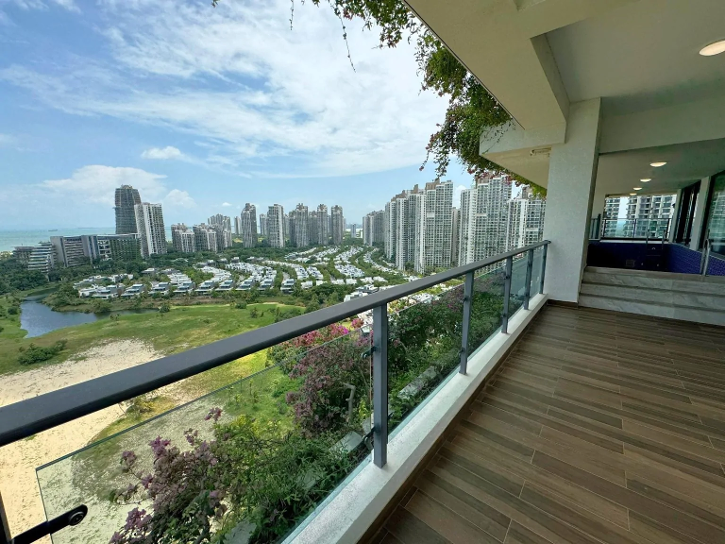
On March 6, 2016, Malaysia’s prime minister, Najib Razak, turned up for the grand opening of a city that did not exist yet, two kilometers off the coast from Singapore.
It was called Forest City, and the plan was enormous. One of the largest property developers in the world came in to build four artificial islands in the strait and put a “smart, green” city of 700,000 people on them, at a cost of roughly $100 billion.
Avoid These 4 Common Mistakes When You Get Rich Overnight
September 4, 2025 by Laura Bogart GoBankingRates
You’re about to score a financial touchdown. Maybe you’ve crushed it at work and landed a sweet promotion. Perhaps you’ve won a lottery or stumbled into a side hustle that suddenly pays off. As you near the end zone, heart pounding, head full of dreams, you can’t afford (literally) to fumble. Whether you’re blindsided by unexpected taxes or tripped up by bad financial advice, you have a lot to lose if you drop the ball.
6 Common Excuses for Not Saving Money By Tara Struyk
Have you ever settled on a new exercise program, only to get a bad cold a few days in and happily throw yourself on the couch, relieved to have a handy excuse? Excuses must be human nature; I know I usually make them when I'm facing something that’s new, that's hard, or that I just don’t enjoy. And I’ve certainly made excuses when it comes to money.
In the years that I’ve been writing about personal finance and investing, I’ve also heard my fair share of excuses, mostly from readers who don’t agree with my advice. The problem is, unlike good financial habits, excuses are easy to come by, even though most of them just don’t stand up to reason. Check out some of the ones I’ve heard most frequently so far.
How To Make Strategic Cash Bucketing Work For You
Last Edited Sep 16, 2026| Angelena Mascilli
Cash bucketing – or categorizing your funds based on specific expenses or goals – can help you organize your financial life.
Cash and other liquid assets may be the ideal place for buckets of money that you may need to access soon to cover expenses or capitalize on new investment opportunities.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
Brazil’s Massive Crash Is A Sign Of Things To Come In The West
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 29, 2026
On Sunday night, Brazil re-elected its left-wing president, Lula da Silva. On Monday morning the São Paulo stock market fell so hard at the open that the exchange halted trading for the first time since the pandemic. When trading resumed, Brazil’s stock market kept falling.