What Should You Do With a Life Insurance Benefit?
What Should You Do With a Life Insurance Benefit?
By Melanie Lockert The Fabric Blog
We’ve all dreamed of coming into a large sum of money. You imagine all the ways you’d spend a million dollars and think how much better your life would be. But what if you did get a large sum of money but it came at a great cost? This is what life insurance is all about.
But what is it like getting a life insurance death benefit and how does it actually work? What should you actually do with a life insurance benefit? We chatted with personal finance experts to find some answers.
Receiving a Life Insurance Benefit
Life insurance death benefit amounts can vary depending on the policy. Generally, life insurance payouts aren’t taxable unless you earn interest.
Emily Guy Birken, author of End Financial Stress Now received a life insurance death benefit in 2013 after her dad passed. During a time of grief, it can be difficult to do almost anything—but luckily the process of claiming her death benefit wasn’t too difficult.
“I was pleasantly surprised at how easy it was to get the life insurance payout. Based on life insurance in pop culture, I thought it would be a more drawn-out or emotionally draining process,” she says.
In order to receive the life insurance payout, Birken says she had to fill out paperwork, sign documents and send in the death certificate. It took her about two to three weeks to receive the payout. In general, this process can often take between 30 to 60 days.
Choosing Between Payment Options
When it came to actually getting the life insurance payout, Birken was offered a couple of options. “The insurer offered us the option of receiving the full amount in either a check or direct deposit, or keeping it in their interest-bearing account, which is what my sister and I both opted to do,” explains Birken.
Choosing to keep it in the interest-bearing account was a strategic move and one that helped her manage her spending.
To continue reading, please go to the original article here:
https://meetfabric.com/blog/what-should-you-do-with-a-life-insurance-benefit
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
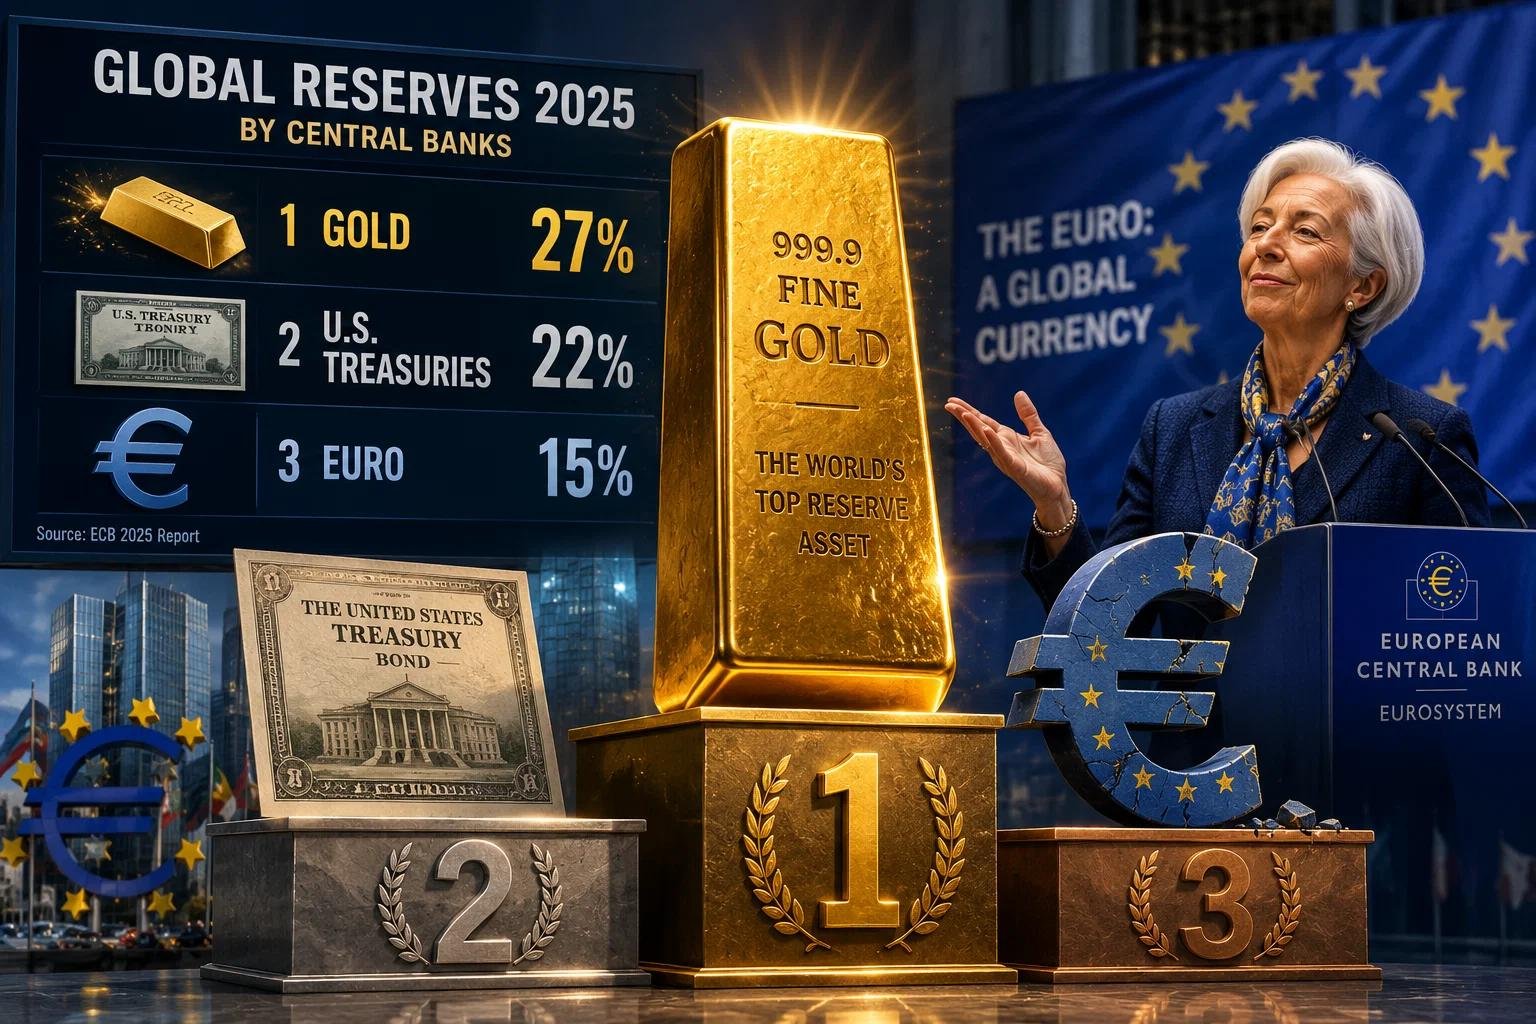
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
Green Policy is Deadlier Than Guns
Notes From the Field By James Hickman (Simon Black / Sovereign Man May 29, 2026
Every year around this time, a silent killer sneaks its way onto European shores and slaughters people by the tens of thousands. Last year, it killed more people in just three months than the number of civilians killed in the war in Ukraine all year. It killed three times as many people as traffic accidents do. And it killed FOUR times more Europeans than gun violence killed in America. I'm not talking about COVID. Or even the legions of migrants invading the continent.
4 Bad Habits That Could Affect Your Money More Than Tariffs and Inflation
Written by Chris Adam GoBankingRates
The Trump administration’s discussions about tariffs and inflation have led many consumers to question how well they’re prepared for the future regarding their finances. After all, some experts have raised concerns that tariffs could lead to higher prices on products and services people use each day.
But there may be a way to protect personal finances that has little to do with moves by the White House.
Expert Issues Warning Over US Bank Accounts Sitting Idle
Rudro Chakrabarti Mon, April 20, 2026
Money Can Now Be Turned Over To State. Secure your money ASAP
Katelyn Fugate thought she was doing something nice for her young son. A few years back, she opened a savings account for him — a small starter fund he could build on one day. Recently, she decided to check in on it.
The balance was zero. Fugate told Scripps News she went to check the balance hoping to start adding to it again. Instead, she found the account empty. (1) The bank had declared it dormant after five years of inactivity, closed it and shipped the money off to the state's unclaimed funds department. Worse, when Fugate went looking for it, she couldn't find the money at the bank or the state.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses