What Should I Do With a $50k Inheritance?
What Should I Do With a $50k Inheritance?
Mark Henricks Wed, December 30, 2020
It’s not uncommon for people to receive sizable inheritances, but it’s less common for them to make the most financially advantageous decisions about what to do with their newly acquired assets. If you inherit a significant amount, such as $50,000, a strategy for wisely handling a windfall is likely to include making a long-term plan that considers your age and goals, starts with a well-stocked emergency fund and employs tax-advantaged investments if available. Consulting with a financial advisor is a great way to develop a realistic long-term plan and lay out some strategies for reaching your goals.
Over an eight-year period, one in five American households, including older workers, got an inheritance averaging $67,000, according to a 2006 research report. But most spend the money in a few years and have little left to show. A decade after getting an inheritance, the typical heir still has just a third of the windfall, according to a Swedish study from 2016. Here’s how to make an inheritance last.
Inheritance Strategies
The first thing to do after receiving a sizable inheritance is to place the funds in a secure account, such as a bank savings account or money market fund, while you take stock.
Whether you do it on your own or with professional assistance, create a sensible plan for handling the inheritance. Start with your current circumstances. Consider your age, income, assets and debt. Factors like your personal risk profile, future obligations such as children’s college and personal goals such as business ownership come into play.
Note that inheritances are not considered income by the IRS, so you won’t have to pay taxes on the money you inherit. However, any interest or capital gains on investments you make with the funds could be subject to taxes.
Before making any long-term investments, creating a rainy-day fund is likely to be a priority. Loading a secure, easily accessed account with three to six months of basic expenses can provide peace of mind while avoiding the need to borrow or tap illiquid funds in the event of an emergency.
Reducing high-rate debt could be next. Paying off revolving credit card balances will save more on interest than most investments can ever return. Getting into the habit of settling credit card accounts in full every month will prevent taking on more high-cost debt in the future.
Specific Options
After these priorities, much of the inheritance will be invested to build wealth long term.
To continue reading, please go to the original article here:
https://finance.yahoo.com/news/50k-inheritance-161412124.html
How To Make Strategic Cash Bucketing Work For You
Last Edited Sep 16, 2026| Angelena Mascilli
Cash bucketing – or categorizing your funds based on specific expenses or goals – can help you organize your financial life.
Cash and other liquid assets may be the ideal place for buckets of money that you may need to access soon to cover expenses or capitalize on new investment opportunities.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
12 Key Habits for Achieving Financial Freedom
Set yourself on the path to saving with these habits
By Matt Danielsson Updated March 06, 2026
Key Takeaways
Set financial goals and create a plan to achieve them.
Make and stick to a budget covering all financial needs.
Pay off credit cards monthly and minimize debt.
Automate savings with an emergency fund and retirement contributions.
U.S. consumers can request a free annual credit report from major agencies.
The Seven Deadly Sins Of Personal Finance
By J.D. Roth —03 June 2019
I've been reading and writing about personal finance for more than thirteen years. In that time, I've consumed a lot of books about money. Lately, I've found that it's fun to revisit old favorites.
Recently, for instance, I've been re-reading Brett Wilder's The Quiet Millionaire [my review]. It's different than most personal finance books. It's targeted at those who are farther along their financial journeys rather than at those just starting out. Still, there are bits and pieces in The Quiet Millionaire that are applicable to everyone.
5 Reasons Not to Use Debit Cards When You Shop Online
By Holly Johnson.
Many consumers use their debit cards for everything they buy. Using debit instead of paying with a credit card can help you avoid the potential for debt. The money is taken out of your bank account directly and immediately, so there’s little chance to spend more than you have, unlike using a credit card.
5 Pieces of Financial Advice to Avoid at All Costs
Suze Orman on the commonly accepted money tips it pays to ignore.
By Suze Orman
Bad financial information doesn't come only from scammers; even our loved ones can unwittingly steer us wrong. That's why knowing what not to do with your money is often your biggest asset. In general, there are two little words that should set off everybody's suspicion meter: Trust me. Anyone who gives you this line—whether a financial adviser or your significant other—is disrespecting you.
Powerball Winner Wished He 'Tore Up Ticket' After $315m Jackpot Destroyed Him
Story by Liam McInerney
The world's largest lottery is launching in the UK this week - offering a fortunate British player the chance to become more than £300million ($400m) wealthier. Powerball, an American lottery game, awards massive jackpots that are distributed over a 30-year period.
Today (July 23) marks the inaugural UK draw with an estimated top prize exceeding £300m - the biggest jackpot ever made available in Britain. Allwyn, which operates the National Lottery, has opened the game to UK participants, who will be entering alongside American players.
No Such Thing as Enough Money
Jacob Schroeder Oct 27, 2021
How much money is enough?
It’s a philosophical money question that often arises out of discontent. We see someone of substantial means, like a celebrity, live a troubled life. Or, we ourselves experience great fortune yet feel unhappy.
It makes us wonder where the finish line is, the point when you can stop striving for more and settle into a life of satisfaction.
The Relationship Between Money and Marriage
Jacob Schroeder Oct 12, 2021
I love scotch; she hates it.
There are many things my wife and I don't agree on, but money isn't one of them. We are intentional spenders, buying only what mutually aligns with our needs or values. For instance, disinterested in paying for the trappings of an ostentatious wedding, we tied the knot at New York's City Hall; our reception was watching our first son play at a public playground in the East Village on a warm fall afternoon.
We've been happily together for 16 years, which makes me wonder: Does love make the financial side of marriage work, or is it the other way around?
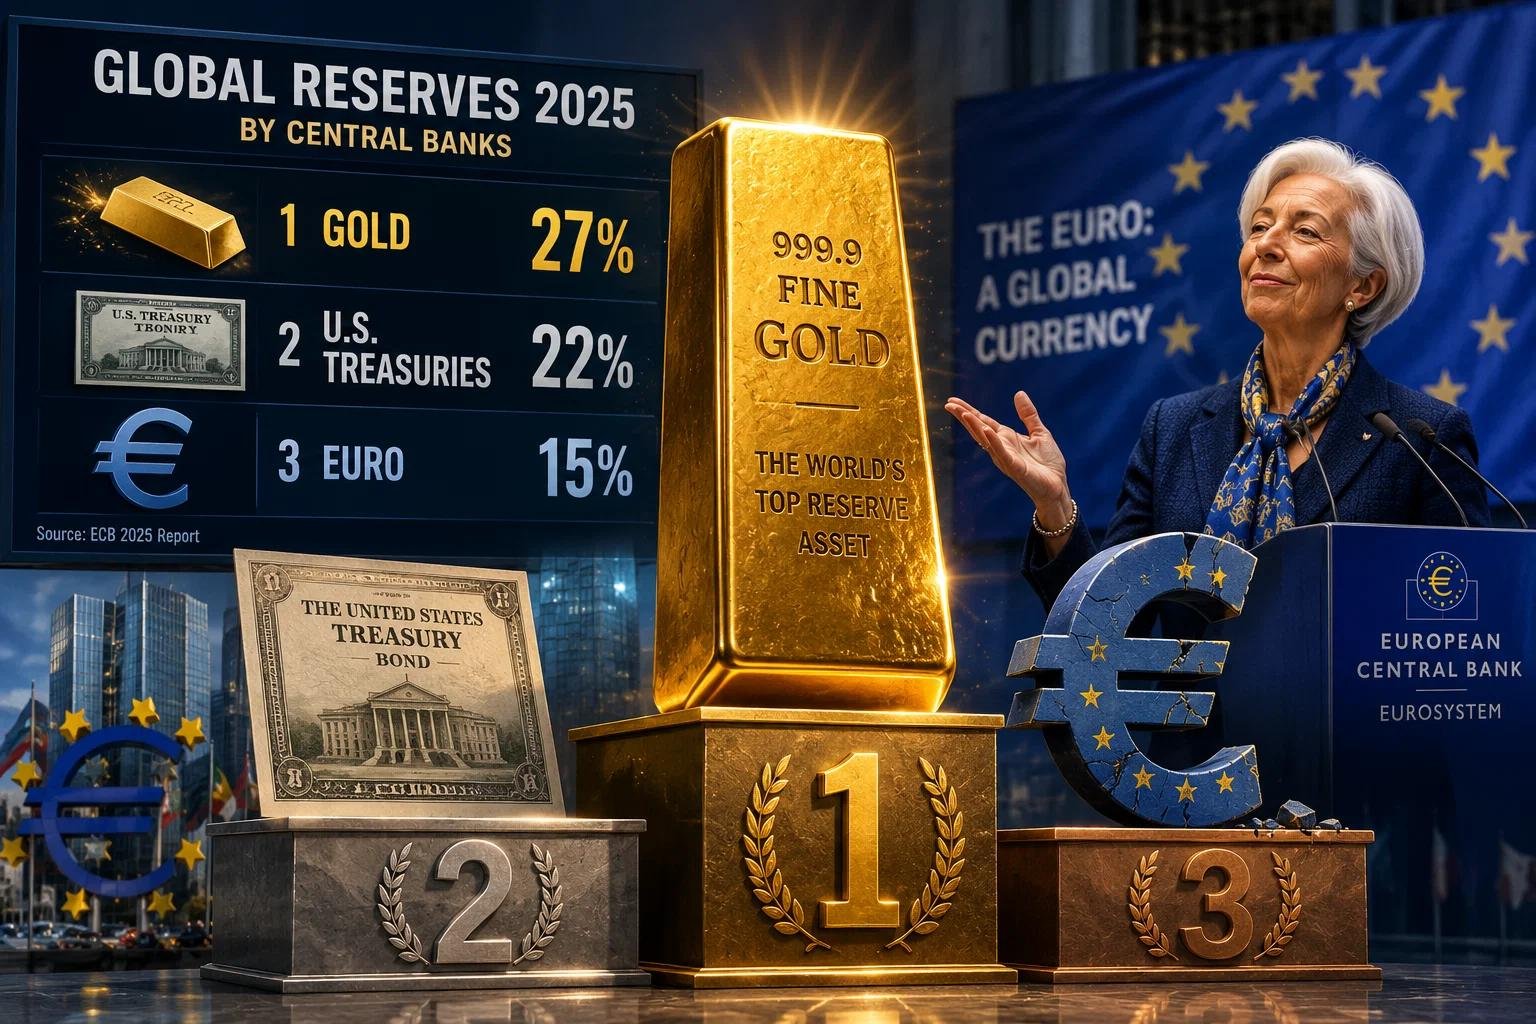
Europe Just Bragged About Losing to Gold
Notes From the Field By James Hickman (Simon Black / Sovereign Man) June 4, 2026
When the euro launched on January 1, 1999, it was sold as the future. It would be a single currency to knit Europe together — to wipe out the exchange-rate friction between member states, complete the continent's single market, and bind a dozen squabbling nations into one economic bloc with one money.
And in the grander ambitions of its architects, it was meant to do something more: to grow up into a true global currency, the first serious rival the US dollar had faced since World War II.
Experts Say This Is A Key Sign You Have An Unhealthy Relationship With Money
By Natalia Lusinski
When it comes to money and budgeting, it’s often easier said than done. You may have the best of intentions — you’ll eat out less this month and put the money into your savings account instead. But then life happens. Just like working through any other life, fitness, or wellness issue, a little introspection is often the ticket. If you want to get your finances back in order, a financial psychologist or money mindset coach can help. It all starts with getting your head in the right place.
6 Common Excuses for Not Saving Money By Tara Struyk
Have you ever settled on a new exercise program, only to get a bad cold a few days in and happily throw yourself on the couch, relieved to have a handy excuse? Excuses must be human nature; I know I usually make them when I'm facing something that’s new, that's hard, or that I just don’t enjoy. And I’ve certainly made excuses when it comes to money.
In the years that I’ve been writing about personal finance and investing, I’ve also heard my fair share of excuses, mostly from readers who don’t agree with my advice. The problem is, unlike good financial habits, excuses are easy to come by, even though most of them just don’t stand up to reason. Check out some of the ones I’ve heard most frequently so far.