We’ll Get Through This
Mar 9, 2020 by Morgan Housel
In the 1930s an Ohio lawyer named Benjamin Roth kept a detailed diary about what he saw during the Great Depression.
In the late 1930s, when the depression had mostly passed, he summarized a few points he had learned from the debacle. He wrote:
“Business will always come back. It will remain neither depressed nor exalted.”
“The stock market forecasts business in only a limited way. The beginning of a stock market movement usually is caused by the trend of business but in the end the movement is carried too high or too low—by the extreme optimism or despair of human nature.”
“Depression is time of greatest profit. The investor who has liquid funds and the courage to act can lay the basis for great profits.”
It’s silly to compare the last week to the Great Depression – unemployment is near a record low and the market is still up over the last 10 months. It’s also hard to think of a time when sentiment has changed so far, so fast, than the last week. And what’s really silly is to assume that abrupt shift won’t both feed on itself and lead to tangible economic problems.
But let me offer some advice, echoing Benjamin Roth’s lessons from 90 years ago: We’ll get through this.
It won’t be easy, and for some it will be agonizing. But no one should be surprised when a market economy that offers so many benefits occasionally asks something in return.
Keep a few things in mind.
1. Booms plant the seeds of busts. Busts do the same in the opposite direction.
There are no exceptions to Newton’s third law of physics. Every action has an equal and opposite reaction.
It’s tempting to fall for the siren song of booms because it’s so easy to extrapolate a positive trend without accounting for its offsetting factors. Booms make people complacent, assets expensive, and businesses fragile – all of which are easy to discount and hard to even measure when things are going well. It’s usually only in hindsight that we look back and realize how oblivious we were to the forces building up against us.
The same thing happens in reverse during busts. Relative to literally five hours ago, people are more aware of the risks they’re taking, businesses are looking for ways to get more productive, and assets are priced for better future returns – all of which are easy to discount and hard to even measure when things are falling apart.
It’s strange to think that we’re better positioned for future growth this week than last week. How can that be, given everything that’s happened? Well, it may get worse. But every step down plants the seeds for the next ride up.
2. Compounding is not about earning the highest returns. It’s about earning pretty good returns for the longest period of time possible.
Earning 20% a year and getting washed once a decade will leave you worse off than earning 8% a year and being able to hold your ground when times get rough. That’s so obvious. But it’s times like this that you realize financial “survival” is not just relevant to the broke and paranoid; it’s the single most important ingredient to long-term growth.
“Survival” means different things. It means having a strategy whose downsides you’re preemptively familiar with, so you’re prepared both psychologically and financially when they occur.
To continue reading, please go to the original article here:
https://www.collaborativefund.com/blog/well-get-through-this/
From Windfall to Financial Foundation
Marguerite C. Weese Chief Wealth Strategist
Practical first steps for turning unexpected money into greater security and long-term opportunity
Key Takeaways
Pause before making major decisions by keeping the money secure, gathering information, and avoiding pressure to spend, invest, or give before you have a plan
Match the money to your goals by separating short-term needs from long-term priorities so you know what should stay accessible and what may be invested for future growth
Get guidance before complexity creates mistakes, especially when taxes, inherited assets, debt, family requests, or investment choices may affect your next steps
5 Questions To Ask An Advisor About A Financial Windfall
Get help turning sudden wealth into a sustainable plan.
Fidelity Wealth Management
Key takeaways
A windfall can create new opportunities, but it can also bring emotional and financial complexity. Taking time to understand your new financial picture can help you avoid costly mistakes.
Significant increases in net worth may require updates to your portfolio, insurance coverage, estate plan, and approach to family and charitable giving.
Building the right team of financial, tax, legal, and insurance professionals can help you navigate new opportunities and challenges with confidence.
Did You Get Rich Quick? These 4 Steps Can Help You Stay That Way
By Jeremy DiTullio, CFP®, AWMA®, CRPC® Reviewed by Lisa Hitt
Published August 29, 2026 In Features
Sudden wealth is less about the money and more about the discipline required to manage it, so it's critical to pause and plan before making any major financial moves
Sudden wealth doesn't change who you are. It does reveal how prepared you are.
I recently read a news story in which a lottery winner who received a jackpot worth more than $167 million had reportedly been arrested four times within 14 months of receiving the money.
Rethinking the Inheritance Timeline
November 13, 2026 Wendy Farrissey
As lifespans increase, affluent investors may want to consider accelerating inheritances to help heirs at critical junctures in their lives.
For years, wealth advisors have been discussing the implications of the Great Wealth Transfer—the expected shift of some $124 trillion from older to younger generations over the next two decades.1
How Much Gold Should You Have In Your Portfolio? Experts Weigh In
Faith Wakefield, USA TODAY Sun, November 15, 2026
Gold is often viewed as a store of value and can help stabilize portfolios during times of inflation or market volatility. But how much gold should you have in your portfolio? And is it even necessary at all?
Experts tend to recommend investors hold between 0% and 15% of their portfolio in precious metals, with gold typically making up the largest share. A common starting point for moderate buyers is 5%.
There’s a Different Way
Notes From the Field By James Hickman (Simon Black / Sovereign Man) November 6, 2026
A friend of mine got legal residency in New Zealand a couple of years ago as global tensions rose around wars in Ukraine and the Middle East. He was only half joking about why. His reasoning is that if WW3 breaks out and the nukes start flying, he would want to be in New Zealand.
But he’s not picking up his life, abandoning all caution, and permanently moving to a new country. He just has a plan, and the basics in place.
Tomorrow’s Election Changes Nothing About The National Debt
Notes From the Field By james Hickman (Simon Black/Sovereign Man) November 2, 2026
Johnny Moon was homeless and unemployed in the early 2000s. A high school dropout with a bad drug habit, Moon was hardly someone that banks would consider creditworthy.
And yet, over the course of a single year, he was able to borrow more than $600,000 to buy five different investment properties.
7 Surprising Benefits of Failure
By Kentin Waits WISEBREAD
Everyone loves a success story, and the world is filled with them. But what about stories of failure? Can't they be as just as educational? Just as inspirational? Equally insightful?
After all, a single big win is often built on several losses. It's a truth perfectly captured in the words of Japanese industrialist and automaker, Soichiro Honda, "Success is 99% failure."
Brazil’s Massive Crash Is A Sign Of Things To Come In The West
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 29, 2026
On Sunday night, Brazil re-elected its left-wing president, Lula da Silva. On Monday morning the São Paulo stock market fell so hard at the open that the exchange halted trading for the first time since the pandemic. When trading resumed, Brazil’s stock market kept falling.
6 Attitudes That Breed Financial Failure
By Kentin Waits WiseBread
Financial success or failure is often the result of attitudes — both conscious and unconscious — that affect our behavior. No amount of budgeting and self-control can help us when we’re up against ingrained ideas about money management, spending, and debt. If you’re having a tough time shifting your financial behavior, maybe it’s time to change your mind about money. Here are six common attitudes that work against us financially.
Plan B Options for folks on Social Security
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 27, 2026
In the early morning hours of February 7, 1937, a young American named Stirling Dickinson got off a train in central Mexico and rode into San Miguel de Allende on a mule-drawn cart.
He and a Princeton classmate were months into a trip around Mexico looking for a quiet place to write, and a Mexican opera singer had told them to try San Miguel.
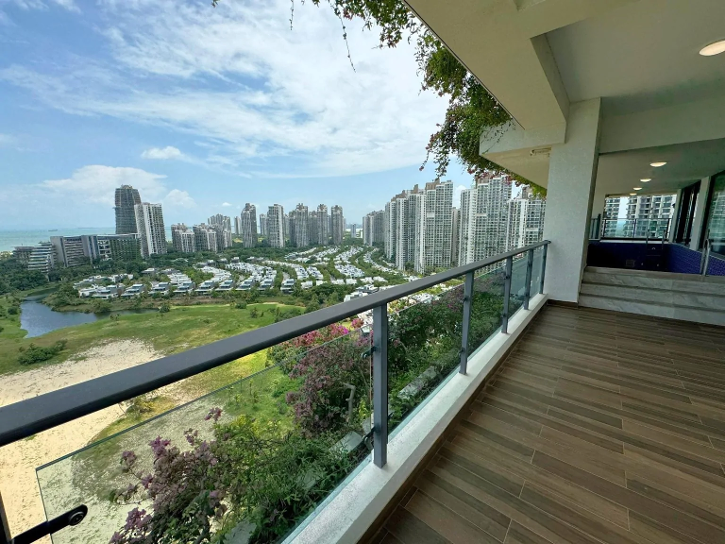
A Condo in this Ghost City Gets You Ten Years Residency
Notes From the Field By James Hickman (Simon Black / Sovereign Man) October 22, 2026
On March 6, 2016, Malaysia’s prime minister, Najib Razak, turned up for the grand opening of a city that did not exist yet, two kilometers off the coast from Singapore.
It was called Forest City, and the plan was enormous. One of the largest property developers in the world came in to build four artificial islands in the strait and put a “smart, green” city of 700,000 people on them, at a cost of roughly $100 billion.
Avoid These 4 Common Mistakes When You Get Rich Overnight
September 4, 2025 by Laura Bogart GoBankingRates
You’re about to score a financial touchdown. Maybe you’ve crushed it at work and landed a sweet promotion. Perhaps you’ve won a lottery or stumbled into a side hustle that suddenly pays off. As you near the end zone, heart pounding, head full of dreams, you can’t afford (literally) to fumble. Whether you’re blindsided by unexpected taxes or tripped up by bad financial advice, you have a lot to lose if you drop the ball.
6 Common Excuses for Not Saving Money By Tara Struyk
Have you ever settled on a new exercise program, only to get a bad cold a few days in and happily throw yourself on the couch, relieved to have a handy excuse? Excuses must be human nature; I know I usually make them when I'm facing something that’s new, that's hard, or that I just don’t enjoy. And I’ve certainly made excuses when it comes to money.
In the years that I’ve been writing about personal finance and investing, I’ve also heard my fair share of excuses, mostly from readers who don’t agree with my advice. The problem is, unlike good financial habits, excuses are easy to come by, even though most of them just don’t stand up to reason. Check out some of the ones I’ve heard most frequently so far.
How To Make Strategic Cash Bucketing Work For You
Last Edited Sep 16, 2026| Angelena Mascilli
Cash bucketing – or categorizing your funds based on specific expenses or goals – can help you organize your financial life.
Cash and other liquid assets may be the ideal place for buckets of money that you may need to access soon to cover expenses or capitalize on new investment opportunities.
3 Savings Moves To Make Post-Fed Rate Hike
By Matt Richardson September 17, 2026 CBS News MoneyWatch: Managing Your Money
With interest rates rising again, savers will want to take certain steps now to take advantage.
Savers on Thursday woke up to a new financial climate marked by the first interest rate hike from the Federal Reserve in more than three years. Now at a range between 3.75% and 4.00%, a new, higher federal funds rate is expected to lead to even higher rates for savers than they've already been accustomed to in recent years. And while that change will look different based on the account type and the bank in question, savers are undoubtedly now entering a more profitable period, especially if the Fed proceeds with another interest rate hike when it meets again in October.
5 Steps To Master Your Money
Simple strategies to help fund your future.
Fidelity Viewpoints
Key takeaways
Define clear goals and make a plan to help guide your financial decisions.
Set up automatic transfers to help boost your savings and keep you on track.
Build up your emergency savings to cover unexpected essential expenses
Debt management: How To Avoid Common, But Costly, Money Mistakes
May 27, 2026 Malena de la Fuente and Aaron Goodman
Americans are carrying more debt than ever before. Total household balances now approach $19 trillion, reflecting a steady increase over the past decade.1 In 2025, millennials in their mid-30s held roughly twice as much nonhousing debt—including student loans, auto loans, and credit card debt—as baby boomers did at a similar age.2
9 Ways Retirement Will Be Different in 2026
By Cameron Huddleston and Deirdre Shesgreen, AARP
How changes to Social Security, Medicare, 401(k) contributions and more will affect your finances
Retirement may seem like the most stable period of your life, with no work demands, no kids to cart around and lots of free time. But this dynamic new chapter comes with its own twists and turns. Your lifestyle, expectations and finances continue to change. And in 2026, big shifts are coming — from Social Security payments and Medicare expenses to how you save and spend.
What To Do With A Windfall
Considerations to help you make the most of your good fortune.
Fidelity Wealth Management
Key takeaways
Even though it may be tempting to treat yourself right away, it's important to step back and thoughtfully assess your full financial picture.
Taxes and other costs may impact the net value of your windfall.
Consider how you may want to change your asset allocation, giving strategy, and estate plan.