Physical Gold vs. Digital Gold: Which Is the Ultimate Safe Haven?
Physical Gold vs. Digital Gold: Which Is the Ultimate Safe Haven?
Published: 05-20-2026
Gold is trading at approximately $4,500 per troy ounce as of May 20, 2026 [World Gold Council]. However, the debate about physical gold vs digital gold matters more than most investors realise — because not all of these products are the same thing. Both show up on a brokerage statement with a dollar value attached. But what you actually own — what you hold, what you control, what survives a real crisis — is a very different story. This isn’t a debate about returns. It’s a debate about what “safe haven” actually means.
Key Takeaways
Gold ETFs, futures, and tokenized products track the gold price — but they are paper claims, not gold. In a crisis, that distinction can matter enormously.
Physical gold carries no counterparty risk. No custodian, fund, or institution stands between you and your asset.
Professional vault storage eliminates the storage problem. You can own allocated physical gold with the same convenience as a brokerage account.
What Counts as “Digital Gold”?
The term gets used loosely. Here, specifically, is what it covers.
Gold ETFs — funds like SPDR Gold Shares (GLD) or iShares Gold Trust (IAU) — hold physical gold in vaults on behalf of shareholders. However, you own shares in the fund, not the gold itself. You can’t take delivery of your pro-rata bar. When you sell, you receive dollars, not metal [World Gold Council].
Gold futures and options, meanwhile, are contracts on the price of gold. No metal changes hands in most cases. Instead, you own a legal claim that expires — useful for hedging or speculation, but nothing more.
Tokenized gold products like Paxos Gold (PAXG) and Tether Gold (XAUt) — the most traded examples — represent gold positions on a blockchain. In theory, each token equals one troy ounce in a vault. In practice, however, the infrastructure, regulation, and redemption mechanics vary considerably between providers. Moreover, in most cases, retail investors cannot easily redeem for metal.
Gold savings accounts from banks and fintech platforms, similarly, let you buy “fractional gold” in paper form. These are typically unallocated — meaning you hold a proportional claim against a pool, not a specific bar.
All of these are paper claims on gold. Their value is derived from gold. But they are not gold.
What Physical Gold Actually Is
Physical gold — coins, bars, and rounds — is the metal itself.
A one-ounce American Gold Eagle, for example, isn’t a claim on anything. It doesn’t depend on a counterparty staying solvent, a blockchain functioning, or a custodian keeping its license. Specifically, it contains a guaranteed troy ounce of fine gold — alloyed with silver and copper for durability, with every grain of its gold content backed by the US Mint [US Mint]. Furthermore, gold in that form has been accepted as money for 5,000 years.
That distinction isn’t philosophical. It’s structural. And it matters most precisely when markets are under the most stress.
When Does the Physical Gold vs Digital Gold Difference Actually Matter?
In March 2020, COVID uncertainty hit markets hard. As a result, gold ETFs sold off alongside equities as investors scrambled for cash. GLD dropped roughly 13–14% from its February high. Physical gold premiums at dealers rose at the same time — in other words, the metal became harder to acquire even as its paper price fell [World Gold Council].
April 2025 saw the same dynamic, more severely. Paper gold sold off on margin calls and forced liquidations. Consequently, physical premiums widened to levels not seen in decades.
This is the paper vs. physical divergence. Paper gold responds to financial market signals — including forced selling by leveraged investors with no fundamental view on gold. Physical gold, by contrast, responds to actual monetary demand. As a result, the two can split apart exactly when you need your safe haven to hold.
There is also a structural issue with ETFs. When you hold one, you hold shares in a trust that relies on authorized participants, custodians, and the continuous functioning of the financial system. In a genuine crisis — a banking freeze, a settlement failure, a custody dispute — your recourse runs through those same institutions. Physical gold, however, has no counterparty. No one can default on a bar you possess.
What Does Digital Gold Actually Get Right?
Gold ETFs aren’t a bad product. For most investors, most of the time, they work fine.
They’re liquid and cheap to trade. Additionally, they sit easily inside brokerage accounts and retirement vehicles. GLD charges 0.40% annually [SPDR Gold Shares] — low friction for a tactical position. For a trader hedging equity risk over three to six months, therefore, an ETF is the right tool.
There are no storage decisions to make. There’s no insurance to arrange, and no logistics to manage.
Furthermore, ETFs held in tax-advantaged accounts offer benefits physical gold simply can’t match. That’s a genuine structural advantage for long-term retirement investors who prioritise tax efficiency over direct ownership.
In summary, the honest case for digital gold is this: it’s efficient, accessible, and purpose-built for financial market exposure.
Why Does Physical Gold Win Long-Term?
Physical gold’s advantages aren’t tactical. They’re structural. Specifically, four properties set it apart.
First, ownership is direct. No custodian sits between you and your wealth. In an era of rising financial surveillance and capital controls, that matters more than it used to.
Second, supply is genuinely finite. A government can print more dollars — it cannot, however, mine more gold on demand. Roughly 3,661 tonnes are produced globally each year, against an above-ground stock of approximately 216,000 tonnes [World Gold Council]. That ratio barely moves.
Third, gold exists outside the financial system entirely. Central banks hold over 36,000 tonnes collectively — not out of sentiment, but because gold carries no one else’s liability [IMF / World Gold Council]. It cannot be frozen, inflated away, or rehypothecated by someone else’s decision. When financial systems seize, therefore, gold doesn’t.
Fourth, it is portable, private, and sovereign. France repatriated its gold from US custody between mid-2025 and early 2026. As a result, central banks act on the same logic retail investors often forget: there is a meaningful difference between owning gold and owning a claim on it.
Do You Have to Choose Between Convenience and Real Ownership?
The most common objection to physical gold is straightforward: storage.
Fortunately, GoldSilver’s vault storage program removes that friction entirely. Investors own allocated physical gold — their own specific bars and coins — stored in highly secure, insured vaults with institutional-grade infrastructure.
InstaVault, GoldSilver’s flagship product, makes this process straightforward. You can buy and hold allocated physical gold and silver at low storage rates. In addition, you can take physical delivery whenever you choose. Your metal is segregated, insured, and audited — not pooled with other clients, and not held on a financial institution’s balance sheet.
As a result, the old trade-off no longer holds. Genuine physical ownership and operational convenience are no longer mutually exclusive.
Which Type of Gold Is Right for You?
Why Are Central Banks Buying So Much Gold in 2026?
Why Are Central Banks Buying So Much Gold in 2026?
Published: 10-05-2026 De-dollarization is the gradual shift by central banks away from holding the US dollar as their dominant reserve asset. In practice, that usually means adding gold and other currencies instead. In 2026, this shift stopped being a theory investors had to take on faith.
Specifically, it is now a documented pattern, visible in the World Gold Council’s own survey data and in the IMF’s own reserve statistics.
Central banks bought a reported 289 tonnes of gold in the second quarter of 2026. That is the World Gold Council’s largest quarterly figure on record. Meanwhile, the dollar’s share of global reserves fell to 56.7%, per IMF data. A record 45% of reserve managers surveyed by the WGC in 2026 said they plan to add more gold. They expect to do so within the next year.
Key Takeaways:
Central banks bought a record 289 tonnes of gold in Q2 2026 (World Gold Council), keeping up a four-year run near 1,000 tonnes a year, though the WGC’s own 2026 forecast is a more moderate 850 tonnes.
The dollar’s share of global reserves fell to 56.7% in Q2 2026 (IMF COFER data), down from a peak above 72% in 2001.
A record 45% of central banks plan to add gold in the next 12 months (WGC 2026 survey); 89% expect global holdings to keep climbing.
The mechanism is specific: the 2022 freezing of $300 billion in Russian reserves put a line item on every reserve manager’s risk model that used to be theoretical.
Most reserve managers target a 15-20% gold allocation, not open-ended accumulation. This is a diversification program with a destination, not a flight from the dollar.
Why Does This Matter Right Now?
GoldSilver has covered the basics before: is the dollar losing its reserve currency status and what de-dollarization actually means. This piece instead focuses on what’s new in the 2026 data.
For individual investors, the useful signal here is less about any single number. It is more about who is buying. This is not retail money chasing a price move. Instead, it is sovereign balance sheets executing a multi-year plan. That plan has nothing to do with what gold did last Tuesday.
As of early October 2026, gold trades in the mid-$4,100s, down roughly 5% from its September record, per GoldSilver’s own live price charts. Silver sits in the low $60s, down about 9% from its own September peak. That said, it would be easy to read that pullback as evidence the de-dollarization story has cooled off.
The institutional data says the opposite: official-sector buying did not slow when prices did. That gap, between what price charts show and what central bank balance sheets show, is the actual story worth understanding.
Why Are Central Banks Buying Gold Right Now?
The short answer is reserve diversification driven by geopolitical risk, not a bet on next quarter’s gold price. As of mid-2026, central banks had averaged roughly 1,000 tonnes of gold purchases a year for four consecutive years. That is a pace the market had not seen since the era of fixed exchange rates.
The World Gold Council fielded its 2026 Central Bank Gold Reserves Survey between February and May, with a record 76 central banks responding. The survey found that 93% of reserve managers now hold some gold, up from 81% a few years earlier, and that 84% expect gold to make up a larger share of their reserves five years from now.
The Council’s own head of central banks described demand as remaining on an upward trajectory. Separately, 68% of central banks said in March 2026 they planned to increase gold holdings that year, up from 62% the year before.
Individual countries tell the same story at different scales. For example, Poland added 82 tonnes in 2026, working toward a stated 700-tonne target. Similarly, Turkey added 45 tonnes in January alone, pushing its reserves to 565 tonnes.
China’s central bank, meanwhile, reported a 20-tonne addition in July. That was its largest monthly rise since late 2023, a pattern GoldSilver covered in our analysis of China’s gold imports versus its official buying.
It was also its 21st straight month of reported buying, taking disclosed holdings to roughly 2,366 tonnes, or about 8% of its foreign exchange reserves. None of these are retail-sized moves. None are reversible in a weekend the way a trading position is.
Is the Dollar Really Losing Its Reserve Currency Status?
Not in the way that phrase usually implies. The dollar remains the dominant reserve and trade-settlement currency by a wide margin. Nothing in the 2026 data shows an abrupt handoff to a rival currency. Instead, what the data shows is narrower and more precise: a multi-decade decline in concentration. Specifically, the IMF’s own reserve data puts the dollar’s share of allocated reserves at 56.7% at the end of Q2 2026. That is down from 57.2% in Q1, and down from a peak above 72% back in 2001. The World Gold Council’s own central bank survey confirms the same pattern from the buying side.
The euro, by comparison, has held roughly steady near one-fifth of reserves over the same stretch. Meanwhile, the gains have mostly gone to a broader group of currencies, and to gold itself. In fact, gold’s share of global reserves has nearly doubled over the past quarter-century.
Notably, conflating “losing reserve share” with “losing reserve status” is the most common error in this topic. The difference is worth being precise about: a household that moves a third of its savings into a mix of assets has not declared bankruptcy. It has simply diversified.
What Does the 2022 Russian Reserve Freeze Have to Do With Gold?
This is the mechanism that gets skipped in most coverage of this topic. Naming it precisely matters more than simply repeating the word “geopolitics.” After the invasion of Ukraine, Western governments froze roughly $300 billion of Russia’s central bank assets.
In doing so, they demonstrated something specific: a sovereign dollar or euro reserve is not unconditionally safe. Instead, it is safe only on the condition of that country’s relationship with the government whose banking system holds the asset.
For the United States itself, a reserve of US Treasuries carries no such risk. However, for every other country, the freeze changed the calculation. It converted an abstract tail risk into a specific, dated, quantified event.
Reserve committees now model that risk explicitly, rather than assume it away. Gold held in a country’s own vault, by contrast, is simply a claim on a physical object and a domestic legal system. It does not depend on another government’s goodwill.
How Much Gold Are Central Banks Actually Buying, and Is It Slowing Down?
As of early October 2026, the most recent full-quarter figure is Q2 2026’s reported 289 tonnes. That is a record for a single quarter, according to World Gold Council data. Zoom out to the annual picture, though, and the pattern is even clearer (Chart 1). Per World Gold Council data, central banks averaged just 473 tonnes a year between 2010 and 2021.
Every year since 2022 has run two to three times that average. The Council’s own full-year forecast for 2026 continues the trend.
The World Gold Council’s Q3 2026 report is expected in early November. It will be the next real test of whether the Q2 pace held through the autumn price correction.
Even so, one thing is already clear from the survey data: reserve managers are not treating the recent pullback as a reason to pause.
TO READ MORE: https://goldsilver.com/industry-news/article/why-central-banks-buying-gold-2026/
BRICS Is Hoarding Gold. Here’s What It Means for Your Portfolio.
BRICS Is Hoarding Gold. Here’s What It Means for Your Portfolio.
Most news coverage of the BRICS gold story gets one thing wrong: it treats this as political drama rather than a portfolio signal.
It asks whether a BRICS currency will succeed. Whether it’ll topple the dollar. Whether the summit announcements are serious or just rhetoric. Those are interesting questions. However, they’re also the wrong ones if you’re trying to protect and grow your savings.
Key Takeaways
The mechanism, not the headline: BRICS gold buying matters not because a new currency is imminent. It matters because it reduces demand for US Treasuries at the margin — slowly eroding the dollar’s reserve role and the purchasing power of dollar savings.
Physical over paper: The hedge you want for a dollar debasement scenario is physical gold and silver. ETFs and futures carry counterparty risk in the exact conditions you’re protecting against.
Position before the headline: BRICS central banks are building reserves now, not after the announcement. The time to position is while the shift is still being dismissed.
Silver complements gold: Silver offers the same monetary properties as gold with higher volatility and a lower entry price per ounce. It’s a natural complement to a gold core position.
The more useful question is this: If the world’s largest emerging economies are buying gold as a reserve asset, what does that mean for the purchasing power of your dollars over the next decade?
That question has an answer. Let’s work through it.
What’s Actually Driving the BRICS Gold Accumulation?
Start with the structural reality, because the portfolio implication flows directly from it.
The global monetary system rests on a simple but fragile premise. At its core, the US dollar is the world’s reserve currency. Global trade is priced in dollars. Foreign central banks hold dollar-based assets — primarily US Treasuries — as their primary reserves.
This arrangement gives the United States something no other country has. It can run persistent deficits, issue debt at scale, and effectively export inflation simply by printing money.
BRICS+ nations have spent years building an alternative to that arrangement. The group now includes Brazil, Russia, India, China, and South Africa, plus six new full members admitted in 2024 and 2025: Egypt, Ethiopia, Iran, the UAE, Indonesia, and Saudi Arabia.
Together, they have built settlement systems that bypass SWIFT, bilateral trade agreements in local currencies, and — most critically — a systematic accumulation of physical gold at the central bank level.
As we covered last month, central banks globally bought 1,037 tonnes of gold in 2023. That was the second-highest annual total on record. Moreover, they exceeded that pace in 2024 with 1,045 tonnes [World Gold Council, Gold Demand Trends Full Year 2023]. China’s People’s Bank of China added gold for 18 consecutive months through April 2024.
It then paused for six months as prices hit records, resumed in November 2024, and has continued buying since [Bloomberg, December 2025]. Russia has effectively replaced its dollar reserves with gold. India’s Reserve Bank repatriated 100 tonnes from the Bank of England in spring 2024, then a further 102 tonnes by year-end.
The common thread is simple. Gold cannot be frozen. It cannot be sanctioned. It belongs to whoever holds it physically. No government can revoke that.
Does a Gold-Backed Currency Need to Succeed for This to Matter?
No. And that’s the point most commentators miss.
The BRICS proposal for a gold-backed trade currency is usually framed as binary. Either it replaces the dollar, or it fails and nothing changes. Neither is right.
A gold-backed settlement unit doesn’t need to replace the dollar. It just needs to exist as a credible option for bilateral trade between willing parties. If China and Saudi Arabia can settle oil in a unit partly backed by gold, they have one less reason to hold US Treasuries. As a result, demand for dollar-based debt falls at the margin. The US government’s ability to borrow cheaply becomes slowly constrained.
That’s the mechanism. Not a dramatic collapse — but a slow tightening of the conditions that make dollar dominance sustainable.
The dollar’s share of global foreign exchange reserves has already fallen from roughly 72% in 2001 to around 58% today [IMF Currency Composition of Official Foreign Exchange Reserves (COFER), 2024]. That 14-point decline happened quietly over two decades. It didn’t make front pages. Instead, it showed up as higher consumer prices, a more constrained Federal Reserve, and a steady erosion of dollar purchasing power.
That’s how these shifts work. Not with a bang.
Why Hasn’t Your Financial Advisor Mentioned Any of This?
Because they’re not paid to.
The financial advisory industry is built around US market assets. Fee structures, product shelves, and compliance frameworks all centre on dollar-based investments. Recommending that a client move a meaningful portion of their portfolio outside that system is awkward at best. At worst, it opens conversations advisors would rather avoid.
This isn’t a conspiracy. It’s an incentive structure. Moreover, it creates a gap that a well-constructed portfolio can exploit.
The answer isn’t to abandon conventional assets. Instead, it’s to add a layer of physical gold and silver that sits entirely outside the dollar system. Not a gold ETF. Not a gold miner stock. Metal you own outright, with no counterparty between you and the asset.
How Should You Actually Position for This?
TO READ MORE: https://goldsilver.com/industry-news/article/brics-is-hoarding-gold-heres-what-it-means-for-your-portfolio/
Dollar Dominance Is Fading. Gold and Silver Are Paying Attention
Dollar Dominance Is Fading. Gold and Silver Are Paying Attention
The U.S. dollar and gold have a well-documented inverse relationship — and right now, with gold at $4,690 and silver at historically unprecedented price levels, that relationship is doing exactly what it’s supposed to do. The dollar is weakening structurally. Precious metals are the direct beneficiary.
Most investors tracking gold and silver watch inflation, interest rates, and geopolitical headlines. All of those matter. But they all route through the same upstream variable: the dollar. Understanding why is the difference between reacting to price moves and anticipating them.
Key Takeaways
The U.S. dollar’s share of global foreign exchange reserves has fallen from ~71% in 2000 to ~57% today — a structural decline that directly benefits gold and silver.
When the DXY dropped roughly 10–11% in the first half of 2025, gold broke to successive all-time highs and silver gained approximately 147% for the year.
Central banks bought gold at a 70-year high across 2022, 2023, and 2024 — the clearest institutional signal that dollar dominance is in long-term decline.
What Is Dollar Dominance — and How Does It Affect Gold and Silver Prices?
Dollar dominance is the U.S. dollar’s outsized role in the global financial system. Since the Bretton Woods agreement in 1944, the dollar has been the world’s primary reserve currency. Most international trade, debt, and commodity pricing — including gold and silver — is denominated in USD.
When the dollar is strong, it takes fewer dollars to buy an ounce of gold — that suppresses price. When the dollar weakens, the reverse happens. It’s a relationship that has held through every major market cycle for the past half-century.
What’s changed is the dollar’s grip itself. Its share of global foreign exchange reserves has fallen from approximately 71% at the turn of the century to roughly 57% today — its lowest level in decades [IMF Currency Composition of Official Foreign Exchange Reserves (COFER), Q4 2025]. That structural decline is the backdrop against which every gold and silver price move should be read.
How Does Dollar Strength Drive Gold and Silver Prices?
The mechanics are direct. Gold is priced in U.S. dollars globally. When the dollar rises, gold becomes more expensive for foreign buyers — demand falls, price follows. The reverse is equally true, and the data bears it out consistently.
Most gold analysts track the U.S. Dollar Index (DXY), which measures the dollar against a basket of six major currencies. In the first half of 2025, the DXY dropped roughly 10–11% — its steepest first-half decline in over 50 years. Gold surged through its previous all-time high and kept climbing into 2026 [RBC Wealth Management, U.S. Dollar in Transition, 2025].
This isn’t coincidental. Gold doesn’t pay interest, doesn’t carry counterparty risk, and can’t be printed. When the currency it’s priced in loses purchasing power, gold’s real value stays the same — only the number of dollars required to buy it changes. That’s not speculation. That’s arithmetic.
Silver responds to the same dynamic, but more violently. Its smaller market and industrial demand component mean bigger moves in both directions.
Why Is the Dollar the #1 Signal — and Not Just One Factor Among Many?
Precious metals investors track inflation, interest rates, geopolitical instability, central bank policy. But the dollar sits above the rest because nearly every other variable routes through it first.
Take inflation. Rising prices erode the dollar’s purchasing power and push investors toward hard assets. But the specific mechanism runs through real interest rates — Treasury yields minus inflation. When inflation exceeds bond yields, real rates turn negative.
Holding dollars becomes punitive. Gold, which carries no yield but also no debasement risk, becomes comparatively attractive.
Geopolitical stress used to trigger a “flight to safety” into dollars. That reflex has weakened as confidence in U.S. fiscal credibility has declined. Increasingly, instability flows straight into gold — bypassing the dollar. That’s a structural change.
Watch the dollar. Everything else is downstream from it.
What Happens to Silver When Dollar Dominance Fades?
Silver is the leveraged version of the same thesis. When the dollar weakens, silver doesn’t just follow gold — it typically outpaces it.
In 2025, silver gained approximately 147% over the course of the year as dollar dominance came under sustained pressure [Silver Institute, World Silver Survey 2026]. At $87.71, the white metal is trading at levels with no historical precedent outside the 2025–2026 rally.
That price reflects two forces at once: the monetary trade — a weaker dollar, rising inflation expectations, eroding reserve currency confidence — and surging industrial demand from solar panels, EVs, and electronics.
That dual demand base is what separates silver from most assets. The energy transition keeps industrial demand growing, which raises silver’s structural price floor. Dollar weakness then hits a metal with a shrinking supply cushion. Neither driver needs the other to work — but when both are present simultaneously, silver tends to move fast.
Silver’s percentage gains during dollar stress have historically exceeded gold’s. Both metals respond to the same signal — silver just responds harder.
What Are the Long-Term Implications of a Declining Dollar for Gold and Silver?
The Fed’s Retreat Exposes the Real Monetary Reset
The Fed’s Retreat Exposes the Real Monetary Reset
Miles Harris: 10-15-2026
The landscape of American fiscal policy is undergoing a significant transformation, marked recently by the appointment of Judy Shelton as a counselor at the United States Treasury.
This move signals a potential shift in how the nation views its currency, its debt, and its role in an increasingly digital global economy.
Shelton, a long-time advocate for monetary stability and sound money principles, brings a vision that challenges the traditional dominance of the Federal Reserve. Her focus centers on a transition toward a more decentralized, programmable financial system that leverages modern technology while grounding it in the historical reliability of tangible assets.
Central to this vision is a move away from the heavy-handed influence of the Federal Reserve over the money supply. Instead, the proposed framework emphasizes a system of programmable, collateral-backed money.
This includes the integration of stablecoins and tokenized bank deposits, which allow for faster and more transparent transactions within the private sector. By fostering an environment where private digital money can flourish, the goal is to create a more resilient financial infrastructure that does not rely solely on central bank interventions. This approach seeks to modernize the dollar’s utility without compromising the fundamental principles of market-driven value.
One of the most striking aspects of Shelton’s proposal is her firm stance against Central Bank Digital Currencies, or CBDCs.
While she rejects the idea of a government-issued digital currency that could increase federal oversight of private transactions, she remains a strong proponent of private-sector digital innovation.
To ensure the stability of these private instruments, she suggests a model where digital money is potentially backed by gold-linked Treasury bonds.
This unique mechanism would not only provide a stable anchor for the digital dollar but also stimulate ongoing demand for United States debt by offering investors a more secure and attractive form of collateral.
The importance of collateral has become paramount as the Federal Reserve continues to shrink its balance sheet. In the current economic climate, the repo markets—where financial institutions trade short-term debt for cash—have become the heartbeat of the financial system.
Shelton’s focus on using high-quality collateral, particularly U.S. Treasuries and gold, highlights a shift toward a system where the “quality” of money is just as important as its quantity. By linking digital money creation to these high-value assets, the financial system can maintain liquidity while reducing the volatility often associated with unbacked fiat currencies.
This domestic shift is occurring against a backdrop of complex international monetary dynamics, particularly involving China. As China moves to internationalize its own currency through gold reserves and alternative payment systems, the global monetary order is becoming increasingly multilateral.
Interestingly, despite their competitive relationship, both the United States and China appear to be converging on a similar structural path. Both nations are recognizing the necessity of enhanced collateral-backed financial frameworks to maintain economic influence. This suggests that the future of global finance may be defined by a race to see which nation can best integrate traditional assets into a digital-first economy.
Ultimately, we are witnessing the resurgence of gold as a critical monetary anchor and reserve asset.
In a world characterized by fluctuating exchange rates and intense capital flows, gold provides a neutral ground that can help balance the conflicting pressures of national monetary autonomy and international trade.
Shelton’s vision suggests that by embracing this “new” form of stability, the United States can lead the way into a multilateral monetary era. This transition promises to redefine the relationship between government debt, private innovation, and the fundamental nature of money itself.
0:00 Judy Shelton Joins the US Treasury
1:08 The Fed Is Stepping Back
2:55 The Collateral Machine Steps Forward
4:36 Stablecoins - a Treasury Demand Engine
6:41 Gold Returns Inside the Financial System
8:48 China, Bessent and a New Bretton Woods
11:09 Gold and International Payments
13:30 What the New Monetary Architecture Means
What Backs the US Dollar? Not Gold Not Silver
What Backs the US Dollar? Not Gold Not Silver
What Backs the US Dollar?
So what backs the US dollar, if not gold or silver? The answer has been the same since August 15, 1971: nothing physical. The dollar is a fiat currency — from the Latin fiat, meaning “let it be done.” Its value rests on a government declaration that it is legal tender. Beyond that, it rests on trust.
Key Takeaways
The US dollar has not been backed by gold since August 15, 1971 — the date President Nixon formally ended dollar-to-gold convertibility under the Bretton Woods system.
Since leaving the gold standard, the dollar has lost approximately 87% of its purchasing power [Bureau of Labor Statistics, CPI-U]. As a result, M2 money supply has grown from ~$630 billion in 1971 to over $22 trillion in 2026 [Federal Reserve H.6 Release] — a 35x expansion.
Central banks purchased a net 244 tonnes of gold in Q1 2026 alone [World Gold Council, Gold Demand Trends Q1 2026]. Consequently, the world’s largest reserve managers are reducing dollar exposure — a shift that accelerated after the 2022 freezing of approximately $300 billion in Russian central bank reserves [US Congressional Research Service].
That trust, however, has real and measurable consequences. As of Q3 2025, the dollar accounted for approximately 57% of global foreign exchange reserves [IMF Currency Composition of Official Foreign Exchange Reserves (COFER), Q3 2025]. No other currency comes close. Moreover, the dollar remains the default unit for international trade, oil pricing, and sovereign debt.
However, trust — unlike gold — has no physical limit on its supply. That distinction is at the heart of everything that follows. How the dollar went from redeemable metal to redeemable promise is one of the most consequential financial shifts of the past century.
When Did the Dollar Leave the Gold Standard?
For most of American history, dollars tied directly to precious metals. Under the classical gold standard, anyone could exchange paper dollars for a fixed weight of gold at any bank.
The Bretton Woods system, established at the 1944 conference in Bretton Woods, New Hampshire, extended this logic internationally. Specifically, foreign governments could exchange dollars for gold at $35 per ounce. The dollar was, effectively, as good as gold for international trade.
That ended on August 15, 1971. President Richard Nixon announced that the US would no longer honor foreign requests to convert dollars to gold.
The reason was straightforward: America spent far more than it produced. Financing the Vietnam War and Great Society programs simultaneously had drained the gold reserves. Furthermore, foreign nations — France most prominently — were accelerating their redemptions. As a result, the US simply could not honor the commitments.
Nixon called it a “temporary” measure. Fifty-five years later, however, the gold window has never reopened.
What Did Removing the Gold Standard Actually Do?
Before 1971, the gold standard was a hard ceiling on money creation. The government could not print dollars faster than it could acquire gold to back them. Remove the ceiling, and the supply expands. Indeed, that’s exactly what happened.
M2 money supply grew from approximately $630 billion in 1971 to over $22 trillion in 2026 [Federal Reserve H.6 Money Stock Measures, March 2026] — a 35x increase in just over five decades. For a deeper look at why this pattern repeats across history, see our analysis of why fiat currencies fail.
The purchasing power math is just as stark. According to the Bureau of Labor Statistics’ Consumer Price Index, a 1971 dollar buys roughly 13 to 14 cents worth of goods today [BLS CPI-U, 2026]. For example, a $100 purchase in 1971 costs nearly $800 now.
In addition, gas at 36 cents a gallon now costs over $3.50. Similarly, a median home at $24,000 in 1971 now sells for over $400,000 [US Census Bureau, New Residential Sales].
Those prices didn’t go up. The dollar shrank.
CHART: LINK https://goldsilver.com/industry-news/article/what-backs-the-us-dollar-not-gold-not-silver/
What Gives the Dollar Its Value Now?
Three structural pillars replaced gold as the foundation of dollar demand. However, none of them limits how many dollars can be created. That’s the constraint gold used to provide.
The petrodollar system. From 1974, the US reached agreements with Saudi Arabia and other oil producers to price oil exclusively in dollars.
As a result, every country that imports oil — which is nearly every country — needs dollars to do it. That created sustained global demand for the currency. In recent years, the arrangement has frayed as BRICS nations pursue alternatives, but it remains a significant structural support.
US Treasury debt as a global reserve asset. Foreign governments and central banks hold trillions in US Treasury bonds as their primary reserve asset. It’s self-reinforcing: you need dollars to buy Treasuries, and you hold Treasuries because you need a place to park dollars. The long-term cost of that arrangement is visible in the dollar’s 87% purchasing power decline since 1971.
Network effects and institutional inertia. The dollar runs through global trade contracts, commodity pricing, SWIFT payment infrastructure, and international debt. Consequently, unwinding that takes decades, not quarters. De-dollarization is real — it’s just slow.
Is the Dollar Losing Its Reserve Currency Status?
Yes — but gradually. The dollar’s share of global foreign exchange reserves has fallen from approximately 72% in 2001 to about 57% in Q3 2025 [IMF COFER, Q3 2025]. That’s 15 percentage points over 25 years. In other words, not a collapse — a slow drift.
TO READ MORE: https://goldsilver.com/industry-news/article/what-backs-the-us-dollar-not-gold-not-silver/
We’re in a “WARTIME ECONOMY” & GOLD Is a National Security Asset | Graham Summers & Michelle Makori
We’re in a “WARTIME ECONOMY” & GOLD Is a National Security Asset | Graham Summers & Michelle Makori
Miles Franklin Media: 10-9-2026
Michelle Makori, President & Editor-in-Chief of Miles Franklin Media, speaks with Graham Summers, President and Chief Market Strategist at Phoenix Capital Research and Macroeconomics Fellow at the Homeland Defense Institute, about why he believes the U.S. is already operating on a wartime economic footing as its economic competition with China reshapes national security, critical minerals, financial markets, and gold.
Summers explains why gold has moved to the forefront of U.S. national security, whether Washington could be quietly accumulating gold as China builds its reserves, and why policymakers may be reconsidering gold’s role in the monetary system.
He also examines the U.S. debt and Treasury market, the dollar’s purchasing power, central bank gold buying, and why government policy could drive a repricing across gold, Bitcoin, critical minerals, and other strategic assets.
Summers also explains why he believes the stock market itself has effectively become a matter of national security and what this shifting economic environment could mean for investors focused on hard assets, monetary stability, and wealth preservation.
In this episode of The Real Story:
Why gold is becoming a national security asset
Whether the U.S. could be quietly accumulating gold
How economic competition with China is reshaping U.S. policy
Why the dollar could be reassociated with gold
What could drive the next repricing in gold and Bitcoin
00:00 Coming Up
02:02 Introduction
03:32 Defining Wartime Economy
05:18 Executive Orders And Minerals
08:55 Inside National Security Briefings
11:40 Economic Defense Unit Explained
15:04 Deal Examples And Mining Push
18:10 Sponsor Break
19:10 Why The Urgency Now
24:37 Gold As Sanctions Weapon
30:05 Gold Backed Bonds Theory
35:24 Treasury Market Stress
44:22 China Gold And US Response
45:16 Trial Balloons Framework
46:04 Covert Gold Buying Tools
50:10 Fort Knox Audit Debate
51:00 Gold Revaluation Talk
53:12 Gold National Security Lens
55:32 Dollar Dominance Reality Check
58:48 China Gold Yuan Theory
01:01:30 Silver Critical Mineral Role
01:02:27 Venezuela Weapons Example
01:04:37 Silver Price Manipulation
01:07:23 Stocks As National Security
01:12:13 Everything Bubble Explained
01:15:10 Wartime Portfolio Strategy
01:20:12 Bipartisan Wartime Momentum
01:23:37 Homeland Defense Institute
Historic Gold Rush Reprices Global Debt
Historic Gold Rush Reprices Global Debt
Kinesis Money: 10-8-2026
In this week's Live from the Vault, Andrew Maguire details how central banks swapping dollars for physical gold at an unrivalled pace are quietly forcing a repricing of global debt — and why this gold rush marks something far bigger than a market rally.
As the Fed remains the last major institution still sitting on gold valued at a fraction of its true market price, Andrew outlines why he sees this gold rush not as a rally, but as the opening chapter of a fundamental restructuring of the monetary order
Historic Gold Rush Reprices Global Debt
Kinesis Money: 10-8-2026
In this week's Live from the Vault, Andrew Maguire details how central banks swapping dollars for physical gold at an unrivalled pace are quietly forcing a repricing of global debt — and why this gold rush marks something far bigger than a market rally.
As the Fed remains the last major institution still sitting on gold valued at a fraction of its true market price, Andrew outlines why he sees this gold rush not as a rally, but as the opening chapter of a fundamental restructuring of the monetary order.
Timestamps:
00:00 Start
02:17 Why central banks are no longer just buying gold — they are revaluing it
07:44 The Hong Kong exchange launch — why it changes gold pricing permanently
13:02 Gold has overtaken US Treasuries as the world's top reserve asset
19:28 Why the Fed is the last institution standing between gold and a full repricing
25:11 How rising gold revalues sovereign balance sheets — what that means for debt
31:44 Silver's structural deficit — why it is yet to reflect the same revaluation
38:07 Why the current dip is being absorbed by the same buyers driving the gold rush
45:52 The path from $42 Treasury gold to market price — who gets caught short
Why Did Treasury Just Hire the Architect of the Gold-Backed Bond?
Why Did Treasury Just Hire the Architect of the Gold-Backed Bond?
by Phoenix Capital Research Tuesday, Oct 06, 2026 - 8:20
In late September, Treasury Secretary Scott Bessent brought Judy Shelton into his office as Counselor to the Secretary. Most of the coverage treated it as a personnel note about a longtime gold advocate. I think the more useful question is a simple one: why would Treasury want her, and why now? Start with the problem Bessent is trying to solve.
Treasury has to sell trillions of dollars in long-term debt to finance a national debt that has passed $40 trillion.
Investors are demanding more to hold it. On Monday, the 30-year Treasury yield hit 5.7%, its highest level since 2002. Treasury expanded its bond buyback program in August to bring those yields down, and it has had little lasting effect.
The traditional fixes for this problem run through the Federal Reserve: the Fed buys bonds, or it caps long-term yields directly. Both options hand the problem to the Fed, and both tend to weaken the dollar.
Judy Shelton has spent more than a decade designing a different fix. One that runs through Treasury.
In a 2012 paper for the Cato Journal, she proposed Treasury Trust Bonds: zero-coupon bonds that holders could redeem at maturity for either dollars or a fixed amount of gold. More recently, she has advocated a 50-year Treasury bond backed by U.S. gold reserves. Her argument is that investors would accept a lower interest rate in exchange for the gold option, which would reduce the government’s borrowing costs.
That is a very specific skill set. And it happens to match a very specific problem.
Now look at the order in which things have happened.
First, President Trump personally named gold a critical mineral in Executive Order 14241. Then Treasury audited Fort Knox and valued America’s gold reserves at more than $1 trillion. Then Treasury added gold to its Iran sanctions. And now the country’s leading designer of gold-convertible debt is working in the Secretary’s office
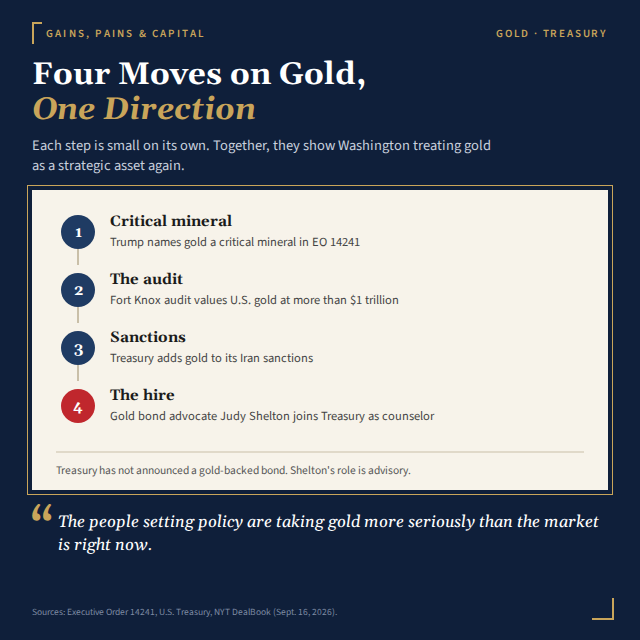
If you were preparing to use gold as part of the government’s financing toolkit, those are the steps you would take: establish its strategic importance, verify what you own, and bring in someone who knows how to structure it.
I want to be careful here. Treasury has not announced or proposed a gold-backed bond. Shelton’s role is advisory. Bessent himself said this summer that gold doesn’t determine the value of the dollar. It is entirely possible that she is there for other reasons, such as Washington’s push to reform the Fed, which she has criticized for years.
Still, investors get paid for understanding what is possible before the market prices it. So let’s look at the implications.
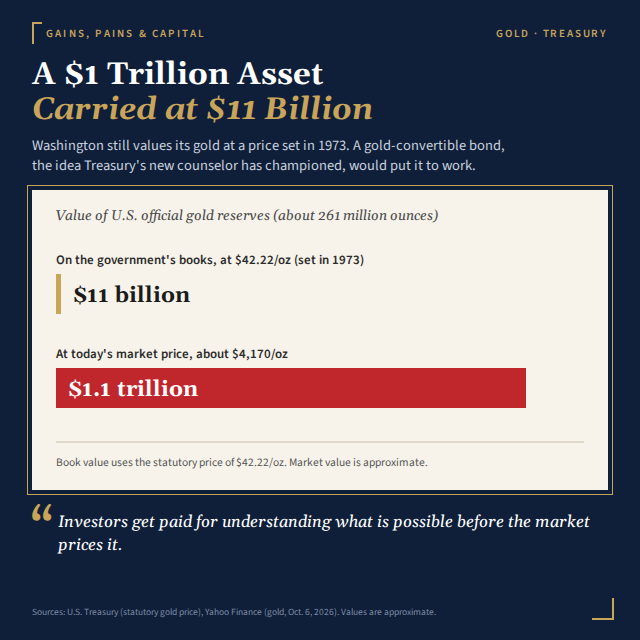
First, the balance sheet. The U.S. government still carries its gold at $42.22 an ounce, an official price set in 1973. At that price, America’s roughly 261 million ounces are worth about $11 billion on paper. At today’s price of around $4,170, they’re worth about $1.1 trillion. Any program that uses gold as backing for debt puts that gap to work without selling a single ounce.
Second, the incentive. A government that uses gold to support its borrowing has a reason to want a strong gold price, because the more gold is worth, the more it can support. That would be a meaningful shift from the past 50 years, when Washington treated gold as a relic.
Third, China. Beijing is already treating gold as strategic money. China’s central bank added 20.2 tonnes in August, its largest monthly purchase since October 2023. Its gold holdings have risen for 22 consecutive months, and gold is now 9% of China’s foreign exchange reserves. Shelton has written for years about rebuilding the international monetary system with gold playing a role. If Washington wants a response to China’s gold buildup, strengthening the dollar’s link to gold is one option.
And here’s what makes this interesting for investors: the market isn’t paying attention.
Gold is down nearly 8% from a month ago, and its gain over the past year is the smallest since Yahoo Finance began tracking it daily. Back in January, gold was up more than 95% year over year. Investors are treating gold as a trade that has run its course.
TO READ MORE: https://www.zerohedge.com/news/2026-10-06/why-did-treasury-just-hire-architect-gold-backed-bond
The Ultimate Anchor for the Financial System
The Ultimate Anchor for the Financial System
Gold Telegraph: 10-4-2026
For decades, U.S. Treasuries were treated like money.
Now they are starting to trade like debt.
Gold has always just been money.
The founding fathers understand that money is good as gold.
The Ultimate Anchor for the Financial System
Gold Telegraph: 10-4-2026
For decades, U.S. Treasuries were treated like money.
Now they are starting to trade like debt.
Gold has always just been money.
The founding fathers understand that money is good as gold.
Sound money…
Gold Telegraph: BREAKING NEWS: JUDY SHELTON HAS JOINED THE U.S. TREASURY DEPARTMENT AS COUNSELOR TO THE SECRETARY. Judy has spent decades thinking deeply about monetary policy, sound money, gold, and the architecture of the global financial system. To now see her bringing those ideas and that experience into discussions at the highest levels of the U.S. Treasury is incredibly exciting. My conversation with Judy on The Gold Telegraph will always be one of the highlights of my career. Beyond her extraordinary intellect, she is thoughtful, gracious, and deeply committed to the ideas she believes in. Full documentary: youtu.be/USGjSU5yXh8?si… Congratulations, my friend. Very well deserved. @judyshel
America has $40 trillion in national debt.
The President recently suggested that a certain level of inflation could reduce that burden faster.
Of course it can.
Inflation reduces the real value of debt.
But it also reduces the real value of your money.
This is exactly why gold remains the ultimate anchor of the financial system.
Source(s):
• https://x.com/GoldTelegraph/status/2106106115138478393
• https://x.com/GoldTelegraph/status/2106118311251767572
https://dinarchronicles.com/2026/10/03/gold-telegraph-the-ultimate-anchor-for-the-financial-system/
Gold and the Fed, Judy Shelton Appointment in Treasury, Six Banks
Gold and the Fed, Judy Shelton Appointment in Treasury, Six Banks
And We Know: 10-4-2026
The modern financial landscape is undergoing a massive transformation, driven by technological innovation and shifting economic philosophies. As traditional banking systems evolve, individuals and investors are being forced to reevaluate how money works, how transactions are processed, and what the future holds for personal financial autonomy.
Recent discussions from prominent financial commentators highlight a growing tension between centralized digital currency initiatives and timeless principles of sound money, offering a fascinating glimpse into the crossroads where technology meets liberty.
At the forefront of these technological changes is the emergence of programmable digital payments, particularly initiatives being explored by Canadian financial institutions. Proponents of these digital systems champion them for their incredible speed, efficiency, and the promise of cost-free transactions that could streamline commerce.
However, this technological leap forward is not without its critics. A closer look at programmable currency reveals significant concerns regarding individual privacy, personal freedom, and institutional control. Because programmable money can be coded with specific restrictions or conditions on how, when, and where it is spent, many analysts worry it paves the way for unprecedented oversight.
This apprehension has even led some commentators to draw symbolic comparisons to historical and biblical warnings regarding absolute control, underscoring the deep-seated mistrust many citizens hold toward top-down monetary policies.
Contrasting sharply with the trend toward centralized digital control are differing visions for broader economic recovery and monetary stabilization. On one side of the debate, figures like Judy Shelton have emerged as voices of hope for those advocating a return to stability.
Shelton has famously championed the idea of a gold-backed bond that could be convertible into either gold or traditional fiat currency, a move designed to instill confidence and anchor the currency in tangible value.
Supporters believe that reintroducing elements of a gold standard could curb reckless spending and protect the purchasing power of everyday citizens against the erosive effects of inflation.
This hopeful outlook on asset-backed currency stands in stark opposition to other economic proposals currently circulating among policymakers and influencers. For instance, strategies suggested by figures like Anthony Scaramucci—which often lean toward higher taxation and fiscal austerity—face heavy criticism from market traditionalists.
Opponents argue that increasing the tax burden and tightening austerity measures can severely stifle economic growth, hurt small businesses, and place an unfair weight on the middle class during already uncertain times. Instead of relying on government-mandated belt-tightening, many financial experts suggest that true economic health comes from fostering production, encouraging investment, and preserving the value of the currency.
As these debates unfold, a common theme continues to resonate among those seeking financial security: the enduring value of precious metals. Gold and silver are increasingly viewed not just as traditional investments, but as essential safeguards against persistent inflation and the potential loss of financial freedom.
In an era where digital currencies can be monitored, restricted, or altered by central authorities, holding physical assets provides a reliable fallback that remains entirely outside the banking system.
This renewed interest highlights a broader excitement within certain financial circles about the potential revival of sound money principles, reminding the market of the fundamental importance of intrinsic value.