Thank you to all the subscribers to our Early Access program…we thank you for your continued support.
We are excited to offer this new service to keep you informed and up-to-date on the latest Dinar and currency news.
Sat. Iraq News Posted by Tishwash at TNT 9-5-2026
TNT:
Tishwash: The Central Bank reassures depositors and confirms the protection of their funds.
The Central Bank of Iraq affirmed on Saturday that all depositors' funds in licensed banks are protected, while also stating that the Iraqi banking system possesses sufficient liquidity to efficiently manage its operations.
In a statement received by the Iraqi News Agency (INA), the bank clarified that "the Central Bank of Iraq's exercise of its powers to directly appoint supervisory or trusteeship committees to a licensed bank does not signify the bank's bankruptcy, as has been circulated on some social media platforms. Rather, these are precautionary and legal supervisory measures to ensure the bank's safety and the overall stability of its operations, and to protect depositors' rights in particular."
TNT:
Tishwash: The Central Bank reassures depositors and confirms the protection of their funds.
The Central Bank of Iraq affirmed on Saturday that all depositors' funds in licensed banks are protected, while also stating that the Iraqi banking system possesses sufficient liquidity to efficiently manage its operations.
In a statement received by the Iraqi News Agency (INA), the bank clarified that "the Central Bank of Iraq's exercise of its powers to directly appoint supervisory or trusteeship committees to a licensed bank does not signify the bank's bankruptcy, as has been circulated on some social media platforms. Rather, these are precautionary and legal supervisory measures to ensure the bank's safety and the overall stability of its operations, and to protect depositors' rights in particular."
The statement added that "the Central Bank of Iraq applies the best international banking standards to the banking sector to guarantee its safety, compliance, and the provision of optimal financial services without compromising the rights of its depositors."
It further explained that "all licensed banks participate in the Deposit Guarantee Corporation, which is a cornerstone of banking stability, through its role in compensating depositors should a bank fail to meet its obligations in accordance with applicable laws."
The bank noted that "depositors' funds are protected under applicable laws, regulations, and instructions, and the Central Bank of Iraq is closely monitoring banking procedures, particularly those related to ensuring depositors' access to their funds at any time without delay."
The bank also affirmed that "the Iraqi banking system possesses sufficient liquidity to manage its operations efficiently and under any potential pressures; the ratio of liquid assets to short-term liabilities exceeds 60%." link
************
Tishwash: The Central Bank reassures bank depositors
Affirming its pivotal role in protecting the financial system and ensuring a sound banking sector based on competitiveness and the provision of the best traditional and digital financial services, the Central Bank of Iraq wishes to inform and reassure the public of the following facts:
1. The Central Bank of Iraq's exercise of its powers to appoint supervisory or trusteeship committees to banks licensed directly by the Central Bank does not imply the bank's bankruptcy, as has been circulated in some media outlets. Rather, it is a legal and precautionary supervisory measure to ensure the bank's overall soundness and operational stability, and to protect depositors' rights in particular.
2. The Central Bank of Iraq applies the best international banking standards to the banking sector to ensure its safety, compliance, and the provision of optimal financial services without compromising the rights of its depositors.
3. All licensed banks participate in the Deposit Guarantee Corporation, which is a cornerstone of banking stability, through its function of compensating depositors in the event of a bank's inability to meet its obligations in accordance with applicable laws.
4. Depositors' funds are protected under applicable laws, regulations, and instructions. The Central Bank of Iraq pays close attention to monitoring banks' procedures, particularly those related to ensuring depositors' access to their funds at any time without delay.
5- The Iraqi banking system has sufficient liquidity to manage its operations efficiently and under any potential pressures; the ratio of liquid assets to short-term liabilities is more than (60%).
Baghdad - Media Office,
September 5, 2026 link
************
Tishwash: Removing zeros from the dinar: Parliamentary Finance Committee sets conditions for proceeding with this matter.
Member of the Parliamentary Finance Committee, Amer Rahim, confirmed on Saturday that voting on a bill to remove zeros from the local currency requires extensive discussions and the enactment of a package of laws within the Parliament. He indicated that raising this issue at the present time is premature.
Rahim told Al-Maalouma, "The step of removing zeros from the currency cannot be decided hastily; rather, it requires a series of lengthy and in-depth discussions within Parliament." He explained that "the process is closely linked to the economic reality and requires amending and enacting several supporting financial laws and regulations to ensure market stability."
He added, "Raising the discussion about this topic at this stage is premature, given the financial challenges that require first providing a comprehensive economic and banking environment before embarking on any structural change to the currency." He pointed out that "any measure of this kind without careful and prior study may negatively impact the purchasing power of citizens."
Rahim stressed "the need to focus currently on supporting the stability of the national currency and implementing banking reforms, while leaving the issue of removing zeros until economic conditions are more favorable and full legislative support is available within the House of Representatives." link
************
Tishwash: Washington's messages reach Baghdad... American reservations haunt the draft law on the Popular Mobilization Forces.
Revealed by the newspaper "An-Nahar" Lebanese The American side reported Baghdad Over the past few days, there have been clear reservations about re-tendering bill Popular Mobilization Forces In its previous form, while it requested Washington Explicit guarantees that all Popular Mobilization Forces formations will be subject to the authority of the Commander-in-Chief of the Armed Forces, and that no parallel structures or authorities will be allowed to exist alongside the security institutions.
And the law entered Popular Mobilization Forces A new political round in Iraq More than a year after its passage was thwarted in House of RepresentativesThis comes at a time when the attempt to regulate the situation of the Popular Mobilization Forces intersects with a broader governmental approach to restricting weapons to the state and readjusting the relationship between armed formations and official security institutions.
The House of Representatives had completed the first and second readings of the bill during 2025, before the process stalled at the voting stage due to political disagreements, American objections, and reservations from Sunni and Kurdish forces. The American objection at the time focused on articles that it considered...Washington This could grant armed factions greater space within the formal system, and affect the nature of the security partnership with Baghdad
The issue was revived in 2026 after the Speaker of Parliament addressed the government regarding the submission of the draft law, while confirming prime ministerAli Al-Zaidi His government is proceeding with submitting the Popular Mobilization Forces (PMF) law to parliament, based on the premise that the PMF is part of the armed forces.
This coincides with the drafting of a law restricting weapons to the state, placing the government in a complex dilemma. Legally reorganizing the PMF must proceed in parallel with reducing any space for weapons and security decisions outside the official command, especially since the PMF already enjoys legal cover since the enactment of the PMF Law.Popular Mobilization ForcesLaw No. 40 of 2016 links the Popular Mobilization Forces (PMF) to the Commander-in-Chief of the Armed Forces, according to the newspaper.
The newspaper adds that for this reason, the dispute is not so much about the legitimacy of the PMF's existence as it is about its internal structure, its chain of command, its funding and command mechanisms, and the boundaries of the relationship between the official institution and the factions that maintain their own political, ideological, and organizational identities.
Washington is setting its conditions.
In this context, an Iraqi government source revealed to the newspaper that the American side had informed Baghdad in recent days of clear reservations about reintroducing the draft law in its previous form, considering that any legislation granting the factions additional influence could directly conflict with the process of disarming the militias.
According to the source, Washington requested explicit guarantees that all PMF formations would be subject to the authority of the Commander-in-Chief of the Armed Forces and that no parallel structures or powers would be allowed to exist alongside the security institutions. American concerns also focus on the articles that might grant some leaders greater independence in decision-making, funding, or command structure, thus reinforcing the separation between the official form of the PMF and the actual reality of some factions within it.
Washington is also sensitive to the timing of the reintroduction of the law, given Baghdad's ongoing efforts to restrict weapons and end all armed activity outside official institutions. According to the same source, the American message warned that passing a version of the law that contradicts security sector reform could have repercussions on security, military, economic, and financial cooperation between the two countries.
Meanwhile, [the text abruptly ends here ].Iraqi governmentThe review of several articles of the draft law aims to preserve the legal framework of the Popular Mobilization Forces (PMF) and the rights of its members, without granting factions additional space outside the official command structure. The source believes that the coming days will determine whether Baghdad can reach a formula that combines establishing the PMF as an official institution with fulfilling its obligations regarding weapons.
The institution is one thing, and the factions are another.
The newspaper indicated that the main obstacle lies in the fact that legalizing the PMF has not practically led to the complete unification of its constituent formations. Since 2016, most factions have retained their names, structures, bases, and political and ideological affiliations, in addition to their presence in different areas of influence.
This reality, according to the newspaper, has left the transition from a multi-factional structure to a unified military institution incomplete, and has transformed issues of leadership, funding, and the chain of command into the core of the debate surrounding any new legislation.
The expert in strategic affairs, Major General Ahmed Al-Dulaimi The essence of the American observations lies precisely in this point: the necessity of subjecting all formations to the decision of the Commander-in-Chief of the Armed Forces and to a single military chain of command.
The problem, according to...Al-Dulaimi This becomes apparent when certain factions retain the ability to make unilateral decisions or exert their own influence, placing the state in confrontation with armed power centers that do not always operate within the same official framework.
Hence, the value of the law becomes tied to its ability to regulate powers, leadership, funding, and command mechanisms, and to prevent duplication of decision-making, while clearly distinguishing between the Popular Mobilization Forces (PMF) as an official institution and the factions that may adopt independent positions or decisions.
If legislation fails to address this gap, it may transform from a tool for regulating the institution into a legal cover that legitimizes the existing reality rather than changing it.
Weapons determine the fate of the law, and this equation becomes increasingly weighty as we approach 30 September The date related to the weapons inventory and the completion of the mission International coalition This makes the Popular Mobilization Forces (PMF) law part of a broader debate about the shape of Iraq's security state and the future of its relationship with Washington.
The newspaper explained that the law's success will depend not so much on its passage through parliament, but rather on its ability to effectively unify security decision-making within the institution and prevent the continued existence of independent power centers operating under an official umbrella.
Ultimately, the issue remains tied to the broader question facing Baghdad today: Will the new legislation lead to a more tightly integrated PMF into state institutions, or will it solidify the existing fragmentation within the organization under a more robust legal framework? link
MilitiaMan & Crew: Are You Ready for What's Next? | Sept 4th Update
MilitiaMan & Crew: Are You Ready for What's Next? | Sept 4th Update
9-5-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
MilitiaMan & Crew: Are You Ready for What's Next? | Sept 4th Update
9-5-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
Be sure to listen to full video for all the news……..
Iraq Economic News and Points To Ponder Saturday Morning 9-5-26
The Central Bank reassures depositors: No bank failures... and liquidity exceeds 60%
Baghdad Today - Baghdad The Central Bank of Iraq reassured depositors on Saturday (September 5, 2026) about the safety of the banking sector, stressing that “imposing supervisory or guardianship committees on a licensed bank does not mean its bankruptcy, but rather comes within the framework of precautionary and legal supervisory measures aimed at protecting the rights of depositors and ensuring the stability of banking operations.”
The Central Bank reassures depositors: No bank failures... and liquidity exceeds 60%
Baghdad Today - Baghdad The Central Bank of Iraq reassured depositors on Saturday (September 5, 2026) about the safety of the banking sector, stressing that “imposing supervisory or guardianship committees on a licensed bank does not mean its bankruptcy, but rather comes within the framework of precautionary and legal supervisory measures aimed at protecting the rights of depositors and ensuring the stability of banking operations.”
The bank stated in a statement received by "Baghdad Today" that "all licensed banks participate in the Deposit Guarantee Company, which is responsible for compensating depositors in the event that the bank fails to meet its obligations, in accordance with applicable laws."
He added that "depositors' funds are protected under laws, regulations and instructions," stressing the need to follow up on bank procedures, particularly those related to ensuring depositors' access to their funds without delay.
He pointed out that "the Iraqi banking system has sufficient liquidity to enable it to manage its operations efficiently in the face of potential pressures," indicating that "the ratio of liquid assets to short-term liabilities exceeds 60%."
It also emphasized the application of the best international banking standards to the banking sector, ensuring its safety and compliance and providing competitive traditional and digital financial services, without compromising the rights of depositors.
https://baghdadtoday.news/305588-60.html
The Government Faces Two Tests: Autonomy And The Economy. Will It Succeed In Overcoming The Political And Administrative Turmoil?
Today 15:34 Information / Special.. Political analyst Majashaa Al-Tamimi confirmed on Saturday that the ambiguous scene in Iraq reflects a structural and chronic governance crisis, which is mainly due to the sectarian and partisan quota system that prioritizes narrow interests over the national interest.
Al-Tamimi told Al-Maalouma that "the absence of sovereign decision-making in Iraq has led to weak administrations that lack strategic vision and rely heavily on a rentier economy based on oil."
Al-Tamimi added that “talking about restricting weapons cannot take place in light of Iraq’s lack of full autonomy and the absence of a serious political will capable of putting an end to foreign interference in all its forms,” stressing that “establishing the authority of the state requires first and foremost an independent sovereign decision and a clear political will.”
He pointed out that "combating corruption and economic reform require moving from patchwork solutions to comprehensive institutional reforms, through automating administration, diversifying sources of income, and strengthening the independence of the judiciary and activating its role in combating corruption."
He continued, "Iraq's future remains suspended between the continuation of the political and administrative chaos and the emergence of a genuine reformist will be capable of transcending the conflicts of power-sharing and spoils and placing the national interest at the forefront of priorities." (End of page 25)
Employee Salaries: Between The Embers Of Economic Skepticism And The Cool Reassurances
Today 13:42 Information/Report... The issue of employee and retiree salaries has returned to the forefront of the Iraqi economic scene, amidst a clear discrepancy between official and parliamentary assurances regarding the availability of the necessary liquidity to secure monthly payments, and warnings against the state's continued reliance on short-term solutions without a comprehensive economic vision to address chronic financial imbalances.
The salary issue holds exceptional importance in Iraq, given its direct impact on millions of employees, retirees, and their families, as well as its repercussions on market activity, consumption, and economic activity in general. This makes any discussion of potential difficulties in funding salaries a matter of widespread concern among the Iraqi public.
Despite the recurring concerns about the state's ability to continue paying salaries, the Parliamentary Finance Committee asserts that the current financial situation does not warrant alarm, and that the relevant government agencies are committed to providing the necessary funds for timely disbursement.
In this context, Jamal Kojar, a member of the Parliamentary Finance Committee, emphasized that the Prime Minister's office and the Ministry of Finance bear direct responsibility for managing the salary file, indicating that official bodies have confirmed their commitment to securing the necessary funds and that there are no obstacles preventing their disbursement.
Kujer told Al-Maalomah News Agency that "the relevant official bodies, foremost among them the Prime Minister's office and the Ministry of Finance, have affirmed their commitment to securing the funds for salaries without any obstacles."
He added that "the country's financial resources have begun to recover significantly, particularly oil revenues, which have recorded better levels compared to previous months," indicating, according to the available data, the government's financial capacity to continue meeting its monthly obligations.
Despite these assurances, concerns about the future of financial stability persist, especially given the Iraqi economy's continued heavy reliance on oil revenues, making it more vulnerable to fluctuations in crude oil prices and global market movements.
Critics of economic policies argue that the continued focus on securing salaries and operational spending does not constitute a genuine solution to the financial problem, but rather postpones crises to later stages, unless this is accompanied by reforms capable of diversifying income sources and increasing the contribution of productive sectors to the national economy.
In this context, MP Abdul Hamza al-Khafaji asserted that the government lacks clear economic solutions to address the financial crises, indicating that its primary focus is on securing employee salaries.
Al-Khafaji told the Al-Maalomah news agency, “The government has no economic solutions beyond securing employee salaries,” explaining that “the Iraqi economy needs a comprehensive vision that goes beyond addressing monthly obligations.”
He pointed out that "relying on oil as the main source of revenue makes the economy vulnerable to fluctuations and crises," calling for the development of concrete plans to diversify income sources and strengthen productive sectors.
Salaries: Between Social Entitlement and Financial Management
Ensuring salaries is a fundamental obligation for the state, but its continued prominence on the list of financial priorities raises questions about the economy's ability to transition from managing monthly obligations to building a more sustainable financial base.
An economy dependent on a single primary resource remains vulnerable to external influences not entirely under government control, most notably fluctuations in oil prices, export volumes, and revenues. This makes financial stability highly dependent on the performance of the oil sector.
Therefore, ensuring regular salary payments does not necessarily guarantee overcoming the economic crisis, but rather reflects the state's ability to meet its basic obligations in the short term. A genuine solution lies in broader reforms encompassing revenues, expenditures, public administration, and productive sectors.
Given these circumstances, calls are growing from both parliamentary and economic circles to reduce dependence on oil by revitalizing the industrial, agricultural, and investment sectors, supporting the private sector, and increasing non-oil revenues.
Al-Khafaji emphasized that addressing the financial crisis requires “economic and administrative reforms, reducing waste and corruption, and improving the management of public resources.” He stressed that "securing salaries should be part of a comprehensive economic plan, not the sole solution to the financial problems."
He also emphasized the need to adopt economic policies capable of creating job opportunities, stimulating the private sector, and increasing non-oil revenues, calling on the government to provide sustainable solutions that guarantee the country's financial and economic stability.
Immediate stability or a sustainable solution?
While assurances regarding the availability of liquidity seem capable of calming concerns about salaries in the short term, the broader debate extends beyond the issue of disbursing monthly payments to the future of public finances and their ability to withstand any potential revenue shocks.
This debate presents the government with a dual dilemma: maintaining the regularity of salaries as a social and economic priority, while simultaneously transitioning to long-term policies that reduce the fragility of public finances and provide the Iraqi economy with more diversified and stable sources of income.
Thus, the salary file remains secure according to current parliamentary and official assurances. However, ensuring its long-term sustainability depends on the state's ability to address the root causes of economic imbalances and transition from managing the financial crisis month by month to building an economy capable of with outstanding oil price fluctuations and achieving sustainable financial stability. End/25
Seeds of Wisdom RV and Economics Updates Saturday Morning 9-5-26
Good Morning Dinar Recaps,
KHARG ISLAND ATTACK RAISES NEW OIL-SHOCK RISK: MIDDLE EAST ENERGY DISRUPTION COULD REPRICE GLOBAL DEBT AND CURRENCIES
An oil tanker was reportedly struck near Iran’s critical Kharg Island export hub, adding a new layer of energy-supply risk to a global economy already dealing with elevated oil prices, inflation pressure and higher borrowing costs.
Good Morning Dinar Recaps,
KHARG ISLAND ATTACK RAISES NEW OIL-SHOCK RISK: MIDDLE EAST ENERGY DISRUPTION COULD REPRICE GLOBAL DEBT AND CURRENCIES
An oil tanker was reportedly struck near Iran’s critical Kharg Island export hub, adding a new layer of energy-supply risk to a global economy already dealing with elevated oil prices, inflation pressure and higher borrowing costs.
OVERVIEW
Energy Risk: An Iranian oil tanker was reportedly hit by four U.S. missiles near Kharg Island, according to Iranian media, with the crew evacuated and no casualties reported. The incident had not been officially confirmed by Iranian authorities or U.S. Central Command when Reuters reported it.
Critical Export Hub: Kharg Island has historically handled about 90% of Iran’s crude exports, making any disruption there potentially significant for an already-constrained regional oil market.
Financial Transmission: A prolonged energy disruption can move beyond oil markets into inflation, interest rates, bond yields, currencies and global borrowing costs.
KEY DEVELOPMENTS
1. A New Threat Emerges Near Iran’s Main Oil Export Hub
An Iranian tanker near Kharg Island was reportedly struck by four U.S. missiles on September 5, according to Iran’s semi-official Tasnim news agency and reporting cited by Reuters.
The tanker reportedly suffered no casualties, while its crew was evacuated. The reported strike had not received immediate official confirmation from either Tehran or U.S. Central Command, making verification important as the situation develops.
The significance lies not only in the vessel itself, but in where the incident occurred.
2. Kharg Island Is a Critical Point in Iran’s Oil System
Kharg Island is Iran’s principal crude-oil export terminal and has historically handled approximately 90% of the country's crude exports.
Operations have already been severely disrupted by the U.S. oil-export blockade and the continuing conflict surrounding the Strait of Hormuz.
That means another disruption could further restrict Iran's ability to move crude into international markets.
For global markets, the question is therefore not simply how much Iranian oil is lost—but how much additional uncertainty is introduced into an already disrupted regional supply chain.
3. Oil Is Already Creating an Inflation Problem
The latest Kharg Island development comes as Middle East tensions have already pushed crude prices above $90 a barrel.
Reuters reported that the ongoing conflict has also driven U.S. gasoline prices to a record-high Labor Day weekend average of approximately $4.03 per gallon. Higher crude prices, limited refinery capacity and reduced inventories are contributing to the pressure on consumers.
That creates a difficult policy environment.
Higher energy prices can push inflation higher just as central banks are trying to determine whether economic conditions justify lower interest rates.
4. The Energy Shock Can Become a Bond-Market Shock
Oil does not operate independently from the financial system.
A sustained increase in energy prices can raise inflation expectations. Higher inflation expectations can make central banks more cautious about cutting rates and can encourage bond investors to demand greater yields.
That creates a potential chain reaction:
Energy disruption → higher oil prices → inflation pressure → higher-for-longer rates → higher bond yields → higher government borrowing costs.
That transmission mechanism is particularly important now because global debt levels are already elevated and long-term Treasury yields have been under pressure.
5. Currency Markets Could Feel the Next Wave
Energy shocks can also produce major changes in international capital flows.
Oil-importing countries may face larger trade deficits and increased demand for dollars to purchase energy. Countries with weaker currencies can experience additional pressure if energy imports become substantially more expensive.
At the same time, investors may move toward currencies and assets perceived as safer during periods of geopolitical stress.
For foreign currency holders, this means the consequences of the Kharg Island development could eventually appear far beyond the Middle East.
WHY IT MATTERS
Economy
Higher energy costs act like a tax on households and businesses.
Consumers have less money available for discretionary spending, while transportation, manufacturing and other energy-intensive industries face higher costs.
Markets
Oil, bonds, equities and currencies can become increasingly interconnected when geopolitical risk threatens energy supplies.
The longer the disruption persists, the greater the possibility that markets begin pricing persistent inflation rather than a temporary oil spike.
Policy
Central banks face a difficult tradeoff.
If energy prices push inflation higher, policymakers may have less room to cut interest rates—even if higher borrowing costs are already weighing on economic activity.
Global System
The Strait of Hormuz and Kharg Island demonstrate how a relatively concentrated energy infrastructure can have consequences across the global financial system.
The issue is no longer simply how much oil is available.
It is increasingly about whether that oil can move reliably through the global trading system.
WHY IT MATTERS TO FOREIGN CURRENCY HOLDERS
Oil-importing currencies: Countries dependent on imported energy can face additional pressure on their trade balances and currencies.
Dollar demand: Energy-market disruptions can increase demand for dollars because much international oil trade is dollar-denominated.
Purchasing power: Higher fuel and transportation costs can reduce the purchasing power of currencies when inflation rises.
Capital flows: Geopolitical uncertainty can redirect international capital toward perceived safe-haven assets and away from vulnerable emerging markets.
Currency volatility: If oil remains elevated, differences between energy exporters and importers could become increasingly important to exchange-rate performance.
IMPLICATIONS FOR THE GLOBAL RESET
Pillar 1: Energy
The Kharg Island development reinforces how energy infrastructure has become a strategic financial asset.
Control over oil exports, shipping routes and energy supply chains can influence inflation, trade balances, currencies and national fiscal conditions.
The global financial system cannot be separated from the physical energy system that supports it.
Pillar 2: Debt
An energy shock becomes a debt problem when higher inflation prevents interest rates from falling as quickly as markets expect.
If governments must refinance large debt loads at higher yields, energy-driven inflation can increase the cost of maintaining already elevated debt burdens.
That creates another pressure point in the global financial system.
CONCLUSION
The reported strike near Kharg Island is significant because it places one of Iran’s most important oil-export locations back at the center of the global energy-risk equation.
The immediate question is whether the incident remains isolated or becomes part of a broader escalation affecting Iran's ability to export crude and the region's ability to move energy safely.
The larger financial question is what happens if elevated oil prices persist while governments are already carrying historically large debt loads.
Energy disruption can become inflation. Inflation can become higher interest rates. Higher rates can become higher debt costs. And higher debt costs can ultimately reshape global capital and currency flows.
This is why the Kharg Island development matters beyond the battlefield: the next financial repricing may come not from a central-bank announcement, but from the interaction between energy supply, inflation, debt and global capital.
Seeds of Wisdom Team
Newshounds News™ Exclusive
SOURCES
Reuters — “Iranian tanker hit by US attack near Iran's Kharg Island, Tasnim says”
Reuters — “Americans hit with record-high Labor Day Weekend gasoline prices”
~~~~~~~~~~
🌱 A Message to Our Currency Holders🌱
If you’ve been holding foreign currency for many years, you were not foolish.
You were not wrong to believe the global financial system would change.
What failed was not your patience — it was the information you were given.
For years, dates, rumors, and personalities replaced facts, structure, and proof. “This week” predictions created cycles of hope and disappointment that were never based on how currencies actually change.
That is not your failure.
Our mission here is different: • No dates • No rates • No hype • No gurus
Instead, we focus on:
• Verifiable developments • Institutional evidence
• Global financial structure • Where countries actually sit in the process
Currency value changes only come after sovereignty, trade, banking, settlement systems, and fiscal coordination are in place. History and institutions confirm this sequence.
You will see silence. You will see denials. That is not delay — that is discipline.
Protect your identity. Organize your documents. Verify everything.
Never hand your discernment to anyone who cannot show proof.
You deserve truth — not timelines.
Seeds of Wisdom Team
Newshounds News
~~~~~~~~~~
Seeds of Wisdom Team RV Currency Facts Youtube and Rumble
Newshound's News Telegram Room Link
RV Facts with Proof Links Link
RV Updates Proof links - Facts Link
Start Here room with Most Asked Questions Link
Follow the Gold/Silver Rate COMEX
Follow Fast Facts
Seeds of Wisdom Team™ Website
Thank you Dinar Recaps
Rob Cunningham: A New Monetary Era is here
Rob Cunningham: A New Monetary Era is here
9-4-2026
RIPPLE: THE CONNECTIVE INFRASTRUCTURE OF PROGRAMMABLE GLOBAL FINANCE
A new monetary era has taken form.
The G20 is advancing financial modernization, digital assets, ISO 20022 harmonization, longer payment-system operating hours and better cross-border payments.
Rob Cunningham: A New Monetary Era is here
9-4-2026
RIPPLE: THE CONNECTIVE INFRASTRUCTURE OF PROGRAMMABLE GLOBAL FINANCE
A new monetary era has taken form.
The G20 is advancing financial modernization, digital assets, ISO 20022 harmonization, longer payment-system operating hours and better cross-border payments.
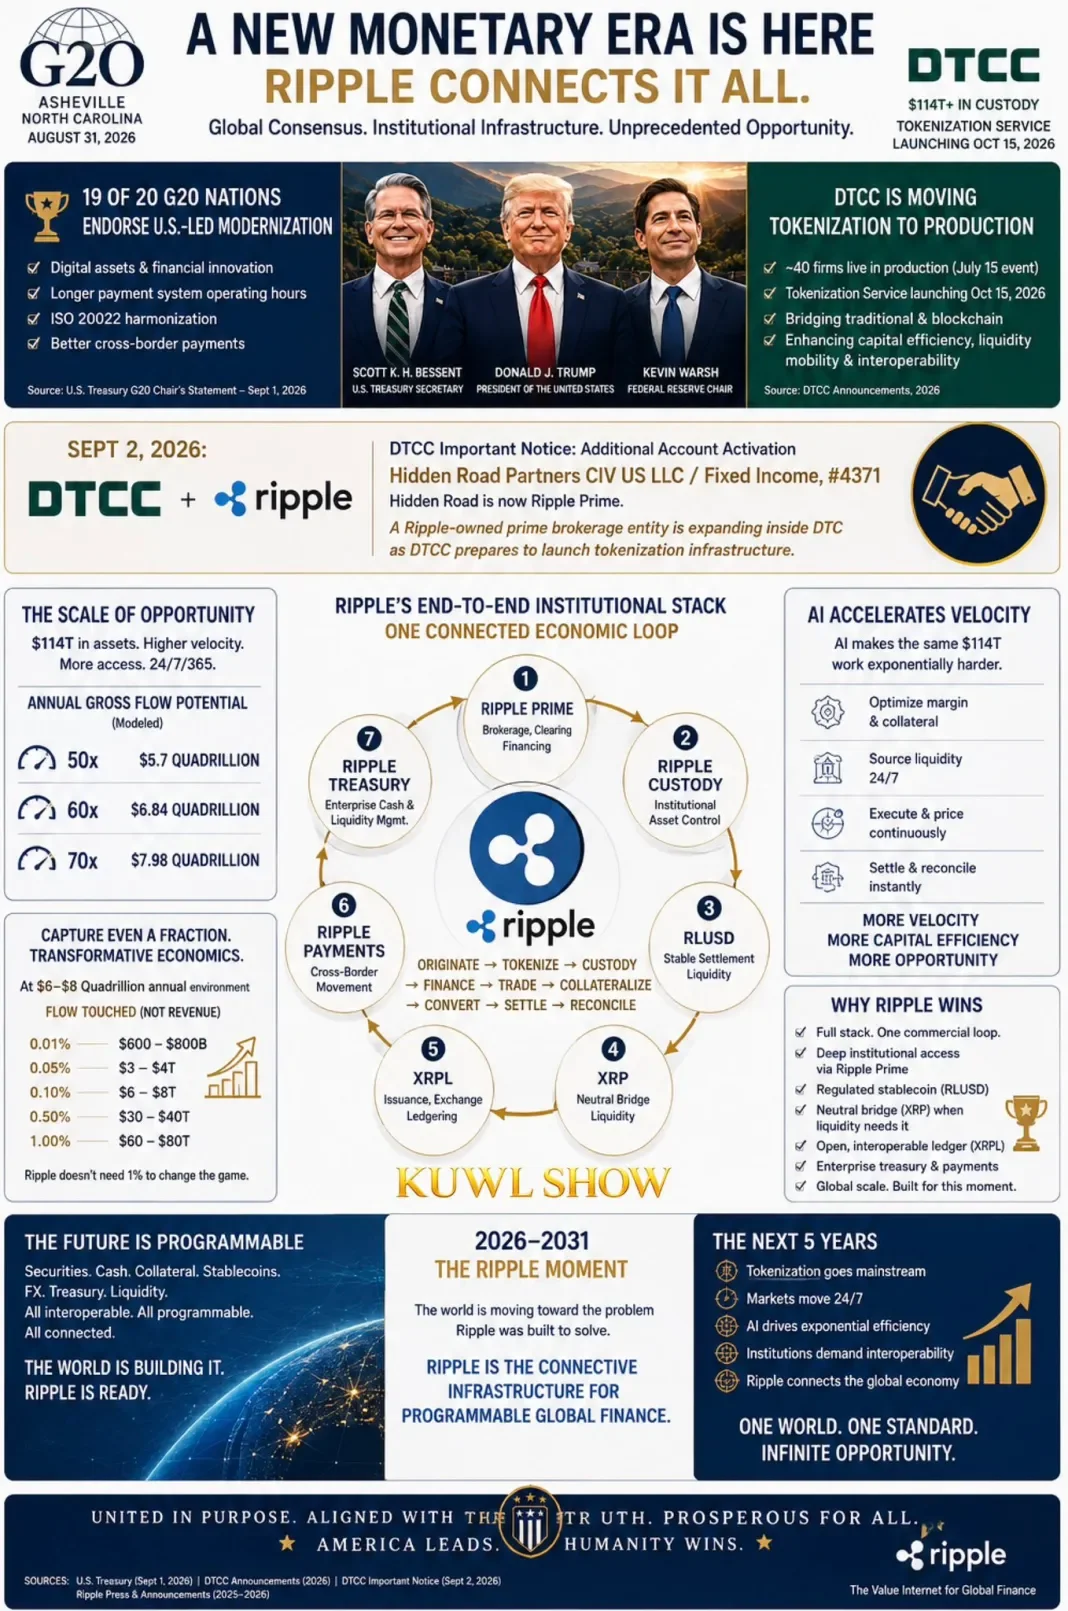
DTCC is bringing tokenization into production across an infrastructure responsible for more than $114 trillion in assets.
Ripple Prime now extends Ripple directly into institutional brokerage, clearing, financing and fixed-income markets.
These forces converge around one requirement:
Capital must become programmable, interoperable, liquid and globally mobile.
Ripple built for this moment.
ONE COMPANY. SEVEN INSTITUTIONAL CAPABILITIES.
1 Ripple Prime — Brokerage • Clearing • Financing
2 Ripple Custody — Institutional Asset Control
3 RLUSD — Stable Settlement Liquidity
4 XRP — Neutral Bridge Liquidity
5 XRPL — Issuance • Exchange • Ledgering
6 Ripple Payments — Global Value Movement
7 Ripple Treasury — Enterprise Cash & Liquidity Management
Together they create one connected economic loop:
ORIGINATE → TOKENIZE → CUSTODY → FINANCE → TRADE → COLLATERALIZE → CONVERT → SETTLE → RECONCILE
That integration is Ripple’s competitive advantage.
Ripple does not merely provide another payment rail, stablecoin, blockchain, custody platform or prime broker.
Ripple connects the entire institutional value chain.
$114 TRILLION BECOMES MORE PRODUCTIVE
Tokenization changes what assets can do.
AI changes how frequently they can do it.
As markets move toward continuous trading, collateral optimization, liquidity sourcing and settlement, the same capital can work harder:
50× turnover → $5.7 quadrillion annually
60× turnover → $6.84 quadrillion annually
70× turnover → $7.98 quadrillion annually
The transformation is not simply more money.
It is more utility from every dollar of existing value.
More velocity.
More liquidity.
More collateral mobility.
More transactions.
More settlement.
More interoperability.
RIPPLE NEEDS A FRACTION TO BUILD AN EMPIRE
At $6–$8 quadrillion of modeled annual institutional flow:
0.01% connected → $600–$800 billion
0.10% → $6–$8 trillion
0.50% → $30–$40 trillion
1.00% → $60–$80 trillion
Every additional institutional connection can strengthen the utility of Ripple Prime, Custody, RLUSD, XRP, XRPL, Payments and Treasury.
Each product strengthens the others.
Each new customer expands the network.
Each new asset creates another potential liquidity relationship.
Each new market creates another pathway through the stack.
2026–2031: THE RIPPLE MOMENT
The financial system is becoming programmable.
• Securities become programmable.
• Cash becomes programmable.
• Collateral becomes programmable.
• Treasury becomes programmable.
• Liquidity becomes programmable.
• Markets become continuous.
Ripple sits at their intersection.
The opportunity is no longer simply moving money across borders.
It is connecting assets, institutions, currencies, liquidity and ledgers across borders and markets.
That is the 5-year Ripple future:
ONE CONNECTED STACK.
ONE GLOBAL VALUE NETWORK.
INSTITUTIONAL FINANCE, MADE PROGRAMMABLE.
The world is building the new financial system.
@Ripple is built to connect it all.
Source(s):
• https://x.com/KuwlShow/status/2095579424884400399
https://dinarchronicles.com/2026/09/03/rob-cunningham-a-new-monetary-era-is-here/
History Makes a STRONG Case For A Dinar Revaluation
History Makes a STRONG Case For A Dinar Revaluation
The Dinar Den: 9-3-2026
Global monetary systems are rarely static, continuously evolving through cycles of restructuring, technological innovation, and geopolitical readjustments.
Among the most discussed topics in modern currency analysis is the long-term trajectory of the Iraqi dinar and the broader economic framework supporting its potential revaluation. Rather than viewing currency shifts as isolated financial events, expert analyses suggest that significant monetary adjustments are part of a larger historical continuum.
History Makes a STRONG Case For A Dinar Revaluation
The Dinar Den: 9-3-2026
Global monetary systems are rarely static, continuously evolving through cycles of restructuring, technological innovation, and geopolitical readjustments.
Among the most discussed topics in modern currency analysis is the long-term trajectory of the Iraqi dinar and the broader economic framework supporting its potential revaluation. Rather than viewing currency shifts as isolated financial events, expert analyses suggest that significant monetary adjustments are part of a larger historical continuum.
By examining historical precedents, modern banking standards, and digital infrastructure rollouts, macroeconomists and currency observers gain a clearer perspective on how post-conflict nations rebuild their fiscal sovereignty and integrate into the international financial ecosystem.
Looking back at twentieth-century economic history provides essential context for understanding modern monetary resets. Countries like post-war Germany, Japan, and South Korea underwent extensive financial and structural overhauls following severe geopolitical disruptions.
In each instance, international stabilization programs, backed by major economic powers and multilateral institutions, helped transition shattered local currencies into stable mediums of exchange. These historical precedents demonstrate that rebuilding national balance sheets often involves severe currency devaluations followed by multi-phase stabilization strategies, institutional reforms, reserve accumulation, and eventual revaluation to reflect real economic value.
In the case of Iraq, the post-2003 financial architecture was heavily shaped by direct international and United States institutional involvement. The initial focus centered on stabilizing the domestic market, establishing a new sovereign currency framework, and controlling hyperinflation through regular currency auctions. Over the past two decades, this relationship has evolved from immediate post-conflict stabilization toward long-term modernization.
Integrating Iraq’s banking system into the global swift network and standardizing international correspondent banking relations have established a foundation where the foreign exchange environment can gradually shift away from strict capital controls toward broader market-oriented flexibility.
A notable aspect of Iraq’s contemporary economic strategy is its aggressive push toward monetary digitization and electronic banking solutions. While many developed nations are still deliberating the domestic deployment of Central Bank Digital Currencies, developing markets often serve as efficient testing environments for rapid digital transformation.
Iraq’s central bank has prioritized financial inclusion, point-of-sale terminal adoption, and core banking technology modernization. This accelerated push toward a cashless framework reduces the reliance on paper physical currency, minimizes informal market leakages, and establishes the precise tracking mechanisms necessary for a controlled currency adjustment.
Behind these domestic reforms lies a strict adherence to global regulatory standards, specifically those governed by the International Monetary Fund and international banking guidelines like Basel III.
Under the Basel III capital adequacy framework, sovereign central banks have renewed their focus on physical gold reserves, reclassifying unencumbered gold as a primary reserve asset.
Iraq’s deliberate accumulation of sovereign gold reserves serves a dual purpose: it fortifies the nation’s balance sheet against inflationary pressures and aligns its banking sector with top-tier international settlement standards, signaling to global markets that its currency is increasingly backed by verifiable wealth.
Despite optimistic analyses regarding monetary adjustments, economic restructurings of this scale are inherently gradual processes. Complex monetary coordination involves balancing exchange rate mechanisms, managed floats, cash turn-in periods, and regional political dynamics, meaning timeline estimates must be met with analytical patience. Sovereign nations prioritize systemic stability over rapid market shifts, ensuring that domestic industries and fiscal policy can sustain new currency values.
Seeds of Wisdom RV and Economics Updates Friday Afternoon 9-4-26
Good Afternoon Dinar Recaps,
GLOBAL INVESTORS MOVE $46 BILLION INTO CASH: JOBS SHOCK REIGNITES RATE RISKS AND REPRICES GLOBAL CAPITAL
Global investors are moving billions toward money-market funds and shorter-duration assets as a stronger-than-expected U.S. jobs report, elevated oil prices and bond-market stress increase the risk that interest rates will remain higher for longer.
Good Afternoon Dinar Recaps,
GLOBAL INVESTORS MOVE $46 BILLION INTO CASH: JOBS SHOCK REIGNITES RATE RISKS AND REPRICES GLOBAL CAPITAL
Global investors are moving billions toward money-market funds and shorter-duration assets as a stronger-than-expected U.S. jobs report, elevated oil prices and bond-market stress increase the risk that interest rates will remain higher for longer.
OVERVIEW
$46.1 Billion Into Money Funds: Global money-market funds attracted $46.1 billion in net inflows through September 2, the largest weekly inflow since early August, as investors became more cautious amid bond-market and geopolitical stress.
Jobs Shock Changes the Fed Equation: U.S. employers added 162,000 jobs in August, nearly three times the expected gain, while unemployment remained at 4.1%, putting a September Fed rate hike firmly back on the table.
Capital Is Being Repositioned: Higher Treasury yields and uncertainty over inflation and interest rates are encouraging investors to favor liquidity and shorter-term assets, creating another measurable shift in global capital allocation.
KEY DEVELOPMENTS
1. $46.1 Billion Moves Toward Cash
Global money-market funds recorded $46.1 billion in net inflows during the week ending September 2.
Reuters reported that this was the largest weekly inflow since August 5, reflecting investor caution as global bonds sold off and U.S.-Iran tensions increased.
Money-market funds provide investors with liquidity and relatively short-duration exposure. The movement therefore offers a measurable indication that investors were becoming more defensive.
The significance is not simply the amount of money involved.
It is where investors chose to put it.
2. Investors Are Reducing Long-Duration Exposure
Bond-fund inflows slowed to approximately $10 billion, their lowest level in five weeks, while short-term bond funds experienced their strongest inflows since July.
At the same time, government and corporate bond funds experienced outflows.
This suggests that investors are not necessarily abandoning fixed income altogether.
Instead, they are becoming more cautious about locking money into longer-term securities while the direction of inflation and interest rates remains uncertain.
That distinction is important.
3. The U.S. Jobs Report Delivered a Major Surprise
Today's employment report changed the financial picture again.
The U.S. economy added 162,000 jobs in August, far above the approximately 56,000 jobs economists had expected.
The unemployment rate remained at 4.1%, while labor-force participation increased to 61.6% from 61.4% in July.
The report indicates that the U.S. labor market was considerably stronger than investors had anticipated.
That matters because a resilient labor market gives the Federal Reserve less reason to quickly ease monetary policy if inflation remains elevated.
4. Rate-Hike Expectations Returned
The stronger jobs data immediately changed expectations for the Federal Reserve's September meeting.
Reuters reported that markets increased the probability of a September rate hike to approximately 61%, reversing some of the easing in expectations that followed Fed Governor Christopher Waller's comments on Thursday.
That creates a significant shift from just one day earlier.
Yesterday: markets were becoming more confident that the Fed could hold rates.
Today: stronger employment data have put another rate increase firmly back into consideration.
The next major test will be the upcoming inflation data, which will help determine whether the Fed can justify another increase.
5. Treasury Yields Rose as the Cost of Money Was Repriced
The jobs report immediately pushed Treasury yields higher.
Reuters reported that the 10-year Treasury yield moved toward 4.80%, while the stronger employment data reinforced expectations for potentially tighter monetary policy.
This is significant because the Treasury market is already dealing with several pressures:
Large U.S. deficits + heavy Treasury issuance + elevated inflation risks + higher oil prices + changing Fed expectations.
Today's jobs report adds another factor:
A stronger economy may allow interest rates to remain higher for longer.
6. Oil Adds Another Inflationary Pressure
The employment shock is occurring against a backdrop of elevated energy prices.
Renewed U.S.-Iran tensions have pushed Brent crude toward $100 per barrel, increasing the possibility that higher energy costs could slow the progress of disinflation.
This creates a difficult environment for the Federal Reserve.
A strong labor market argues against rapid monetary easing, while higher energy prices create another potential source of inflation.
For investors, that combination makes liquidity and shorter-duration investments more attractive.
WHY IT MATTERS
Economy
Higher interest rates increase financing costs for households, businesses and governments.
A stronger labor market could support economic activity, but sustained high borrowing costs can eventually weigh on investment and consumption.
Markets
The movement of $46.1 billion into money-market funds shows that investors are actively repositioning capital.
Today's jobs report adds another reason for that caution by increasing uncertainty about the future path of interest rates.
Policy
The Federal Reserve now faces a difficult combination of stronger employment, elevated oil prices and persistent inflation risk.
The September policy decision will depend heavily on whether upcoming inflation data confirm or contradict today's employment signal.
Global System
U.S. interest rates influence borrowing costs and capital flows around the world.
When investors can earn attractive returns from relatively liquid dollar assets, capital can move toward the United States and away from riskier or lower-yielding markets.
That can place additional pressure on emerging-market currencies, sovereign debt and global liquidity.
WHY IT MATTERS TO FOREIGN CURRENCY HOLDERS
Dollar strength: Higher U.S. rates can increase demand for dollar-denominated assets and support the dollar relative to some other currencies.
Exchange rates: A change in Fed expectations can produce rapid currency movements.
Capital flows: The $46.1 billion money-market inflow demonstrates that global investors are actively changing their allocation toward liquidity.
Emerging-market currencies: Higher U.S. yields can make it more expensive for emerging economies to attract and retain foreign capital.
Purchasing power: Higher oil prices combined with currency movements can increase the cost of imported energy and other internationally traded goods.
For foreign-currency holders, the important signal is not one day's dollar movement.
It is whether higher U.S. yields begin creating a sustained change in global capital allocation.
IMPLICATIONS FOR THE GLOBAL RESET
Pillar 1: Assets
The movement of $46.1 billion into money-market funds is evidence that investors are reassessing duration and liquidity.
If the market increasingly expects higher rates to persist, capital may continue moving away from long-duration assets and toward cash, short-term securities and other liquid instruments.
That represents a change in how global capital is being positioned.
Pillar 2: Debt
Higher interest rates create greater pressure on highly indebted governments, companies and households.
The issue is particularly important for governments because every refinancing cycle can occur at a different—and potentially higher—cost.
Today's jobs report therefore matters beyond employment.
A stronger economy can give the Fed more room to keep rates elevated, while higher rates increase the cost of financing an already heavily indebted global system.
CONCLUSION
The $46.1 billion flow into global money-market funds was already an important signal that investors were becoming more cautious.
Today's employment report gives that capital movement a new context.
The U.S. economy added 162,000 jobs—nearly three times expectations—while unemployment remained at 4.1%, forcing markets to reconsider the possibility of another Federal Reserve rate increase.
At the same time, Treasury yields moved higher and oil remained elevated because of the continuing conflict surrounding Iran and the Strait of Hormuz.
The result is a financial system facing stronger-than-expected U.S. employment, elevated energy prices, higher Treasury yields and investors actively shifting toward liquidity.
That combination matters because the global financial system is highly sensitive to the price of money.
For foreign currency holders, the next phase may be determined less by whether the Fed cuts or raises rates at one particular meeting and more by whether higher U.S. yields begin producing a sustained redistribution of global capital.
When investors move billions toward liquidity while the cost of money rises, the movement of capital itself becomes a signal that the global financial system is repricing risk, return and duration.
Seeds of Wisdom Team
Newshounds News™ Exclusive
SOURCES
Reuters — “Global money funds draw biggest inflow in nearly a month as investors turn cautious”
Reuters — “US nonfarm payrolls surge in August; unemployment rate steady at 4.1%”
~~~~~~~~~~
Seeds of Wisdom Team RV Currency Facts Youtube and Rumble
Newshound's News Telegram Room Link
RV Facts with Proof Links Link
RV Updates Proof links - Facts Link
Start Here room with Most Asked Questions Link
Follow the Gold/Silver Rate COMEX
Follow Fast Facts
Seeds of Wisdom Team™Website
Thank you Dinar Recaps
MilitiaMan & Crew: Iraq's Quiet Build: Why everyone is watching the new cabinet
MilitiaMan & Crew: Iraq's Quiet Build: Why everyone is watching the new cabinet
9-4-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
MilitiaMan & Crew: Iraq's Quiet Build: Why everyone is watching the new cabinet
9-4-2026
The Crew: Samson, PompeyPeter, Petra, Daytrader, Sunkissed, GIGI and Militia Man
No drama. No intrigue. No songs and dances. Just straight, factual news that I read and interpret to the best of my ability after being an avid Dinar investor and insanely obsessed Dinarian for over 15 years.
Follow MM on X == https://x.com/Slashn
Be sure to listen to full video for all the news……..
Iraq Economic News and Points To Ponder Friday Morning 9-4-26
The Budget Comes First... Parliament Pledges To Cooperate With The Government To Approve It Quickly, And The Parliamentary Finance Committee Reveals To NINA The Size Of Iraq's Debt
Baghdad / NINA / The Parliamentary Finance Committee has tallied Iraq's external and internal debts, while affirming that the Parliament will cooperate with the government to pass the general budget law as quickly as possible.
The Budget Comes First... Parliament Pledges To Cooperate With The Government To Approve It Quickly, And The Parliamentary Finance Committee Reveals To NINA The Size Of Iraq's Debt
Baghdad / NINA / The Parliamentary Finance Committee has tallied Iraq's external and internal debts, while affirming that the Parliament will cooperate with the government to pass the general budget law as quickly as possible.
Committee member, MP Ahmed Hama Rashid, stated to the National Iraqi News Agency ( NINA ) that "the Financial Management Law stipulates that the general budget be submitted by the government to Parliament annually by mid-October," noting that "the general budget law in each parliamentary session reflects the government's vision, and Parliament's role is limited to oversight and ratification."
He added that "Parliament will cooperate with the government to pass the general budget law as quickly as possible," explaining that "the program-based budget does not require much time for approval, and Parliament can pass it in less than two months."
Regarding the debt issue and spending limits, the Finance Committee member emphasized that "Iraq needs to diversify its revenue sources, while austerity and cost-cutting measures require a bold step from the government."
He added, "The value of Iraq's outstanding external debt has reached $10 billion, and internal debt has exceeded 90 trillion dinars, in addition to accumulated debts from the era of the former regime amounting to another $41 billion, most of which are debts to Gulf countries, some in cash and others in logistical support." /End 5
https://ninanews.com/website/News/Details?Key=1312900
Positive Understandings Reached Between Erbil And Baghdad Regarding The 2027 Budget And The Resolution Of The Contract Employees Issue
Erbil (Kurdistan 24) - The finance committees from Erbil and Baghdad held a joint meeting on Thursday, September 3, 2026, chaired by the Federal Minister of Finance, Faleh al-Sari, to discuss the Kurdistan Region’s share in the draft federal general budget law for 2027.
The meeting, which lasted for about three hours, witnessed "positive and constructive" discussions that resulted in pledges from the Federal Ministry of Finance to resolve the issue of teachers and employees on contracts throughout Iraq, including the Kurdistan Region, by converting them to permanent staff within the draft budget law for next year.
A member of the negotiating delegation told Kurdistan 24 that the new draft budget will also include a clause related to "job promotions" for employees, stressing that employees of the Kurdistan Region will be included in this decision, just like their counterparts in the rest of the federal institutions.
The relevant authorities are scheduled to begin drafting the budget bill next Saturday, with the aim of completing it by September 15th for submission to the Federal Cabinet. The Cabinet will then have one month to review and approve the bill before sending it to the Federal Parliament in October for the necessary legislative procedures.
Oil Heads For Sharp Weekly Gain On US-Iran Tensions
2026-09-04 Shafaq News Oil prices rose on Friday, heading for their steepest weekly gain since mid-July, as rising tension and renewed U.S.-Iran hostilities heightened concerns over Middle East supply risks.
Brent crude futures rose 54 cents, or 0.6%, to $96.06 a barrel by 0100 GMT, while U.S. West Texas Intermediate crude futures climbed 80 cents, or 0.9%, to $92.10.
On a weekly basis, Brent rose 7.6% and WTI was 10.4% higher, set for the highest gains since the week ended July 20.
U.S. attacks this week that killed and wounded dozens, including Iranian civilians, marked the fiercest clashes between the two countries since July. The war, which began with U.S.-Israeli strikes in late February, is now in its seventh month.
Israeli Defence Minister Israel Katz renewed warnings that Israel would "cripple" Iran's military and civilian infrastructure, including energy facilities.
ANZ analysts raised their Brent crude forecast on Friday to $95 a barrel in the short term, with upside risk if the Middle East conflict intensifies.
"The market is entering a delicate adaptation phase. Elevated inventories helped absorb the initial supply crisis, but the challenge is now to keep the market balanced as those buffers diminish," the analysts said.
U.S. Vice President JD Vance told reporters on Thursday that Washington does not plan to hold talks with Iran unless Tehran stops attacking commercial shipping in the Strait of Hormuz.
Capping oil's advance, however, Russian President Vladimir Putin said there remained a path to a deal to end the war in Ukraine, adding that both the U.S. and China were prepared to support a peace settlement.
Meanwhile, Iran expanded its list of vessels it deems non-compliant and subject to fines, confiscation or detention if they attempt to transit the strait. Iraqi ships remain among the few vessels Tehran has cleared to pass through Hormuz.
Iraq increased its oil exports to around 2.34 million barrels per day in August from about 1.35 million bpd in July, two Iraqi energy officials said on Wednesday, with September exports also expected to increase as heavy discounts and Iranian approvals for Iraqi tankers encouraged buyers. (REUTERS)
https://www.shafaq.com/en/Economy/Oil-heads-for-sharp-weekly-gain-on-US-Iran-tensions
Gold Holds Steady Ahead Of US Payrolls Data
2026-09-04 Shafaq News Gold prices were steady on Friday and poised for a modest weekly gain, as traders' attention turned to key U.S. payrolls data for clues on the Federal Reserve's next interest rate decision.
Spot gold held its ground at $4,469.26 per ounce, as of 0633 GMT. Prices jumped 2% on Thursday as traders scaled back expectations for a September rate hike after Fed Governor Christopher Waller said he would support leaving rates unchanged if data continued to show inflation pressures moderating.
U.S. gold futures for December delivery fell 0.5% to $4,515.70.
Traders are pricing in an about 50% chance of a Fed rate hike later this month, according to the CME FedWatch Tool.
The U.S. nonfarm payrolls report is due at 1230 GMT.
"Weak figures and a rise in unemployment could weaken the case for a rate hike. In this case, gold could recover. However, the metal could remain exposed to changing sentiment, with inflation data releases coming next week," said Ross Maxwell, global strategy operations lead, VT Markets.
"The market continues to benefit from central bank demand, which could limit the extent of any decline."
Though gold is often viewed as an inflation hedge, elevated interest rates tend to weigh on the non-yielding asset.
Data on Thursday showed the number of Americans filing claims for unemployment benefits rose marginally last week amid low layoffs, pointing to stable labour market conditions.
Meanwhile, U.S. Vice President JD Vance said the fighting between Washington and Tehran was not a war and declined to provide a timeline for when the conflict would be over, underscoring the challenge the Trump administration faces as the hostilities enter their seventh month and mid-term elections loom.
Among other metals, spot silver fell 0.5% to $66.59 per ounce. Platinum lost 1.2% to $1,803.53 and palladium declined nearly 1.3% to $1,403.03, with both metals on track for slight weekly declines. (REUTERS)
https://www.shafaq.com/en/Economy/Gold-holds-steady-ahead-of-US-payrolls-data
Seeds of Wisdom RV and Economics Updates Friday Morning 9-4-26
Good Morning Dinar Recaps,
CHINESE BANKS RETURN TO U.S. TREASURIES: DOLLAR DEPOSITS REVEAL A SHIFT IN GLOBAL CAPITAL FLOWS
Chinese commercial banks are increasing purchases of U.S. Treasuries after attracting more dollar deposits, highlighting the complicated relationship between de-dollarization, dollar liquidity and global demand for U.S. government debt.
Good Morning Dinar Recaps,
CHINESE BANKS RETURN TO U.S. TREASURIES: DOLLAR DEPOSITS REVEAL A SHIFT IN GLOBAL CAPITAL FLOWS
Chinese commercial banks are increasing purchases of U.S. Treasuries after attracting more dollar deposits, highlighting the complicated relationship between de-dollarization, dollar liquidity and global demand for U.S. government debt.
OVERVIEW
Chinese Bank Shift: Chinese commercial banks have been buying U.S. Treasuries after raising interest rates on U.S. dollar deposits, according to sources cited by Reuters.
Dollar Liquidity Is Rising: China's foreign-exchange deposits reached approximately $1.18 trillion by the end of July, up 17.9% from a year earlier as exports and trade surpluses generated more dollar liquidity.
A Complicated Dollar Story: The development shows that China's financial system can pursue greater use of the yuan while Chinese banks simultaneously find U.S. dollar assets attractive, particularly when Treasury yields exceed returns available in China's domestic bond market.
KEY DEVELOPMENTS
1. Chinese Banks Are Buying Treasuries Again
Chinese commercial banks have increased purchases of U.S. Treasury securities in recent months, according to people familiar with the transactions.
The purchases follow an increase in the interest rates banks are offering customers on U.S. dollar deposits.
That represents an important shift in behavior because the banks are effectively attracting dollar liquidity from customers and then putting some of those dollars into U.S. government securities.
The development does not mean China has reversed its longer-term reduction in official Treasury holdings. Instead, it shows that commercial banks can respond to market incentives even while China's broader financial strategy continues to diversify.
2. Dollar Deposits Are Becoming More Attractive Inside China
Chinese banks have been raising rates on dollar deposits, with some smaller and foreign banks offering rates above 3% and in some cases approaching 4%, according to Reuters sources.
That compares with yuan deposit rates of roughly 0.95% at major state-owned banks.
The difference creates an incentive for Chinese customers to retain or increase dollar balances rather than immediately converting those funds into yuan.
For banks, those deposits also provide a pool of dollar funding that can be invested in relatively high-yielding U.S. Treasury securities.
3. China's Dollar Liquidity Has Increased Sharply
China's foreign-exchange deposits reached $1.18 trillion at the end of July, representing a 17.9% increase from a year earlier.
Reuters attributed the increase partly to China's strong exports and record trade surpluses.
That means a significant amount of dollar liquidity is accumulating within China's financial system—even as policymakers continue to manage the yuan and encourage development of alternatives to dollar-based finance.
This is one of the most important aspects of the story.
Dollar diversification does not necessarily mean immediate dollar disappearance.
Global financial systems can become more diversified while still maintaining substantial demand for dollars.
4. China's Official Treasury Holdings Tell a Different Story
The latest official Treasury data provide an important counterpoint.
China's reported holdings of U.S. Treasuries fell to approximately $633.4 billion in June, down from $659.3 billion in May and the lowest level since September 2008.
China remained the third-largest foreign holder of Treasuries, but its official holdings were down more than 13% from a year earlier.
Therefore, the new commercial-bank purchases should not be interpreted as proof that China's government has begun rebuilding its official Treasury position.
The more significant development is that private banking flows are responding to Treasury yields and dollar liquidity even while official Chinese Treasury holdings remain substantially below their historical levels.
5. The Global Capital-Flow Picture Is Becoming More Complex
This development comes at a time when the Treasury market itself is undergoing significant repricing.
U.S. Treasury yields have risen sharply, while Chinese domestic bond yields remain comparatively low. That makes dollar-denominated U.S. government securities more attractive to financial institutions seeking yield on their dollar assets.
The result is an increasingly complicated global capital picture:
China accumulates dollar liquidity → banks attract dollar deposits → some dollars move into Treasuries → Treasury demand receives support.
At the same time:
China continues developing alternative payment and reserve arrangements → official Treasury holdings remain below historical levels → global financial diversification continues.
These developments can happen simultaneously.
WHY IT MATTERS
Economy
China's enormous trade surplus generates substantial foreign-exchange liquidity.
How that liquidity is held and invested can influence both China's currency management and the international financial system.
Markets
The development demonstrates that Treasury demand does not come only from foreign governments and central banks.
Commercial banks, corporations, investment funds and private investors can also become important channels through which international dollars ultimately flow into U.S. government debt.
Policy
Chinese policymakers face a delicate balance.
A stronger yuan can reduce the cost of imports and increase purchasing power, but rapid appreciation can create challenges for exporters and domestic economic conditions.
Encouraging dollar deposits can help banks manage dollar liquidity while potentially reducing pressure for those dollars to be immediately converted into yuan.
Global System
The most important takeaway may be that the global monetary system is becoming more complex rather than simply moving from one currency to another.
China can promote yuan internationalization and alternative financial infrastructure while Chinese financial institutions continue using dollars and U.S. Treasury securities when market conditions make them attractive.
WHY IT MATTERS TO FOREIGN CURRENCY HOLDERS
Dollar demand: Rising dollar deposits in China demonstrate that international demand for dollars can remain strong even while countries pursue currency diversification.
Treasury yields: Higher U.S. yields can attract foreign financial institutions seeking better returns on dollar assets.
Currency values: Capital moving between dollars, yuan and other currencies can influence exchange rates and the relative purchasing power of currencies.
Capital flows: Foreign-currency holders should watch where international dollar liquidity is moving—not simply whether a country officially increases or decreases its Treasury holdings.
Diversification:The larger trend is toward a more complicated currency system in which multiple currencies and financial assets can coexist rather than one immediately replacing another.
IMPLICATIONS FOR THE GLOBAL RESET
Pillar 1: Assets
The Treasury market remains a major destination for global capital even as countries diversify their reserve and payment systems.
China's commercial-bank activity demonstrates that dollar assets can continue attracting capital because of yield and liquidity, even while official institutions reduce their exposure.
That makes the future of the Treasury market a key indicator of how global investors are reallocating capital.
Pillar 2: Trade
China's expanding dollar liquidity is closely connected to its export strength and trade surplus.
Trade generates the foreign currency that financial institutions must ultimately hold, convert or invest.
As global trade becomes more diversified geographically and financially, the question is increasingly not simply which currency dominates trade, but where the resulting foreign-currency liquidity is ultimately invested.
CONCLUSION
The latest Chinese banking activity challenges the idea that global financial diversification is a simple story of “China abandoning the dollar.”
The evidence points to something considerably more complicated.
China's official Treasury holdings have fallen dramatically from their historical highs, yet Chinese commercial banks are now attracting more dollar deposits and purchasing U.S. Treasuries because the returns can be attractive relative to China's domestic bond market.
That creates an important distinction between de-dollarization and reduced dollar usage.
The global financial system may be moving toward greater currency diversification without eliminating the dollar's role in trade, banking, liquidity and investment.
For foreign currency holders, that is an important distinction. The next phase of the global monetary system may be defined less by one currency replacing another and more by competing currencies operating within a more diversified global capital structure.
China's relationship with the dollar is not simply disappearing—it is changing, and the movement of those dollars may tell us more about the future financial system than official reserve headlines alone.
Seeds of Wisdom Team
Newshounds News™ Exclusive
SOURCES
Reuters — “Chinese banks purchasing Treasuries after wooing dollar deposits, sources say”
U.S. Department of the Treasury — “Treasury International Capital Data for June”
~~~~~~~~~~
🌱 A Message to Our Currency Holders🌱
If you’ve been holding foreign currency for many years, you were not foolish.
You were not wrong to believe the global financial system would change.
What failed was not your patience — it was the information you were given.
For years, dates, rumors, and personalities replaced facts, structure, and proof. “This week” predictions created cycles of hope and disappointment that were never based on how currencies actually change.
That is not your failure.
Our mission here is different: • No dates • No rates • No hype • No gurus
Instead, we focus on:
• Verifiable developments • Institutional evidence
• Global financial structure • Where countries actually sit in the process
Currency value changes only come after sovereignty, trade, banking, settlement systems, and fiscal coordination are in place. History and institutions confirm this sequence.
You will see silence. You will see denials. That is not delay — that is discipline.
Protect your identity. Organize your documents. Verify everything.
Never hand your discernment to anyone who cannot show proof.
You deserve truth — not timelines.
Seeds of Wisdom Team
Newshounds News
~~~~~~~~~~
Seeds of Wisdom Team RV Currency Facts Youtube and Rumble
Newshound's News Telegram Room Link
RV Facts with Proof Links Link
RV Updates Proof links - Facts Link
Start Here room with Most Asked Questions Link
Follow the Gold/Silver Rate COMEX
Follow Fast Facts
Seeds of Wisdom Team™ Website
Thank you Dinar Recaps
Iraq Economic News and Points To Ponder Thursday Evening 9-3-26
A silent crisis is hitting private banks... and a source warns: "Al-Taif" may not be the last.
Last updated: September 3, 2026 Al-Mustaqilla / Special / - Iraqi private banks are entering a very sensitive phase, amid warnings of widening liquidity problems and the inability of some banking institutions to meet their obligations to their depositors, at a time when the sector is undergoing a broad restructuring and evaluation process led by the Central Bank of Iraq.
A silent crisis is hitting private banks... and a source warns: "Al-Taif" may not be the last.
Last updated: September 3, 2026 Al-Mustaqilla / Special / - Iraqi private banks are entering a very sensitive phase, amid warnings of widening liquidity problems and the inability of some banking institutions to meet their obligations to their depositors, at a time when the sector is undergoing a broad restructuring and evaluation process led by the Central Bank of Iraq.
An informed banking source revealed to Al-Mustaqila that the situation within a part of the private banking sector is going through one of its most difficult phases in recent years, warning that the problems that have appeared in Al-Taif Islamic Bank may not be an isolated case, according to his assessment.
The source said that there are other private banks facing varying degrees of financial and liquidity pressures, noting that there are complaints from depositors about delays in receiving their money or difficulty in withdrawing amounts from their accounts at some banks.
He added that “there are cases whose details have not been officially announced to the public yet,” calling on the Central Bank of Iraq to intensify its scrutiny of the financial solvency and actual liquidity of private banks, and to ensure their ability to return depositors’ money on demand.
Is "The Spectrum" The Beginning Of A Bigger Project?
These warnings come after the Central Bank of Iraq’s decision on September 2, 2026, to place Al-Taif Islamic Bank for Investment and Finance under receivership for 18 months, after confirming the existence of “serious violations” that affected the bank’s financial position and depositors’ funds.
This decision gives an indication that regulatory authorities are becoming more stringent in dealing with banks whose financial situations may pose a risk to depositors' funds or to the integrity of banking operations.
But the source from “Al-Mustaqilla” goes further, as he believes that the need today is not to address the situation of just one bank, but rather to conduct a comprehensive review of the conditions of private banks that show signs of weakness in liquidity or failure to meet their obligations towards customers.
Depositors Are Waiting For Their Money.
According to information obtained by “Al-Mustaqila”, one of the most prominent indicators that warrants regulatory investigation is the existence of complaints related to the difficulty of some depositors obtaining their full funds immediately in a number of banks.
The source emphasizes that any repeated delays or unjustified restrictions on withdrawals should prompt regulators to check the bank’s financial position and match the amount of liquidity available with its obligations to the public.
Al-Mustaqilla cannot currently confirm the number of banks facing such problems independently, and the Central Bank of Iraq has not yet issued an official statement indicating that “dozens of banks” are suffering from conditions similar to Al-Taif Bank.
Therefore, this information remains within the framework of what the banking source revealed to “Al-Mustaqila” and requires regulatory scrutiny and official disclosures that determine the true extent of the problem.
Banking Reform Could Change The Landscape Of The Sector
The current concerns come in conjunction with the largest private banking sector reform program in Iraq in recent years.
The Central Bank had announced that Iraqi banks were required to choose one of three paths within the reform program: to continue as an independent banking institution, to merge with other banks, or to exit the market, with the banks subject to assessments related to minimum requirements, governance, compliance and financial performance.
This means that the current Iraqi banking landscape may not remain the same in the coming period, especially with the continuation of auditing processes and the identification of banks capable of meeting the new requirements.
The Central Bank previously confirmed that the reform process aims to raise the levels of compliance, governance and transparency, improve institutional performance and enhance the resilience of the banking sector.
The Decline In Deposits Increases The Sensitivity Of The Current Phase.
The issue becomes more sensitive with the decline in total bank deposits during the first months of the year.
According to official data published in August, total deposits in Iraqi banks amounted to about 104.296 trillion dinars by the end of May 2026, down from 104.727 trillion in April and 105.090 trillion in March, meaning that deposits recorded a decline for three consecutive months.
This decline in itself does not mean there is a full-blown banking crisis, but it makes the issue of confidence, liquidity, and the ability of banks to meet withdrawal requests more important for regulators.
Source To Al-Mustaqilla: Protecting Depositors Must Be The Priority
The source calls on the Central Bank of Iraq to take clearer steps towards banks that prove unable to meet their obligations, stressing that protecting citizens’ money must take precedence over any other consideration.
He added that addressing problems in their early stages can prevent the crisis from spreading from a single bank to a wider loss of confidence in the private banking sector.
The source stresses that the anticipated measures, in his opinion, should include a review of the actual liquidity size, the ratio of deposits to liquid assets, non-performing loans, transfers and transactions with parties related to the bank, in addition to each bank’s ability to meet customer withdrawals without delay.
The Most Serious Question Is: How Many Banks Might Face The Same Fate?
So far, there is no official list of other banks that will be placed under guardianship or liquidation, and it cannot be said with certainty that the situation of Al-Taif Bank applies to other banking institutions.
But the guardianship decision, in parallel with the reform program that presents banks with options to continue, merge or exit, makes the next stage open to decisions that may completely redraw the map of the Iraqi banking sector.
The Questions That Remain Are:
Are there really other banks that are unable to meet the demands of their depositors?
What is the amount of money that might be at risk?
Will the central bank announce the results of its evaluation of banks transparently to the public?
Will the guardianship of Al-Taif Bank be an isolated case, or the beginning of a series of broader banking measures?
https://mustaqila.com/أزمة-صامتة-تضرب-المصارف-الأهلية-ومصدر/
The Disappearance Of Small Denomination Coins Is Causing "Daily Disruption" In Iraqi Markets.
2026-09-03 Shafaq News - Kirkuk Local markets in Kirkuk Governorate are experiencing increasing difficulty in obtaining small denomination banknotes of 250, 500 and 1000 dinars, amid complaints from traders and citizens about their scarcity in daily transactions.
Shop owners say that what is available is often old, worn out or torn, which makes it more difficult to use in buying and selling operations
At first glance, the problem seems to contradict the available figures on the volume of small banknotes in Iraq, as recent data indicates the existence of hundreds of millions of banknotes of these denominations.
However, their presence in the monetary data does not necessarily mean that all of them are actually available for circulation or in good condition, which raises questions about the cash cycle and the mechanisms for withdrawing damaged banknotes, replacing them, and injecting new alternatives into the markets.
Daily Confusion
Abbas Ahmed, a shop owner in the Doctors Street market in Kirkuk, told Shafaq News Agency, "Obtaining 250, 500, and 1000 dinar notes has become more difficult than before, and the problem becomes clear when a customer pays their bill in large denominations, forcing us to ask the customer to buy another item with the remaining amount."
He points out that some of the small bills that arrive at the shops are in poor condition, as they are torn, dirty, or worn out as a result of frequent handling, which makes it difficult for some merchants and citizens to accept them.
He adds: "The continuation of this creates daily confusion in the markets, especially for shops that deal with large numbers of customers," stressing that the problem is not related to the value of the small banknote as much as it is related to its role in completing commercial transactions.
For his part, Samir Abdullah, the owner of a currency exchange shop on Al-Jumhuriya Street in Kirkuk, told Shafaq News Agency that the demand for small denominations has increased significantly, while it is difficult to provide them in the quantities needed by the market.
It shows that citizens and merchants resort to exchange shops to obtain small denominations, but the available quantities are not stable, and the problem increases when the papers offered for exchange are in a damaged condition.
He adds that small banknotes are passed between large numbers of people in a short period, which makes them more susceptible to damage compared to larger denominations, noting that some of the banknotes that reach the banking system need to be replaced instead of being put back into circulation.
Abdullah believes that the solution is not limited to injecting new banknotes only, but also requires withdrawing damaged banknotes from circulation on a regular basis, because their continued existence reduces the amount of usable cash even if official figures indicate the existence of large numbers of these denominations.
In the Citadel market in Kirkuk, wholesalers face the same problem. Hamza al-Jabari, the owner of a wholesale shop, told Shafaq News Agency that the shortage of small denominations has become part of daily transactions in the market.
He adds: "Wholesale and retail sales sometimes require returning small amounts to customers, but the lack of these amounts leaves the merchant with limited options, including rounding the price or adding another item instead of the remaining cash amount."
He points out that some traders keep the 250, 500 and 1000 dinar notes they receive and do not use them in other transactions except when necessary, for fear that they will not be able to obtain them again, which in turn leads to a reduction in the movement of these denominations within the market.
He points out that "the problem seems simple from a financial standpoint, but its effects expand when it is repeated thousands of times daily, especially in popular markets, food stores, bakeries, transportation, and other activities that depend on direct cash transactions."
Hundreds Of Millions Of Papers
The latest estimates published in 2026 indicate that the volume of small denomination banknotes does not necessarily reflect what the average citizen sees in the market.
According to Shafaq News Agency’s monitoring of cash issuance data, the number of 1000 dinar notes increased from 718 million notes in 2022 to 775 million notes in 2026, while the number of 250 dinar notes increased from 795 million notes to 818 million notes during the same period, while the 500 dinar note decreased slightly from 147 million notes to 145.4 million notes.
Thus, the total number of banknotes of the three categories amounts to approximately 1.738 billion banknotes according to these estimates for 2026, compared to approximately 1.660 billion banknotes in 2022, an increase of approximately 78.4 million banknotes.
The figures show that the 1,000 dinar denomination recorded an increase of about 57 million notes, while the 250 dinar denomination increased by about 23 million notes, while the 500 dinar denomination decreased by about 1.6 million notes.
However, these figures do not mean that all 1.738 billion banknotes are in citizens' pockets or store safes and in good condition for circulation.
They reflect the number of banknotes within the monetary issuance data and do not represent a field survey of the actual quantity of banknotes in circulation or the percentage of damaged ones. This is a crucial point when explaining the problem of the shortage of small denominations.
The Central Bank of Iraq still includes the 250, 500 and 1000 dinar denominations among the officially circulating banknotes, confirming when issuing the second edition of banknotes that the previous banknotes will continue to circulate alongside the new issues, without any intention of withdrawing them from circulation.
Damaged Problem
Economic expert Ali Khalil told Shafaq News Agency that the problem of small denominations should not be measured only by the number of notes issued by the Central Bank, but by the number of notes that are actually valid for circulation.
He says that small batches are subject to high rates of consumption and damage due to their frequent transfer between individuals, and therefore part of the exported quantity may have gone out of circulation or become in need of replacement.
He adds that "the presence of more than one billion banknotes of the three categories within the monetary data does not necessarily mean that there is a surplus of them in the markets, because a banknote that becomes damaged loses its practical ability to perform its function, even if it remains counted within the number of banknotes that were issued."
He points out that addressing the problem requires strengthening mechanisms for replacing damaged banknotes, ensuring that new banknotes reach the markets continuously, and monitoring the movement of cash between banks, exchange offices, and merchants.
Khalil confirms that "the shortage of small denominations is reflected in daily pricing, and may lead to inaccurate approximation of prices, which can sometimes burden the consumer with small additional amounts, but it becomes significant when it is repeated continuously"
Central Bank Instructions
Official data indicates that the Central Bank of Iraq already has specific mechanisms for dealing with damaged banknotes, as it has published official standards for their replacement, which include different conditions and procedures depending on the nature of the damage to the banknote.
An official electronic service is also available through the Ur portal for submitting requests to replace damaged banknotes at the Central Bank of Iraq, allowing citizens to submit their requests according to the approved procedures.
These procedures indicate that dealing with damaged banknotes is not the responsibility of the citizen alone, but is part of the cash management system that includes banks, the central bank, and mechanisms for withdrawing invalid banknotes and replacing them with banknotes that are negotiable.
In 2020, the Central Bank issued a decision to reinstate the penalty for shortages on small denominations, namely 1000, 500 and 250 dinars, effective from October 1, 2020, in accordance with the instructions on standards for the circulation and exchange of banknotes and counting and sorting mechanisms.
This reflects the monetary policy's interest in providing small denominations in the monetary system, given their widespread use in daily transactions.
Citizens Face A "Change" Crisis
Suhad Ibrahim, an employee, told Shafaq News Agency that citizens are the most affected by the problem because they cannot control the availability of small denominations when they buy their daily needs.
She adds that the customer may pay more than the value of the item, but sometimes does not receive the full change, or is forced to buy something else so as not to lose the remaining amount, noting that this problem is repeated in shops, markets and means of transportation.
She explains that providing small change in good condition will make everyday transactions easier, especially for employees and low-income earners who deal with small amounts frequently.
Between Numbers And Reality
The problem of small change reveals a potential gap between the amount of cash recorded in the monetary issuance data and the cash actually available for daily circulation in good condition.
Available figures indicate that there are hundreds of millions of banknotes in denominations of 250, 500 and 1000 dinars, but traders in Kirkuk say they are having difficulty obtaining them, while money changers confirm that part of what they receive is damaged or worn out.
Therefore, the question that arises is not only about the number of notes issued, but also about the volume of notes that are actually valid for trading, the amount that was withdrawn from the market due to damage, and how quickly it was replaced with new notes.
Economists believe that addressing the problem requires more detailed data on the number of damaged banknotes withdrawn annually, the quantities of new banknotes injected into each denomination, and their geographical distribution among the governorates.
With a large segment of Iraqis continuing to rely on cash transactions, small denominations remain an essential part of daily economic life, despite their low nominal value.
While available data shows an increase in the number of 250 and 1000 dinar notes since 2022, and a slight decrease in the 500 dinar note, market complaints indicate that the real challenge lies in the availability of these notes in good condition and in the right place and time.
Hence, there seems to be a need to strengthen the cycle of replacing damaged currency, and to ensure that small denominations have access to banks, exchange offices and markets, in order to prevent the problem of "change" from turning into a daily crisis for both the citizen and the merchant.
The Candlestick Makers Are Back, and This Time They're Not Joking
The Candlestick Makers Are Back, and This Time They're Not Joking
Notes From the Field By James Hickman (Simon Black / Sovereign man) September 3, 2026
In 1845, the French economist Frédéric Bastiat petitioned parliament on behalf of the nation's candlestick makers. They were being ruined, he wrote, by an unscrupulous rival that was flooding the market with light at a price no honest candlestick maker could match.
The Candlestick Makers Are Back, and This Time They're Not Joking
Notes From the Field By James Hickman (Simon Black / Sovereign man) September 3, 2026
In 1845, the French economist Frédéric Bastiat petitioned parliament on behalf of the nation's candlestick makers. They were being ruined, he wrote, by an unscrupulous rival that was flooding the market with light at a price no honest candlestick maker could match.
This light-producing rival, of course, was the sun.
And Bastiat satirically demanded "a law requiring the closing of all windows, dormers, skylights, inside and outside shutters, curtains… in short, all openings, holes, chinks and fissures" to ensure that no sunlight could enter French homes.
Think of the jobs this would create. "If more tallow [curtains] be consumed, there will arise a necessity for an increase of cattle and sheep," the petition argued. "Thousands of vessels would soon be employed in the whale fisheries [for oil]."
Bastiat, one of history's most famous proponents of free markets, was obviously joking. He wrote the petition to mock the tariff wall that sheltered France's industries from cheap foreign goods— block the cheaper competitor, protect the domestic producer, count the jobs saved.
No one counted the cost of protectionism: everyone else paying more for everything, and the whole country became poorer.
Yet decade after decade since, every new innovation has been met with exactly this kind of uproar. And nobody is joking.
It wasn't so long ago that taxi drivers were up in arms over Uber undercutting their prices. In June 2015, nearly 3,000 of them shut down parts of Paris, burning tires and blocking airport roads, because Uber's cheap service didn't require the professional taxi license that could cost $270,000.
The French government caved within a day, ordering police to seize the unlicensed Uber drivers' cars.
Now the wheel has turned. Waymo's robotaxis launched in Atlanta in June 2025, bookable through the Uber app of all places. And Uber drivers say the competition is cutting their pay.
Naturally the Atlanta Rideshare Drivers Union wants the city to slap a $0.50 to $1.00 fee on every robotaxi ride, paid into a "driver transition fund," plus a ban on robo pickups at the Atlanta airport.
If only they could tax the sun for the candlestick makers.
The federal government runs the same play, just bigger.
In January 2025, the Commerce Department finalized its ‘Connected Vehicle Rule’, which bans cars with Chinese-linked software from the US market, starting with the 2027 model year.
The stated reason is national security: keeping foreign adversaries out of the cameras, microphones, and GPS units on American streets.
That's a real concern, to be fair. But then came the carve-outs.
Volvo, majority-owned by China's Geely, got authorization in May to keep selling. Ford, after talks with the department, decided its China-built Lincoln Nautilus doesn't need an exemption at all.
But Polestar— owned by the same Chinese parent as Volvo— was shut out and is leaving the US market.
The Commerce Department doesn't publish these decisions or its reasoning, so nobody outside the building knows why one Geely brand got a green light and the other got kicked out of America.
Let’s be honest: if these Chinese cars were really a security threat, there would be no carve-outs to negotiate. There would be a flat ban. No exceptions.
The real threat of cheap Chinese cars is to the profits of American automakers; Chinese cars are very inexpensive— like a decent quality mid-size SUV for around $20k. So many US buyers would start driving Chinese that the American automakers would either have to adapt and compete... or suffer catastrophic losses.
The end result of these bans is less competition, meaning Americans end up paying more for their vehicles.
Just add this to the long list of things which governments, from city councils to federal regulators, make more expensive.
Yesterday we wrote about how federal influence over local building codes adds $132,000 to the average new home.
Today it's how they're making buying a car and taking a quick trip more expensive.
Ask California how it's doing on that nonexistent high-speed rail… $15 billion and 18 years in, without a mile of track. Or ask Europeans, where climate fuel mandates are already tacking surcharges onto every plane ticket.
The receipts are everywhere: everything the government touches becomes more expensive.
College tuition is up about 1,200% since 1980— the surge began as soon as the federal government made itself the nation's student lender.
Since Obamacare passed, the average family health insurance premium has nearly doubled.
Even junk food became more expensive due to government food subsidies; in fact the moment 18 states pulled soda and snacks off the food stamp list, PepsiCo cut prices on Doritos and Lay's by up to 15%.
Housing, transportation, food, healthcare, education— all swamped by government interference, all quickly became less affordable.
And underneath all of it, bringing the whole pot to a boil, is the inflation that politicians and regulators caused with their own spending.
Yet who do they blame? Greedy corporations.
Inflation has nothing to do with greed. It has everything to do with incompetence and irresponsibility.
Bastiat's joke was that nobody would ever actually file the candlestick makers' petition. Yet 181 years later, what started as satire is taking place every single day.
A political class that treats cheaper goods and services as a threat is deliberately choosing to make the country poorer.
To your freedom, James Hickman Co-Founder, Schiff Sovereign LLC
PS: A government that treats cheaper as a threat isn't going to start choosing growth anytime soon. That's exactly why we publish Plan B Confidential— our flagship research on legal, practical ways to diversify your savings, your income, and even your residency beyond any single government's bad decisions.
Reset Intelligence: Level Playing Field
Reset Intelligence: Level Playing Field
9-3-2026
Level Playing Field
By Reset Intelligence | @EXIT_FIAT
The G20 closed in Asheville with the loudest clips doing the least work. The US Treasury Secretary put exchange rates on the official record as a policy-choice cause of global imbalances, and the word he used for the destination was equilibrium.
Reset Intelligence: Level Playing Field
9-3-2026
Level Playing Field
By Reset Intelligence | @EXIT_FIAT
The G20 closed in Asheville with the loudest clips doing the least work. The US Treasury Secretary put exchange rates on the official record as a policy-choice cause of global imbalances, and the word he used for the destination was equilibrium.
Within the same 48 hours, his department told Japan its currency sits below its fundamentals and should rise, and told Iran its money is finished.
The Three Lines
Hosting the world’s 20 largest economies, Scott Bessent read a negotiated text into the record. Global imbalances do not arise by accident. They are the cumulative result of policy choices on savings, consumption, investment, subsidies, market access, and exchange rates. They matter most when they are excessive, persistent, and larger than the fundamentals warrant. And the objective of the whole G20 workstream is to identify which policy choices can restore equilibrium.
The members agreed the test, agreed the harm hits surplus and deficit economies alike, and handed the IMF and the OECD the job of watching for the gaps. The Chair’s Statement also wrote free, safe and predictable navigation through the Strait of Hormuz into the G20’s own record.
The Loud Half of the Same Treasury
The clips that traveled were about Iran. Bessent told the regime on worldwide television that Treasury knows its British Virgin Islands trust accounts and its $100 million houses, promised a bank sanction this week and another the week after, and said the regime’s stolen assets go back to the Iranian people or to the victims of its terror. He also said the sentence printed on the cover of our book: we are burying the head of the Iranian snake.
The Board Kept Moving
• Kurdistan payroll – public salaries came off cash on September 1, routed onto bank cards through the MyAccount system
• Parliament – the new legislative term is set to open within days, with the vote on the 9 remaining cabinet posts to follow
• The central bank – Tuesday’s deposit auction ran routine at 5.25%, the quiet posture that holds until the day it does not
• The 2027 budget – the paper that writes the dinar’s value into law stays on schedule for parliament by mid-September
• Venezuela – the National Assembly backed the US oil arrangement as Energy Secretary Wright arrived in Caracas to advance it
That is the short version. The full briefing walks the three lines of the speech, the yen precedent, what the 20 signed, and why a currency held below its fundamentals for 2 decades is the textbook entry under the test the referees just agreed – with every source verified.
The referees just published the rule. The only question left is who is positioned when the whistle blows.
Read the full daily briefing free for 5 days. Sign up here: resetintelligence.com
https://dinarchronicles.com/2026/09/03/reset-intelligence-level-playing-field/